


Sany Heavy Equipment International Holdings closed at HK$6.53 after the Q3 2026 earnings release, capping a week where the stock slipped about 13%. The headline print is solid for a heavy machinery player, with total Q3 revenue of C¥7,421.351 million and net income of C¥446.29 million. However, the share price reaction tells a more cautious story.
The real tension sits on valuation. The business trades on a P/E of 10.5x versus a peer average of 8.3x, while a trailing cash flow model points to HK$1.31 per share, which is well below where the stock now changes hands.
Like the quality of Sany Heavy Equipment International Holdings' earnings profile but uneasy about paying a premium multiple for it? Check out the 197 high quality undervalued stocks if you want a shortlist of companies that pair solid fundamentals with more modest pricing.
Q3 2026 Earnings Summary
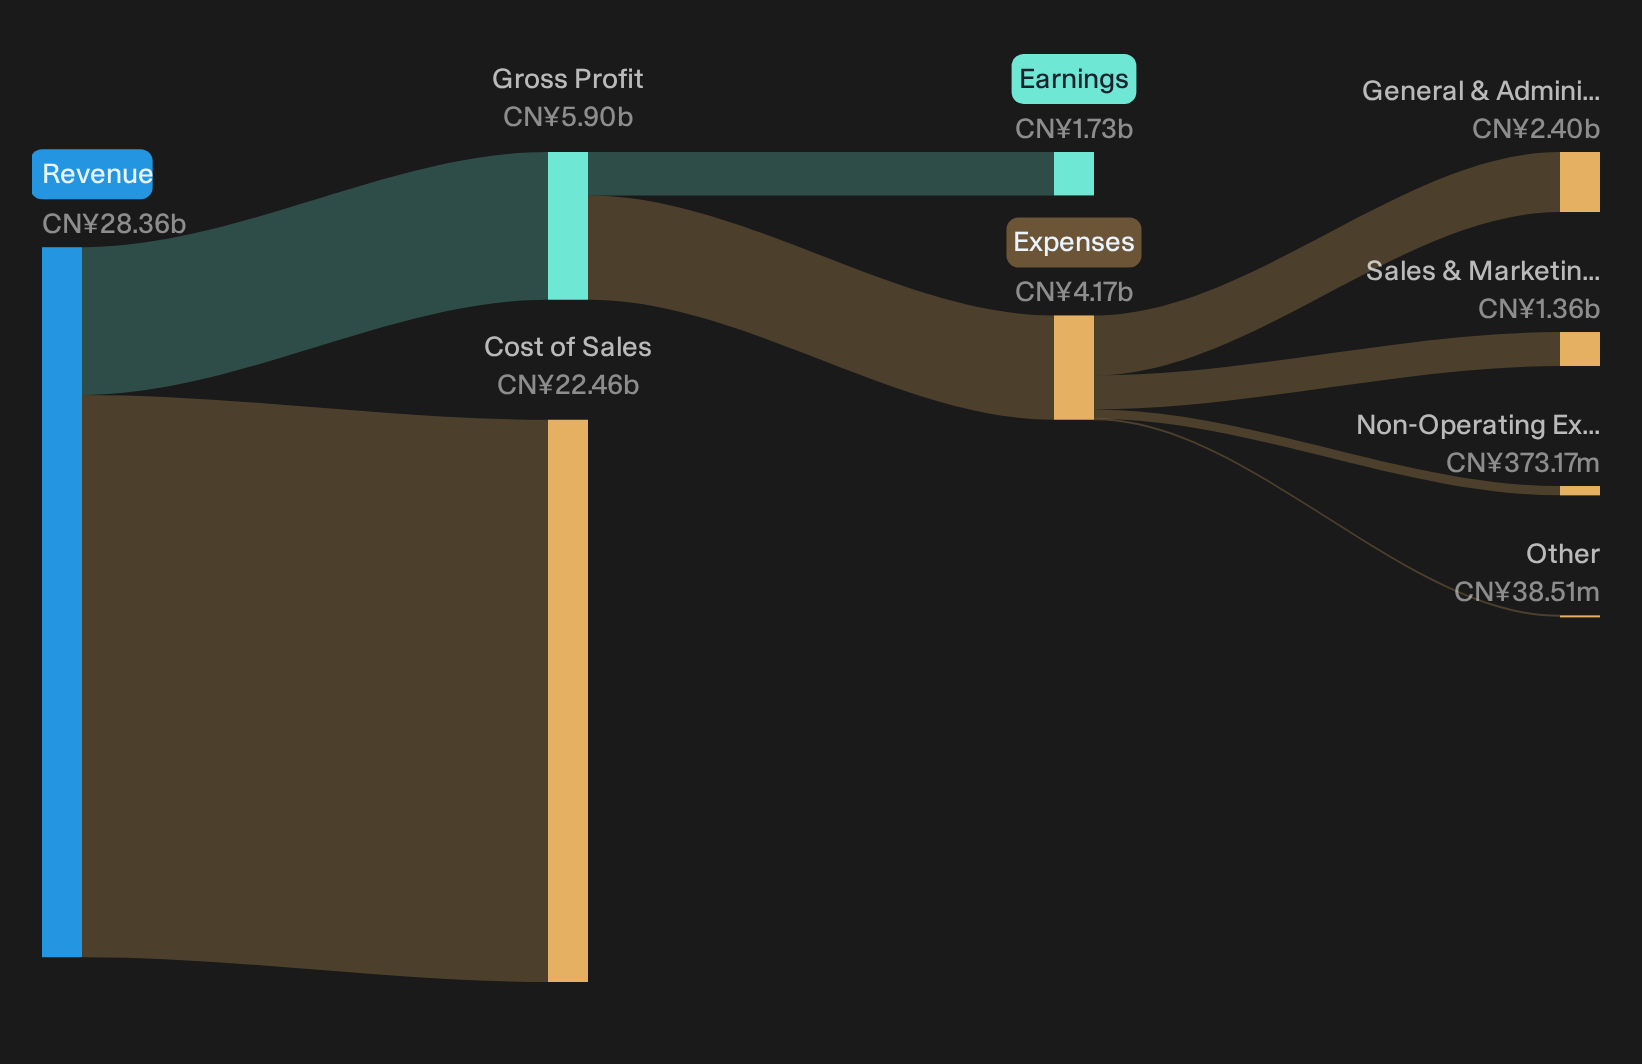
- Revenue (Q3 2026 vs. Q3 2025): C¥7,421.351 million vs. C¥5,910.113 million (up about 25.6%)
- Net Income (Excl. Extra Items, Q3 2026 vs. Q3 2025): C¥446.29 million vs. C¥414.095 million (up about 7.8%)
- Basic EPS (Earnings Per Share, Q3 2026 vs. Q2 2026): C¥0.135661 vs. C¥0.21527 (down about 37.0%)
- Trailing 12-Month Net Profit (Excl. Extra Items, Q3 2026 vs. Q3 2025): C¥1,734.192 million vs. C¥1,420.215 million (up about 22.1%)
Earnings are growing much faster than revenue and margins ticked higher. Ask Charlie what drives Sany Heavy Equipment’s faster earnings growth.
Revenue Momentum Backs Smart Mining Story
Sany Heavy Equipment shows a top line that is moving in the right direction, with Q3 revenue at C¥7,421.351 million compared with C¥5,910.113 million a year ago. Trailing 12 month profit excluding extras also sits above the prior period at C¥1,734.192 million versus C¥1,420.215 million. That combination helps the automation and smart mining narrative. The broader industrial platform is not just a concept. The recent framework agreements around parts and after sales support add some backup for a steady installed base and service income.
Profit Mix And Share Price Signal Caution
The picture is not one way. Basic EPS fell from C¥0.21527 in Q2 2026 to C¥0.135661 in Q3, so headline profitability per share softened even as revenue stayed firm. The stock has slipped over the last week, month, and quarter, which shows investors are questioning the quality or sustainability of recent earnings. That mix fits a cautious view. The underlying industrial engine is working, but the market is pushing back on how much to pay for cyclical and emerging industry exposure.
Are you convinced the underlying industrial engine at Sany Heavy Equipment International Holdings still deserves a premium, or think the re rating has further to run? Check the consensus price target analysis for Sany Heavy Equipment International Holdings.
Hunt For Pricing Disconnects
Sany Heavy Equipment International Holdings highlights how earnings and share prices can diverge for extended periods. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 39% below our estimate - focuses on higher fee private strategies that convert diverse fundraising channels into recurring management income.
- Company 2 - 38% below our estimate - targets essential infrastructure assets that benefit as electrification projects and data traffic increase network demands.
- Company 3 - 21% below our estimate - secures multi year shipbuilding orders that lock in demand for cleaner fuel vessels and specialised projects.
Three companies from the same screener. Open every one of the 197 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com