


Burlington Stores has had a choppy ride lately, yet the real question for you today is whether its current share price makes sense given what the retailer is earning.
- Over the past 3 years the stock has gained 92.0%, which now puts more pressure on its earnings profile to justify where the market is pricing the business.
- The retailer’s off-price model depends heavily on how efficiently it converts sales into profit and cash, which can influence how much investors are prepared to pay for each dollar of earnings.
- The analysts covering Burlington Stores have run their own numbers. See what analysts think Burlington Stores's shares could be worth.
The issue now is whether Burlington Stores' current valuation is adequately supported by its earnings power today and what those earnings are expected to deliver over time.
If you want a quick comparison of how other stocks are priced based on their earnings profile, compare Burlington Stores to companies in the 30 high quality undervalued stocks.
Does Burlington Stores Look Pricey on Earnings?
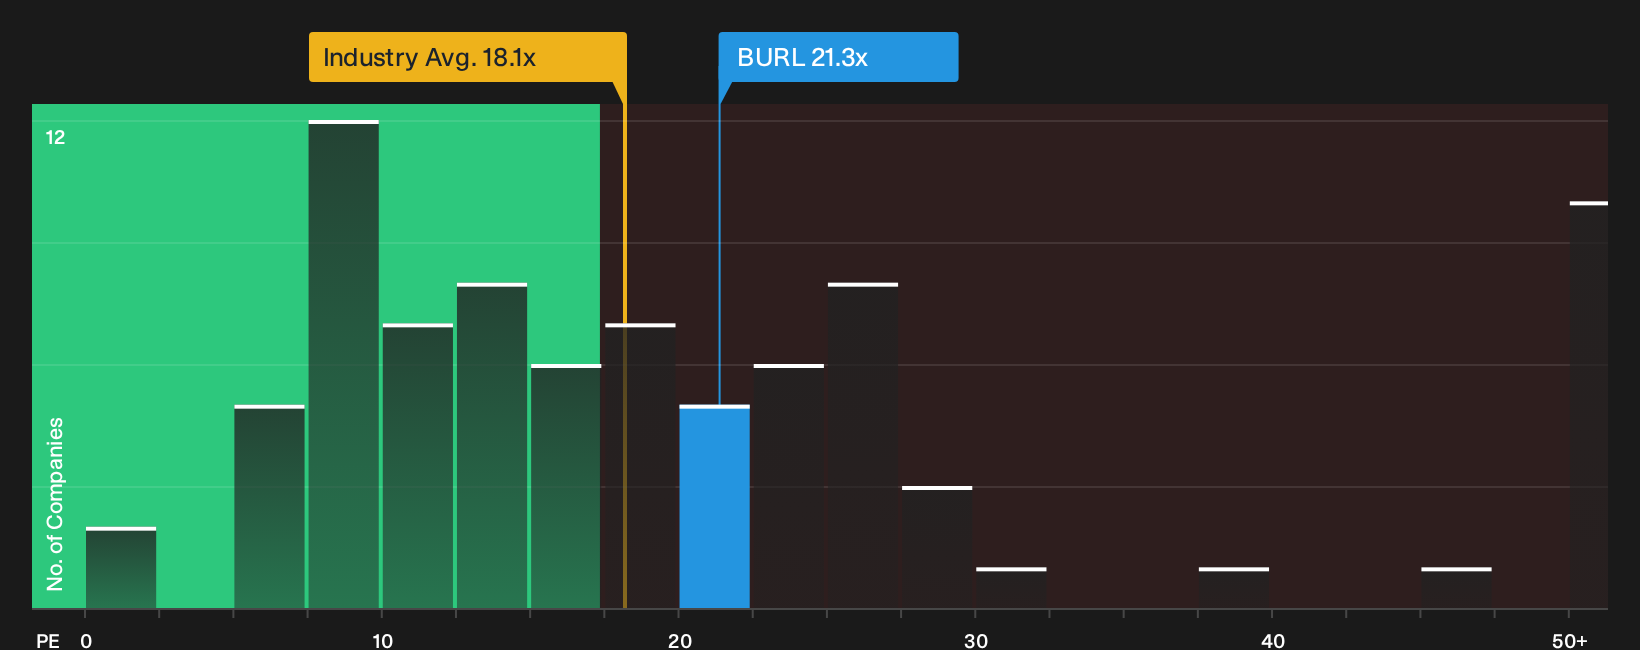
The P/E ratio suits Burlington Stores because earnings are a key lens for a mature retailer where profit quality matters as much as sales growth. The stock trades on about 21.3x earnings, which is modestly above the specialty retail group on roughly 18.1x and well ahead of the peer average near 13.6x. That kind of gap means investors are already paying a premium for Burlington Stores' earnings stream, rather than treating it as a plain vanilla retailer.
The fair multiple implied by the tailored model that weighs Burlington Stores' scale, margins and risk profile sits below the current 21.3x, so the shares screen as overvalued on this approach. To justify paying that higher P/E, an investor would need to be comfortable that the retailer can keep converting its off price model into earnings power that matches or exceeds what is reflected in this richer valuation. Explore the numbers behind Burlington Stores's P/E valuation.
The Burlington Stores Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Burlington Stores' valuation question leaves off by spelling out which paths for sales growth, margins and earnings would need to occur for the current share price to look either generous or conservative. Each scenario links a fair value estimate to a particular story about Burlington Stores' potential catalysts and key risks, so you can track over time which version feels closest to what the business is actually delivering.
One of the top community narratives on Burlington Stores: 34% undervalued
"Accelerated small box expansion and relocations, with 178 gross new stores opened in the 12 months to Q2 2026 and the fleet up 13%..."
Discover why this Narrative puts Burlington Stores at 34% undervalued.
One more angle on Burlington Stores that could change how you see the stock
Everything so far has focused on what Burlington Stores looks like today. However, there is a separate set of expectations that compares this price to where specialists think the business might be a few years from now. Explore where analysts expect Burlington Stores to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com