


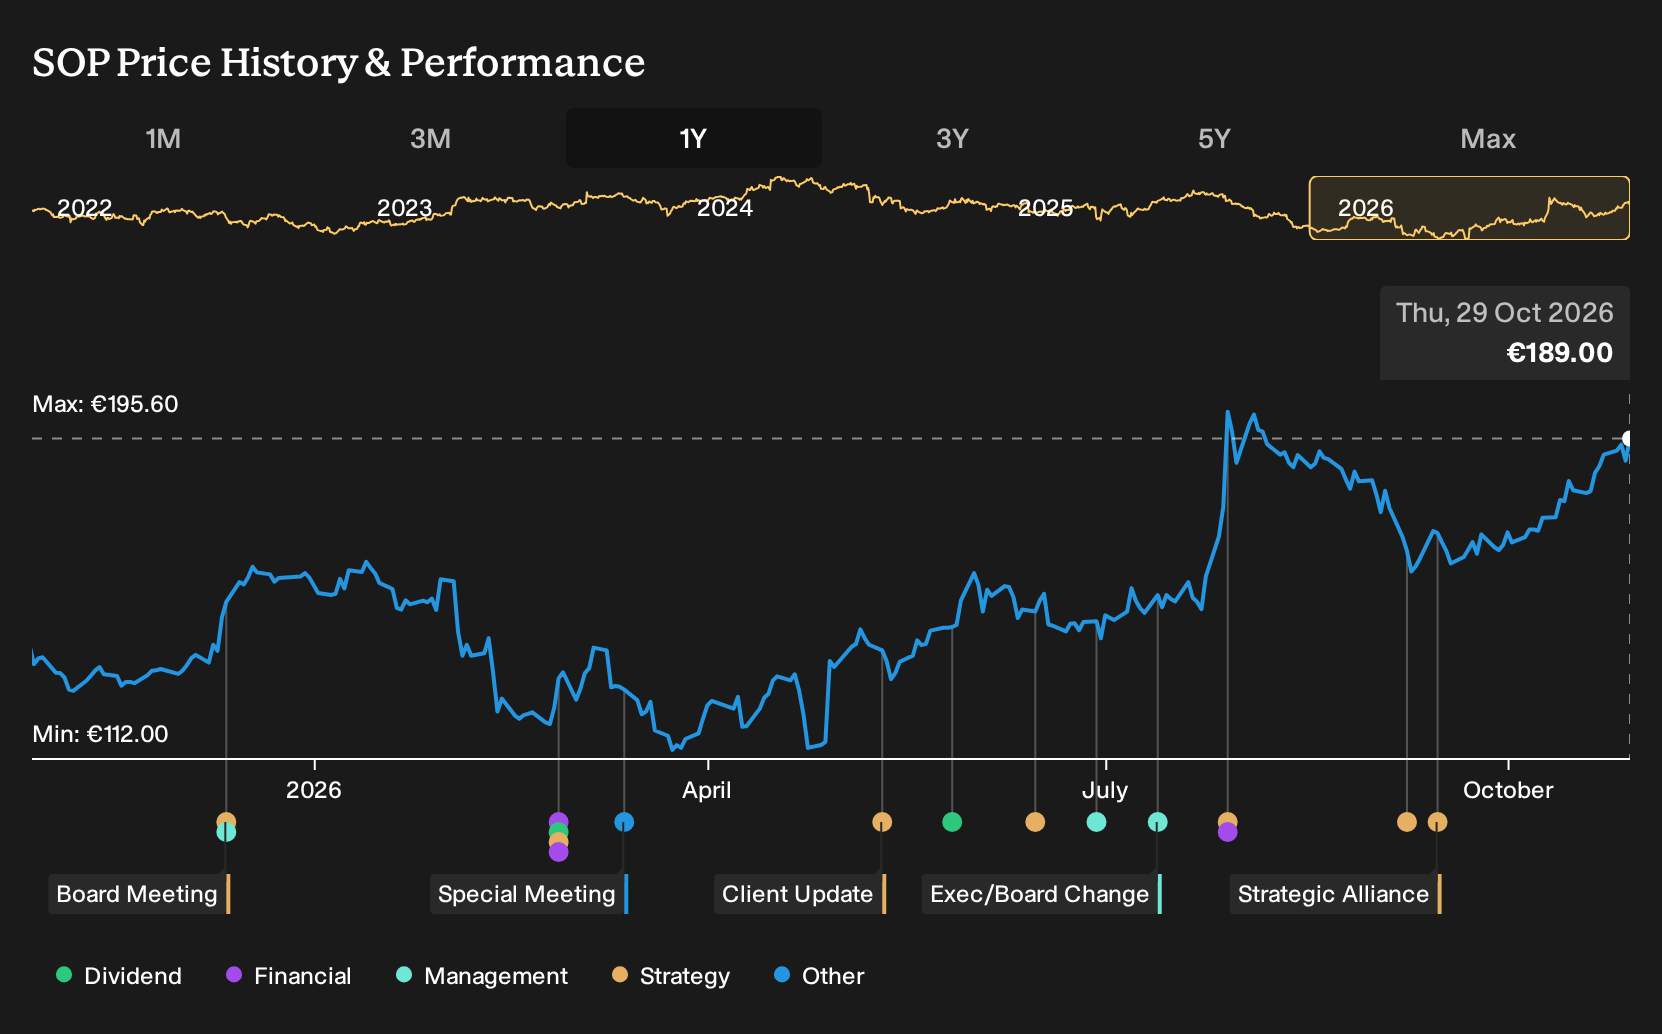
- Sopra Steria Group reported consolidated Q3 2026 revenue of €1,420.1 million and nine-month revenue of €4,379.0 million, both above the prior-year levels.
- The raised full-year organic revenue growth target to a 2.5% to 3.0% range, together with the Digital Product Simulation acquisition, points to management leaning into higher value digital engineering and regulated sector work.
- We will now look at how Sopra Steria Group's investment narrative is shaped by the higher full-year organic growth target.
Scan how Sopra Steria Group’s focus on regulated tech work compares with other potential opportunities by reviewing curated 224 resilient stocks with low risk scores that pair resilient balance sheets with steady business models.
Sopra Steria Group Investment Narrative Recap
To be a shareholder in Sopra Steria Group, you need to believe the business can keep turning its mix of consulting, software and regulated sector contracts into steady, compounding earnings. The raised 2.5% to 3.0% organic revenue target supports that view in the near term, since it points to healthy demand in Defence, Security & Space, aeronautics, cybersecurity and consulting.
The key short term catalyst is continued traction in these higher value activities and the early benefits from AI driven services and productivity tools. The biggest risk is that organic revenue in core European markets or UK transformation work slows again, while wage inflation or higher taxes eat into margins, which this update does not remove.
Among the recent announcements, the completion of the Digital Product Simulation acquisition ties most directly into this trading update. It expands Sopra Steria Group’s product lifecycle management and digital engineering capabilities, which aligns with stronger activity in aerospace and regulated sectors reported in Q3 2026.
For you as an investor, that matters because it can reinforce two existing catalysts. First, a richer offering for aerospace and space clients can support project flow in areas already contributing to revenue momentum. Second, deeper engineering expertise can help execution on complex contracts, which is important if rising staff costs or restructuring elsewhere begin to pressure profitability.
Sopra Steria Group’s narrative links analyst expectations of €6.5b in revenue and €396.4m in earnings by 2029 to an assumed 4.0% yearly revenue growth rate and an earnings increase of about €95m from current earnings of €301.1m.
Discover why Sopra Steria Group's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into AI rollout as the key catalyst for Sopra Steria Group. Before this Q3 update, they were already pencilling in revenue of about €6.6b and earnings near €418.9m by 2029. You can read this as a much more upbeat story that might shift again once the new numbers settle in.
Explore 2 other Sopra Steria Group fair value estimates, including one that suggests there could be as much as 22% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Sopra Steria Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sopra Steria Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sopra Steria Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sopra Steria Group?
If Sopra Steria Group has sharpened your focus on quality and resilience, you can use that same lens to scan other opportunities with the Simply Wall St Screener and compare different types of businesses side by side.
- For investors who want quality at a sensible entry point, start with a curated line up of 197 high quality undervalued stocks that combine stronger fundamentals with appealing prices.
- If income is your priority, you can check companies offering cash returns through 223 dividend fortresses that may suit a long term dividend approach.
- For those who care most about financial resilience, you can concentrate on balance sheet strength by reviewing a list of solid balance sheet and fundamentals (203 results) that can help you focus on sturdier businesses first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com