


- Advanced Energy Industries recently received a Zacks Rank #1 rating after analysts raised earnings estimates, pointing to stronger expected profitability from its precision power solutions across data center, semiconductor, industrial, and medical customers.
- The earnings upgrade highlights how execution in higher power density and higher voltage platforms may be improving, which directly matters for how Advanced Energy Industries monetises its capacity investments and supports its gross margin ambitions.
- We will look at how Advanced Energy Industries' investment narrative is affected by the earnings estimate upgrade and improving business outlook.
Compare Advanced Energy Industries' earnings upgrade story with other potential opportunities in power and automation by scanning our hand picked 95 robotics and automation stocks.
Advanced Energy Industries Investment Narrative Recap
To own Advanced Energy Industries, you need to believe its precision power platforms in AI data centers, semiconductors, and high end Industrial and Medical gear can keep winning slots in customer roadmaps. The short term hinge is execution on those ramps, especially as the firm leans into higher power density and 800 V architectures that support its gross margin goals.
The Zacks Rank upgrade tied to higher earnings estimates signals confidence that current orders and utilization of new capacity are tracking well, but it does not remove key risks. Heavy CapEx, rising inventories, and the 0% convertible notes mean underused factories or slower bookings could pressure returns, dilution, and valuation multiples.
The Zacks Rank #1 call is the clearest recent data point linking operating progress at Advanced Energy Industries to near term earnings potential. That reassessment rests on forecast profit growth, improving net margins, and the idea that new power platforms in AI data centers and advanced semiconductors can support stronger monetisation of existing capacity.
For you, the useful lens is simple. If AI data center programs, sub 2 nm plasma power platforms, and new Industrial and Medical design wins convert into sustained orders, then the current earnings upgrade story has an operational backbone. If demand softens or capacity sits idle, the same fixed investment and convertible financing could amplify downside risk to profitability and per share economics.
Advanced Energy Industries' current narrative is built on analysts expecting revenue of US$4.0b and earnings of US$895.2m by 2029, from earnings of US$220.7m today. This works out to 25.7% yearly top line growth and roughly a 4x earnings increase from the current profit base.
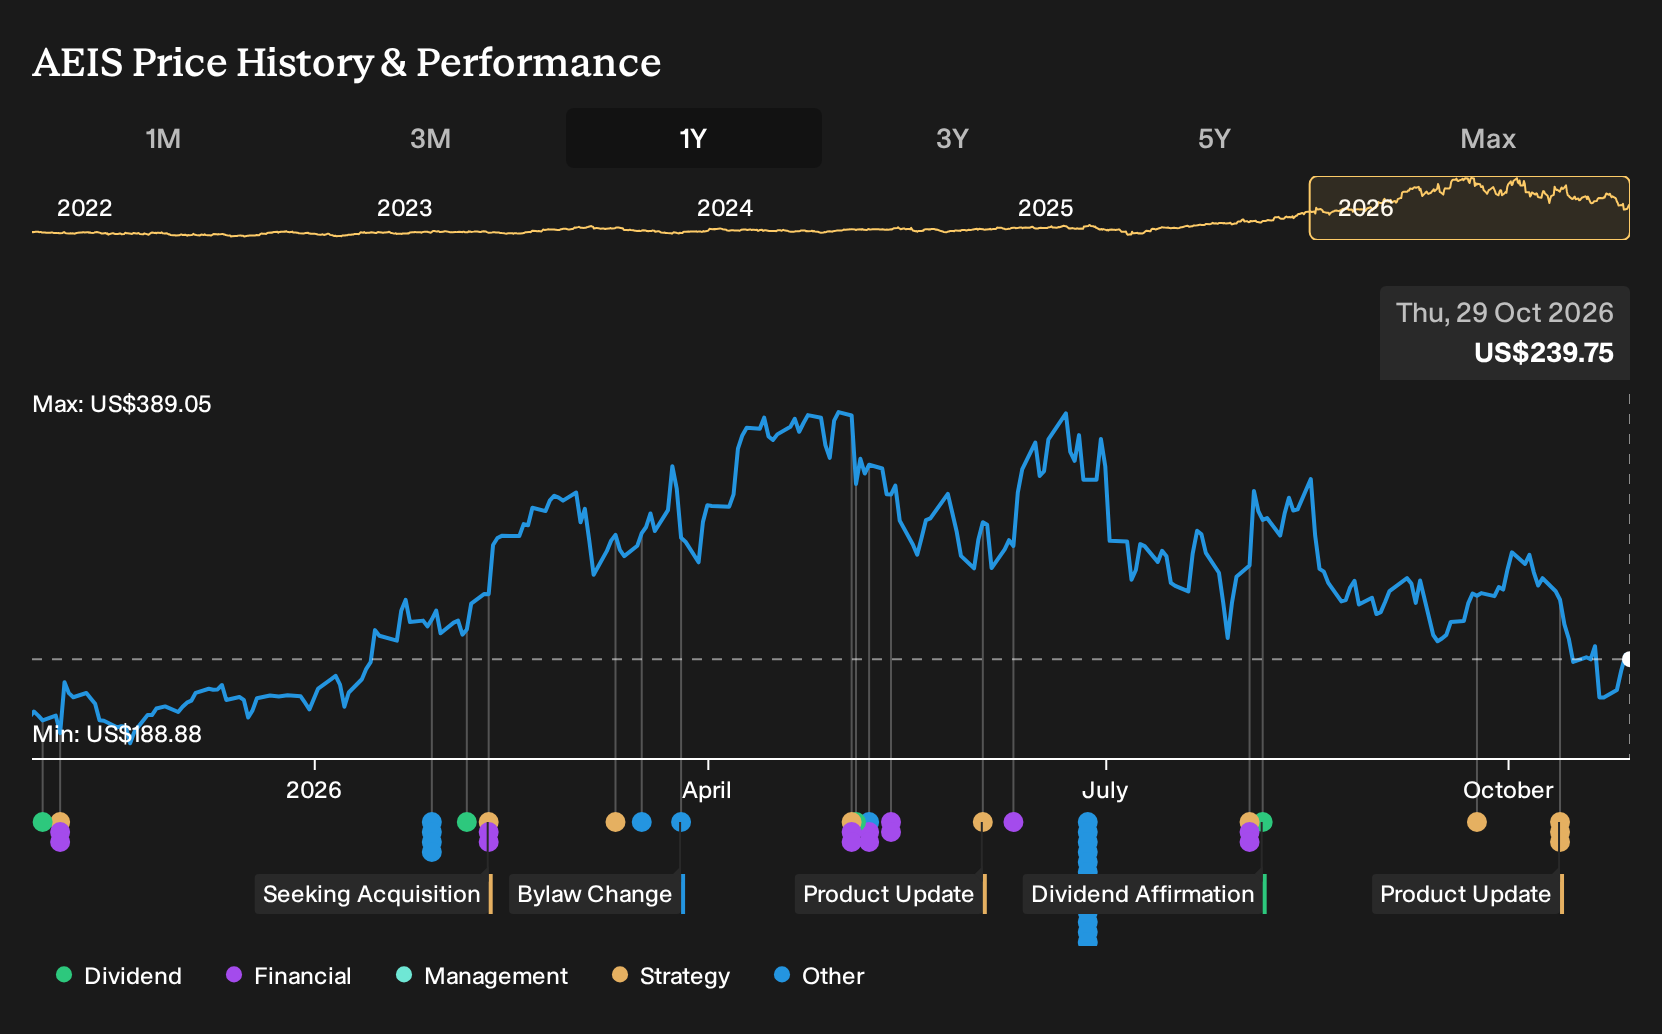
Uncover why Advanced Energy Industries' fair value indicates a potential 75% upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative angle on Advanced Energy Industries focuses on valuation risk rather than growth potential. The most cautious analysts were already working off roughly US$3.9b in revenue and about US$904.3m in earnings by 2029, yet still landed on a lower US$360.0 target. That more pessimistic view shows how sharply opinions can differ, and why it can be useful to compare several pre-upgrade narratives that may now evolve as fresh information filters in.
Explore 4 other Advanced Energy Industries fair value estimates, including one that suggests it could be worth just $360.00!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Advanced Energy Industries research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Advanced Energy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advanced Energy Industries' overall financial health at a glance.
Looking for more investment ideas beyond Advanced Energy Industries?
Once you have a view on Advanced Energy Industries, it can help to line that thesis up against a few very different types of opportunities so you can see what really deserves a spot in your portfolio.
- If you want potential upside with strict quality filters around balance sheets and fundamentals, scan our list of solid balance sheet and fundamentals (23 results) to find businesses that might better match your risk tolerance.
- For investors hunting for mispriced opportunities with strong underlying metrics, compare your Advanced Energy Industries thesis against our carefully curated 18 high quality undiscovered gems to see what else catches your eye.
- If capital preservation comes first and you prefer companies with historically lower risk characteristics, broaden your watchlist using our 30 resilient stocks with low risk scores and weigh those options against Advanced Energy Industries.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com