


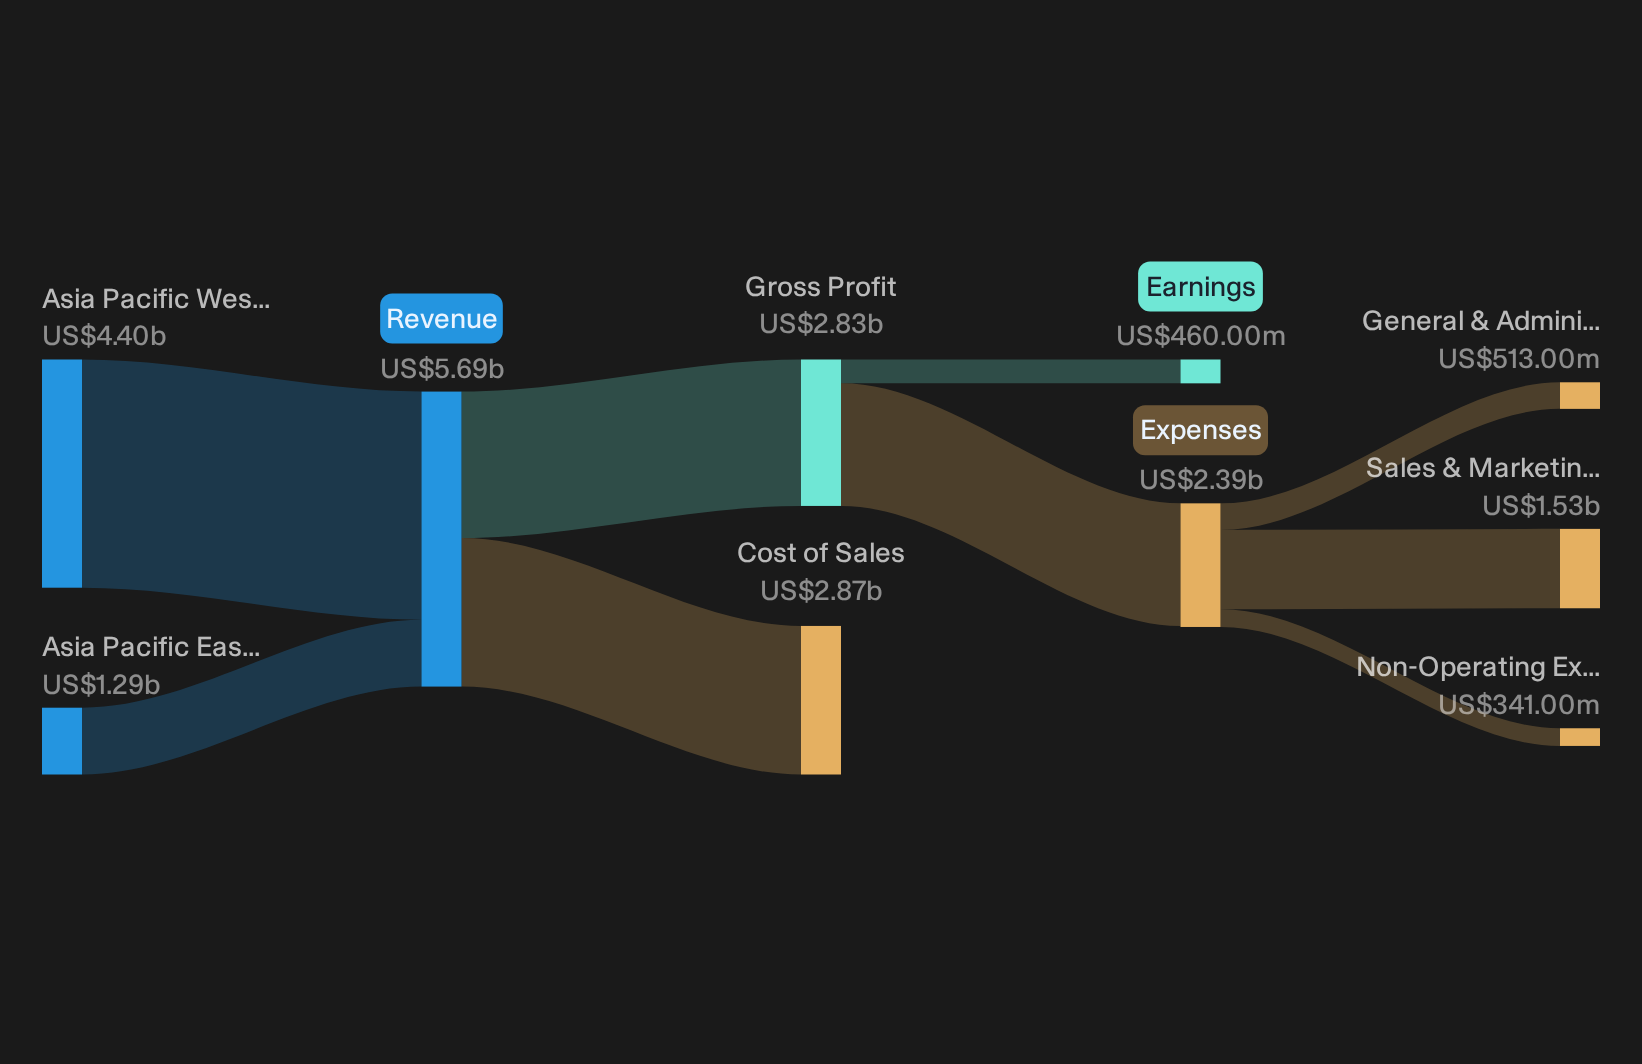
Budweiser Brewing Company APAC just released its Q3 2026 numbers and the verdict from the screen was blunt. The share price closed at HK$5.89, capping a roughly 10% slide over the past three months, even as the brewer posted US$1,449 million in quarterly revenue.
What really jarred sentiment was profit compression. Net income for the quarter came in at US$92 million and basic earnings per share landed at US$0.006953, far below recent quarters. Traders focused on that squeeze and continued to sell, while the full earnings picture is more complicated than a simple bad quarter headline.
Like the brand strength and scale of Budweiser Brewing Company APAC but worried about profit compression and thin earnings per share this quarter? Filter for brewers and consumer stocks with sturdier profitability using our list of solid balance sheet and fundamentals stocks (203 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$1,449 million vs. US$1,555 million (declined 6.8%)
- Net Income (Q3 2026 vs Q3 2025): US$92 million vs. US$185 million (fell 50.3%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.006953 vs. US$0.014004 (decreased 50.4%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 8.1% vs. 9.9% (compressed 1.8 percentage points)
Ask Charlie what explains Budweiser Brewing APAC’s cheap price and high P/E.
Premium Growth Story Hits a Speed Bump
The bullish story says Budweiser Brewing Company APAC can lean on mix and premium brands to raise earnings power even if volumes stay soft.
"Analysts expect Budweiser Brewing Company APAC to keep leaning on premium and super premium brands, in-home and O2O channels, and growth in India and South Korea, in order to improve its overall mix and earnings power over time."
Q3 tells a tougher story. Group revenue declined 6.8% year on year while net income fell 50.3% and basic EPS dropped a similar 50.4%. That scale of profit compression suggests stronger India and South Korea, plus premiumisation and O2O in China, are not yet offsetting pressure elsewhere.
China Drag And Cost Risks Show Through
The bear case focuses on China staying a drag and rising costs eroding the benefit of premiumisation.
"If normalized EBITDA in China continues to contract as management prioritizes brand and route to market investment despite weaker top line trends, the company could see a more prolonged drag from its largest market."
Q3 numbers fit that concern. Revenue fell 6.8% and trailing 12 month net margin compressed from 9.9% to 8.1%. With net income halved while India and South Korea are described as outperforming, the figures point to ongoing profitability strain that likely still ties back to China and input cost pressure.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Hunt For Mispriced Earnings Power
Budweiser Brewing Company APAC showed how a weaker quarter can swiftly reshape expectations across the market. The real opportunity is hunting for stocks that may be undervalued before pricing better reflects their earnings power.
- Company 1 - 17% below our estimate - targets larger healthcare managed services contracts that incorporate AI tools into claims handling and care management.
- Company 2 - 25% below our estimate - supplies test systems buyers lock in as AI server and photonics orders span multiple production lines.
- Company 3 - 15% below our estimate - ramps complex injectable and biosimilar production capacity after building integrated ingredients and contract manufacturing facilities.
Those are three of them. See all 197 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com