


China Petroleum & Chemical just posted its Q3 2026 scorecard and the headline is simple: profit outpaced price. Basic earnings per share landed at 0.113 CNY while net income from ongoing operations reached CNY 13,600m, yet the stock closed around HK$4.87 after only a modest short term climb over the past month.
The strongest story here is earnings power. Quarterly profit stepped up sharply from Q2, and trailing 12 month earnings from continuing operations reached CNY 47,014m. The market reaction looks cautious compared with that improvement, which presents a clear sentiment check for investors watching China Petroleum & Chemical.
Like the profit story at China Petroleum & Chemical but not convinced the share price is reflecting it yet? Benchmark this setup against our 197 high quality undervalued stocks.
Q3 2026 Earnings Summary
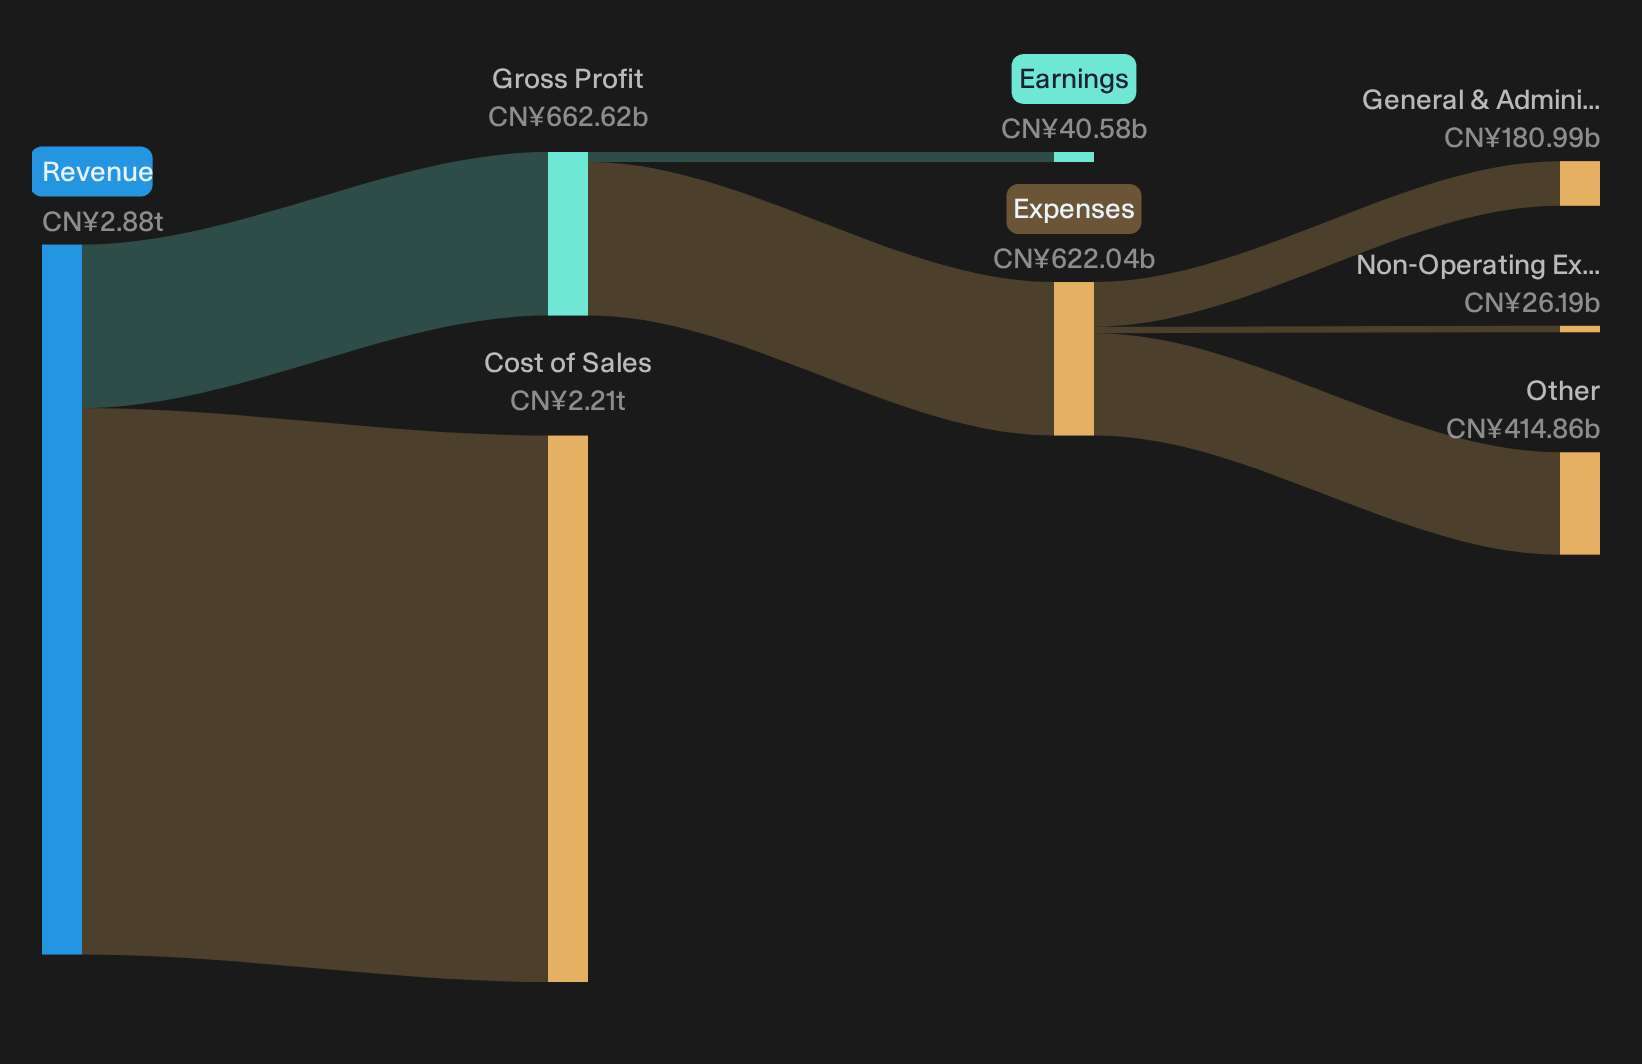
- Revenue (Q3 2026 vs. Q3 2025): CNY 769,735m vs. CNY 704,389m (up about 9.3%)
- Net Income from Ongoing Operations (Q3 2026 vs. Q3 2025): CNY 13,600m vs. CNY 8,313m (up about 63.6%)
- Basic EPS (Q3 2026 vs. Q3 2025): CNY 0.113 vs. CNY 0.069 (up about 63.8%)
- Trailing 12M Earnings from Continuing Operations (Q3 2026 vs. Q4 2025 TTM): CNY 47,014m vs. CNY 35,810m (up about 31.3%)
Tired of squinting at dense tables and raw figures? See China Petroleum & Chemical's valuation laid out in clean, visual charts inside the company report for China Petroleum & Chemical.
China Petroleum & Chemical’s Transition Story Put To The Test
"The main thing that has to go right is that China Petroleum & Chemical successfully shifts away from structurally weaker road fuel demand toward low carbon energy, aviation fuel and higher value petrochemicals while keeping refining and feedstock costs under control."
China Petroleum & Chemical is hitting early waypoints on that shift. Q3 profit from ongoing operations and basic EPS both moved ahead much faster than revenue, which points to mix and cost discipline helping, not just volume. Aviation fuel integration, 16 new sustainable aviation fuel projects and the enlarged high end PVA base are all now live growth vectors, while broader crude sourcing, including Russian ESPO, supports the claim that feedstock costs are being actively managed.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Bear Case Check: Refining Strain vs Q3 Profit Rebound
Bearish analysts argue that China Petroleum & Chemical is on the verge of structurally weaker refining economics as transport fuel demand erodes faster than new ventures can fill the gap.
"Although China Petroleum & Chemical is expanding into new energy and chemicals, the company now expects China’s overall oil demand to have peaked in 2025, with an 8.9% drop projected for 2026. This can force deeper cuts to refining throughput and weigh on revenue and utilization driven earnings beyond what many models assume."
Q3 tells a tighter story. Revenue reached CNY 769,735m and net income from ongoing operations was CNY 13,600m, both up strongly year on year, and earnings grew faster than sales. That points to better mix and cost control, not yet the throughput squeeze that the bearish scenario anticipates. However, management’s own demand forecasts keep that risk very much alive beyond this quarter.
Hunt Quiet Disconnections In Plain Sight
China Petroleum & Chemical recently reported stronger profits while its share price stayed subdued. The real opportunity lies in finding stocks that could be undervalued before any valuation gap narrows.
- Company 1 - 43% below our estimate - uses a growing backlog of large LED projects to expand higher margin software and services across sports, commercial and transport clients.
- Company 2 - 44% below our estimate - turns a completed capacity build out and utilization program into richer aluminum product mixes for autos, HVAC and electrification customers.
- Company 3 - 21% below our estimate - deepens cross category adoption as food customers add grocery and retail orders, lifting order frequency and spreading delivery infrastructure over more transactions.
Those are three of them. See the full list of 197 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com