


- Centrus Energy has shipped the first new centrifuge from its Oak Ridge, Tennessee plant, a key step in its multibillion dollar uranium enrichment expansion, with units now moving to Ohio for final assembly through a fully domestic supply chain.
- The completed centrifuge confirms that Centrus Energy’s high rate manufacturing reboot in Oak Ridge is translating into physical equipment, which matters for meeting future LEU, HALEU, and national security enrichment commitments using an unobligated US supply chain.
- We will examine how Centrus Energy’s investment narrative is affected as it turns its Oak Ridge rebuild into a working centrifuge line.
Scan other nuclear fuel plays on the move with our curated list of 16 nuclear energy infrastructure stocks as governments focus on domestic enrichment capacity and grid reliability.
Centrus Energy Investment Narrative Recap
To own Centrus Energy, you need to believe the uranium enrichment build out converts its US$4.5b backlog and HALEU contracts into durable cash flow despite heavy upfront spending. The first Oak Ridge centrifuge shipment shows the manufacturing restart is producing real hardware, which supports that capacity story but does not materially change it.
In the near term, the key catalyst is still execution on the enrichment expansion and the US$900 million HALEU task order, including cost control after margins compressed and LEU costs climbed. The biggest risk remains the mismatch between high capital spend and the timing of future contracts, which could pressure free cash flow and increase dilution risk.
The recent completion and shipment of the first new centrifuge connects directly to Centrus Energy’s January 2026 plan to invest US$560 million into converting Oak Ridge into a high rate manufacturing hub. That capital program underpins expectations for thousands of centrifuges and new Ohio capacity coming online in 2029.
For you as a shareholder, the Oak Ridge expansion and fully domestic supply chain are now partly proven in practice instead of only on paper. The operational question from here is whether Centrus can keep scaling throughput, integrate Westerman Holdings smoothly, and hold costs in check so that future LEU and HALEU volumes translate into healthier margins rather than just bigger projects.
Centrus Energy's current analyst narrative points to forecast revenues of US$478.8 million and earnings of US$46.4 million by 2029, with revenue expected to remain fairly flat and earnings projected to fall by US$2.1 million from US$48.5 million today.
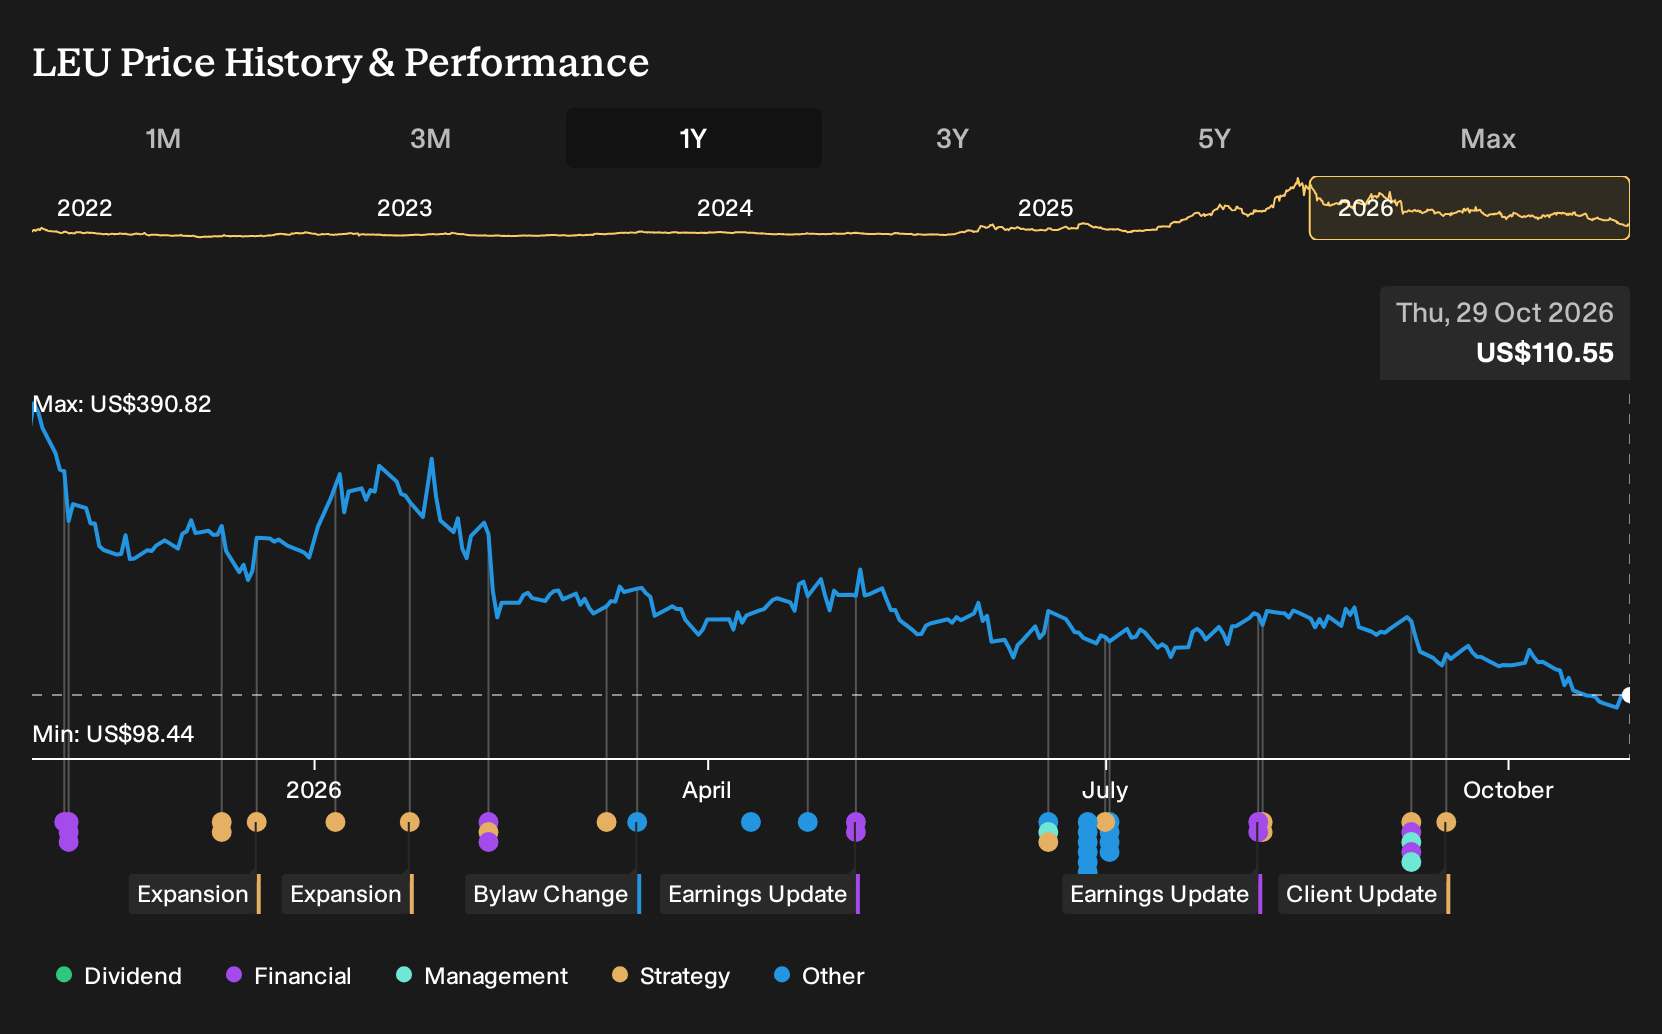
Uncover why Centrus Energy's fair value indicates a 104% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts latch onto operating leverage as the key catalyst. They were modeling Centrus Energy toward US$677.3 million in revenue and US$107.7 million in earnings by 2029, far above consensus. Those views came before this centrifuge milestone, so opinions and models may shift as new information lands.
Explore 5 other Centrus Energy fair value estimates, including one that suggests there could be as much as 452% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own well-researched perspective.
- A great starting point for your Centrus Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Centrus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Centrus Energy's overall financial profile at a glance.
Looking For More Ideas Beyond Centrus Energy?
If you want to pressure test your thesis on Centrus Energy or simply widen your opportunity set, it helps to compare it with other stocks that share similar strengths in different areas of the market. The Simply Wall St Screener can surface candidates that match the quality, balance sheet, or risk profile you care about most.
- For investors who care most about resilient balance sheets and fundamental strength, start with this curated list of solid balance sheet and fundamentals (23 results) that filters for sturdier financial profiles.
- If your priority is uncovering mispriced quality, use our screen of 18 high quality undiscovered gems to see companies that combine fundamentals with relatively low market attention.
- When capital preservation and smoother volatility matter to you, focus on a 30 resilient stocks with low risk scores that highlights businesses with more resilient risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com