


As the Canadian market navigates a landscape marked by fluctuating indices and evolving economic indicators, small-cap stocks are capturing attention for their potential to deliver unique growth opportunities. In this environment, identifying promising companies often involves looking beyond the surface to find those with robust fundamentals and strategic positioning that align well with current market dynamics.
Top 10 Undiscovered Gems With Strong Fundamentals In Canada
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Wesdome Gold Mines | NA | 34.13% | 46.06% | ★★★★★★ |
| Torex Gold Resources | NA | 12.76% | 20.04% | ★★★★★★ |
| Thor Explorations | NA | 38.45% | 61.95% | ★★★★★★ |
| Alvopetro Energy | 18.59% | 7.72% | 6.43% | ★★★★★☆ |
| Eldorado Gold | 28.50% | 19.96% | 57.45% | ★★★★☆☆ |
| Aris Mining | 28.26% | 24.20% | 5.42% | ★★★★☆☆ |
| Hydreight Technologies | 22.28% | 71.66% | 59.41% | ★★★★☆☆ |
| Kolibri Global Energy | 20.09% | 25.10% | -21.44% | ★★★★☆☆ |
| Rio2 | 22.38% | 105.97% | 53.08% | ★★★☆☆☆ |
| Journey Energy | 11.76% | 6.14% | -39.79% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
China Gold International Resources (TSX:CGG)
Simply Wall St Value Rating: ★★★★★★
Overview: China Gold International Resources Corp. Ltd. is a mining company engaged in the acquisition, exploration, development, and mining of gold and base metal resources in China and Canada, with a market capitalization of CA$13.30 billion.
Operations: China Gold International Resources generates revenue primarily from mine-produced copper concentrate ($1.24 billion) and gold ($399.26 million). The company's revenue model is heavily reliant on these two segments, with copper concentrate being the dominant contributor.
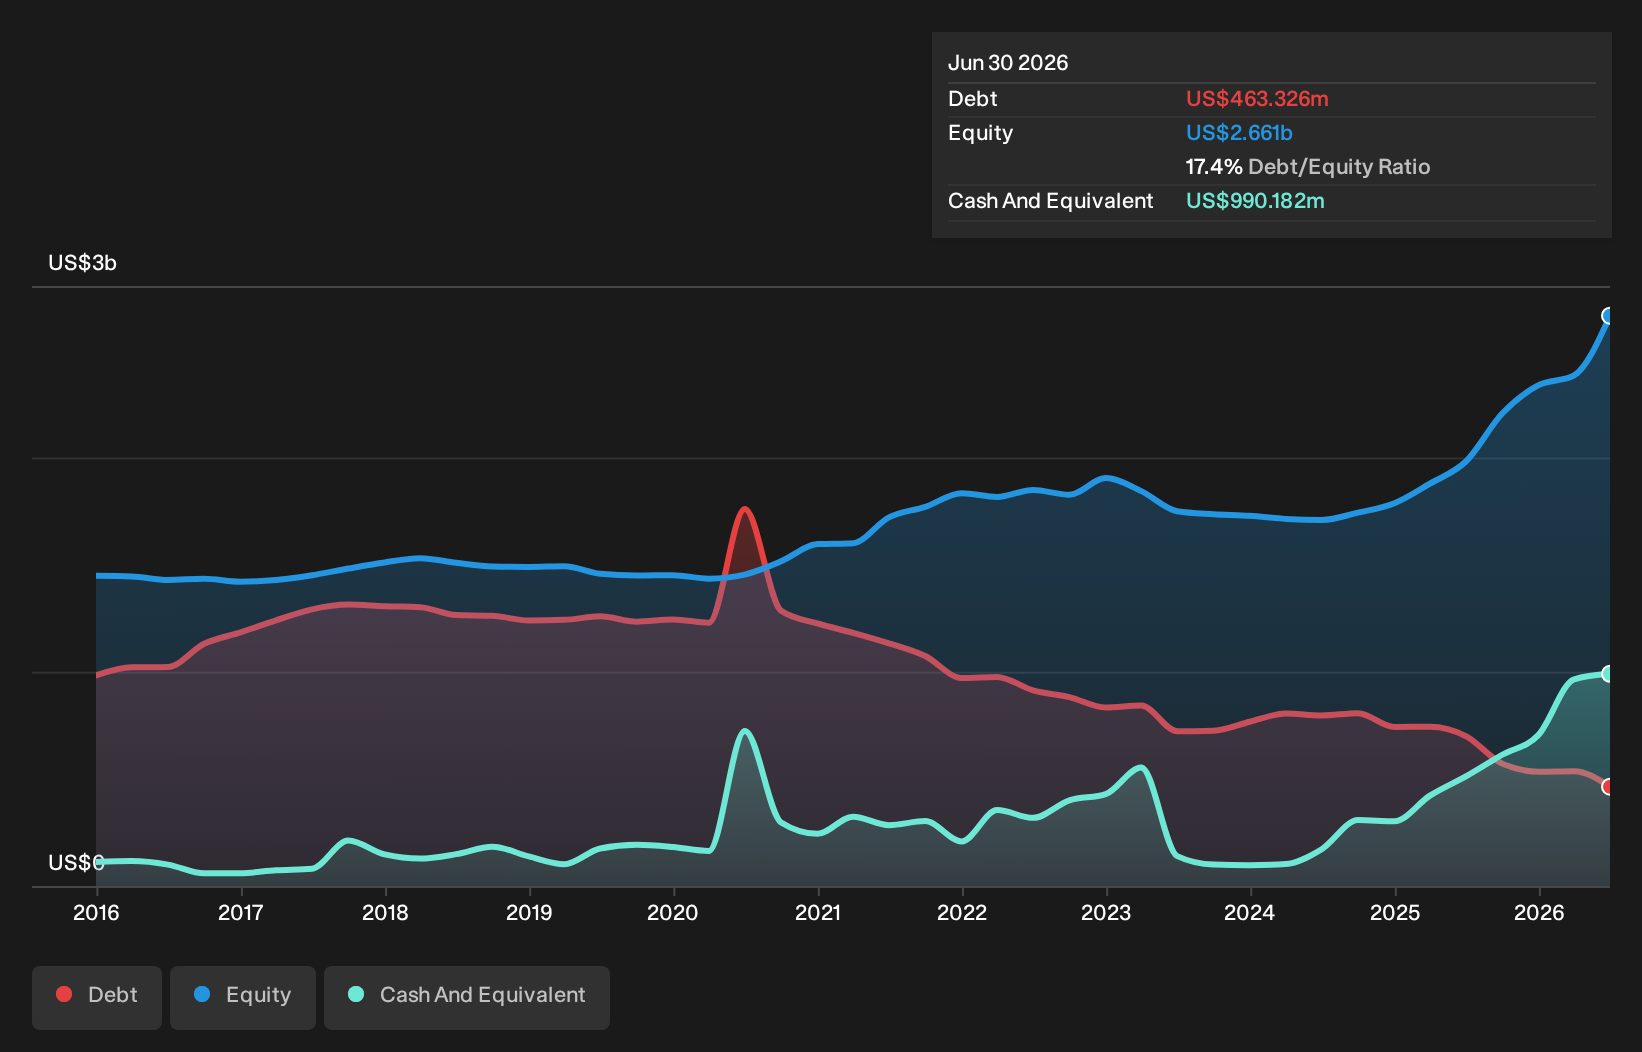
China Gold International Resources, a dynamic player in the mining sector, has shown impressive earnings growth of 162.6% over the past year, outpacing its industry peers. With a debt-to-equity ratio reduced from 65.8% to 17.4% over five years, the company demonstrates financial prudence and stability. Its interest payments are well-covered by EBIT at an impressive 275 times coverage, highlighting robust operational efficiency. Despite recent production challenges due to slope instability at the CSH Mine, which led to a temporary suspension of operations, remediation plans are underway with estimated capital expenditures of approximately RMB 98 million to ensure safety and continuity in operations.
Eldorado Gold (TSX:ELD)
Simply Wall St Value Rating: ★★★★☆☆
Overview: Eldorado Gold Corporation, along with its subsidiaries, focuses on the mining, exploration, development, and sale of mineral products mainly in Turkey, Canada, and Greece with a market capitalization of CA$12.58 billion.
Operations: Eldorado Gold generates revenue through the mining and sale of mineral products in Turkey, Canada, and Greece. The company's financial performance is influenced by its ability to manage production costs and optimize operations across these regions.
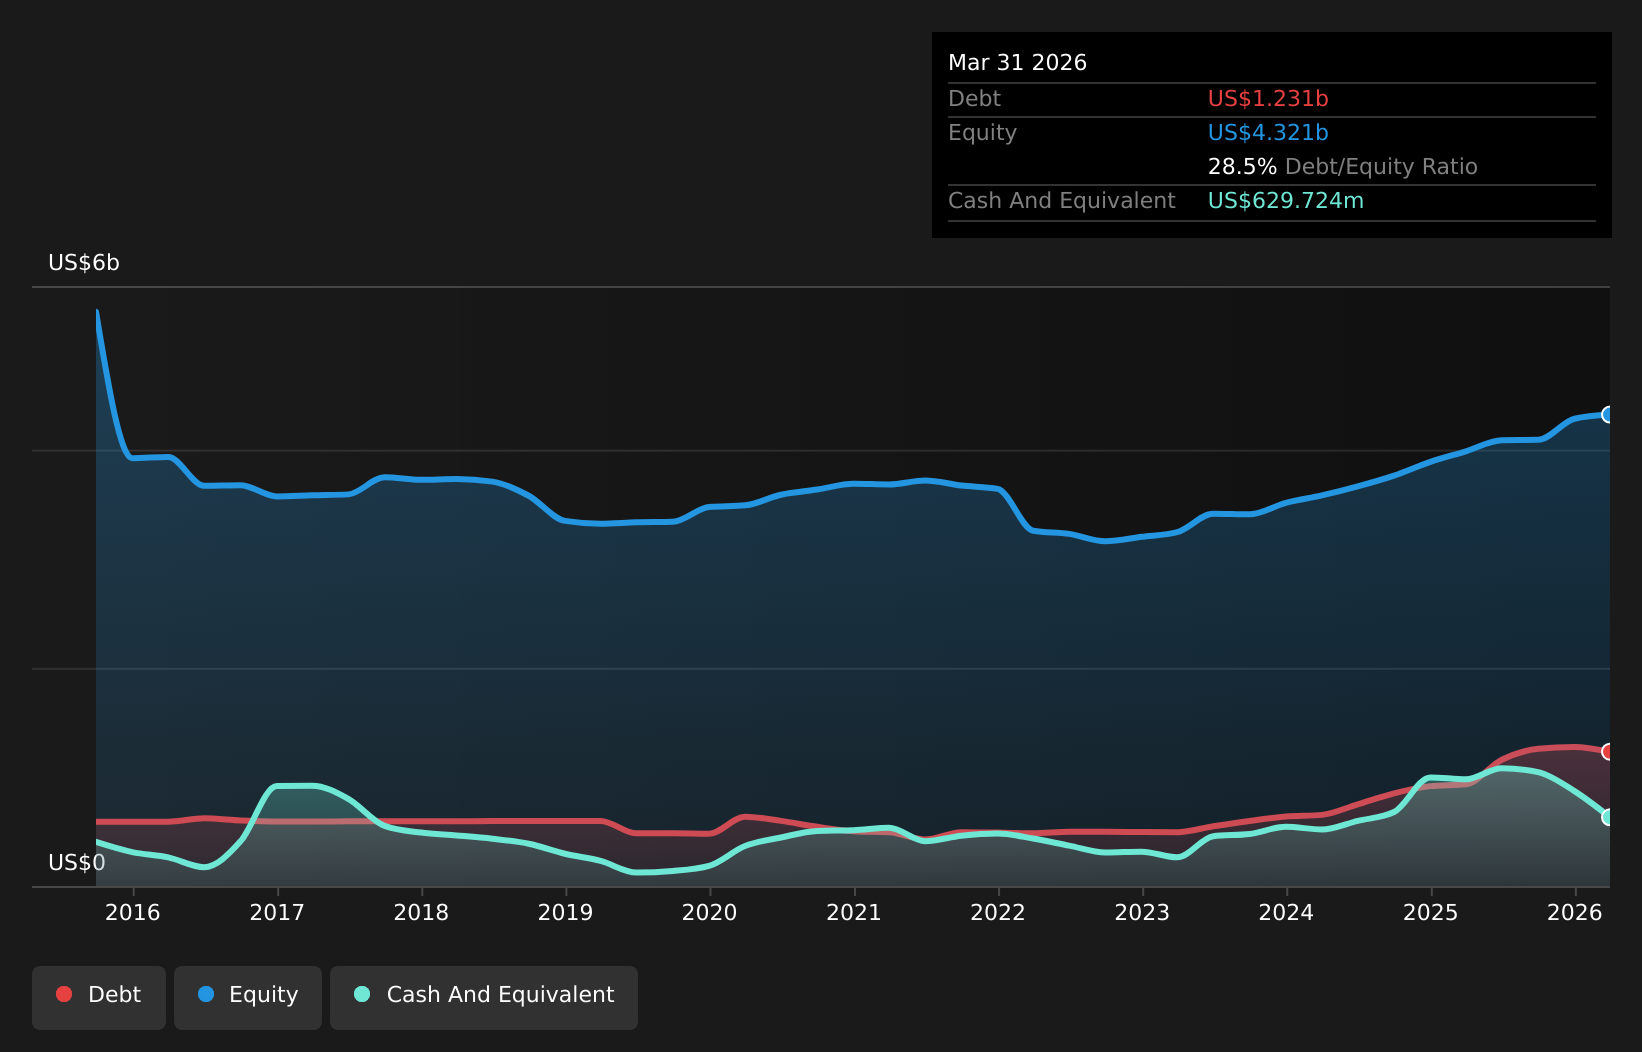
Eldorado Gold, a notable player in the mining industry, has shown significant earnings growth, with net income reaching US$117.95 million for Q3 2026 compared to US$56.03 million the previous year. The company's net debt to equity ratio stands at a satisfactory 22.8%, and its interest payments are well covered by EBIT at 25.5 times coverage, indicating strong financial health. Despite challenges like cost inflation and operational issues at certain mines, Eldorado's strategic focus on ramping up new copper-gold projects could enhance production efficiency and margins significantly in the future, supporting its undervaluation narrative among market analysts.
Rio2 (TSX:RIO)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Rio2 Limited focuses on the exploration, development, and mining of mineral properties across Canada, Peru, Bahamas, and Chile with a market cap of CA$1.53 billion.
Operations: Rio2 Limited, with a market cap of CA$1.53 billion, does not currently report any revenue segments in its financial disclosures.
With a debt to equity ratio climbing from 0% to 22.4% over the past five years, Rio2's balance sheet reflects a manageable net debt to equity ratio of 9.5%, deemed satisfactory. The company's interest payments are comfortably covered by EBIT at a multiple of 10.5x, indicating solid financial health despite shareholder dilution last year. Recent exploration updates highlight ambitious drilling programs across its mining projects in Peru and Chile, while regulatory approvals for environmental impact modifications pave the way for operational expansion at its Condestable mine in Peru. Earnings have surged dramatically by 4776%, with net income reaching US$46 million in Q2 2026 compared to a loss last year, showcasing robust growth potential within the metals and mining sector.
- Click to explore a detailed breakdown of our findings in Rio2's health report.
Explore historical data to track Rio2's performance over time in our Past section.

Where To Now?
- Take a closer look at our TSX Undiscovered Gems With Strong Fundamentals list of 14 companies by clicking here.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com