


Solaris Energy Infrastructure has been a powerful performer in recent years, and the recent share price strength now puts a spotlight on whether the current valuation is still supported by its earnings. With so much optimism already reflected in the chart, investors are starting to ask if Solaris Energy Infrastructure's profit engine is strong enough to back up today's price.
- Over the past 5 years the stock has delivered roughly 9x its starting level by return, which raises the stakes on whether its earnings profile can keep justifying that kind of re-rating.
- Management's decision to lift spending on turbines and power equipment to about US$1.15b, taking investment above recent sales, can shape future profit margins and the timing of cash generation as those 2.3 gigawatts of contracted capacity come on line.
- Your read on Solaris Energy Infrastructure is one view; the desks covering it have another. See what analysts think Solaris Energy Infrastructure's shares could be worth.
The issue now is whether Solaris Energy Infrastructure's current share price fairly reflects what its earnings suggest investors are paying for.
If you want to test the same earnings question that hangs over Solaris Energy Infrastructure against a wider group of companies, take a look at solid balance sheet and fundamentals stocks screener (23 results).
Is Solaris Energy Infrastructure Getting Expensive on Earnings?
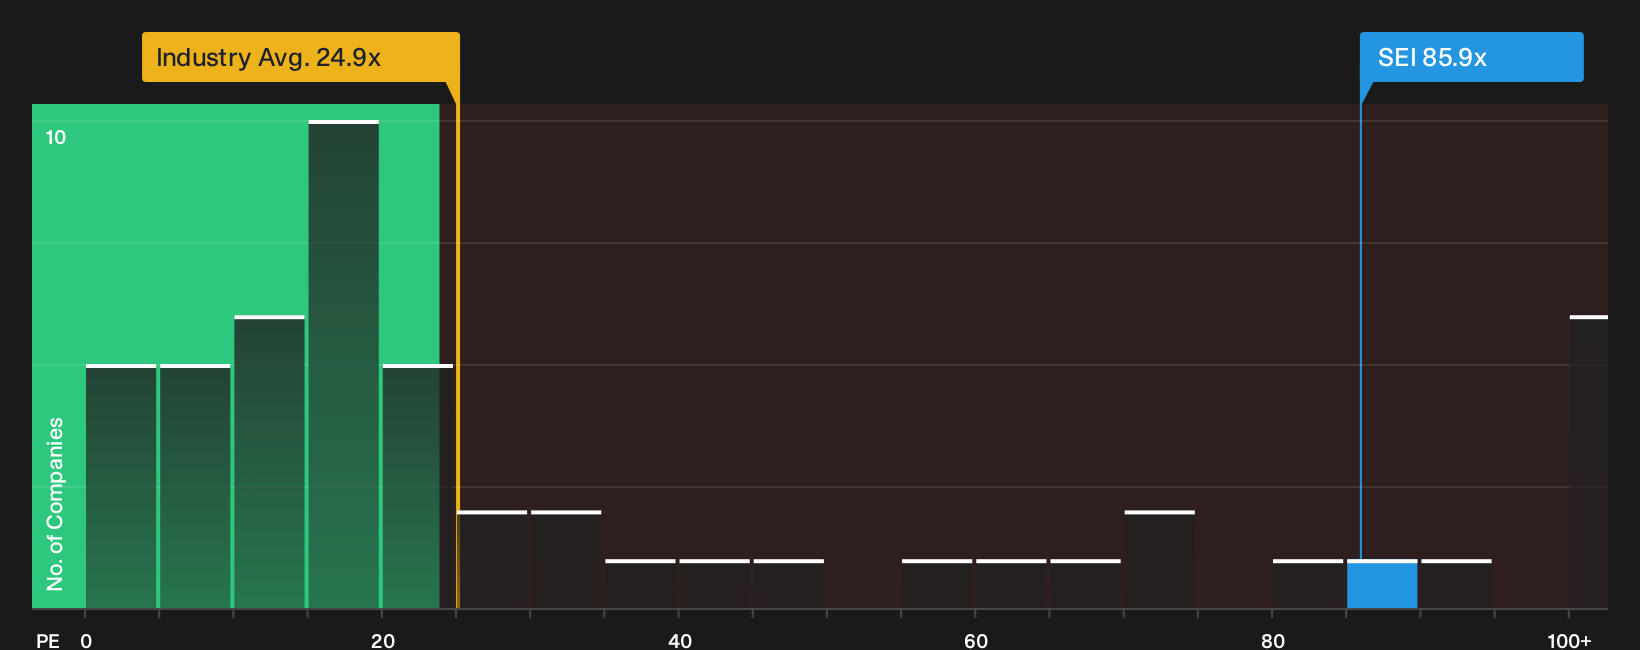
A P/E lens fits Solaris Energy Infrastructure because earnings remain the main anchor for how the market is weighing all that capital spending and future capacity. The stock trades on roughly 85.9x earnings, which is far above both the Energy Services industry average near 24.9x and the peer group around 30.5x. Even against a tailored fair multiple that looks at Solaris Energy Infrastructure's own growth, margins, size and risk profile, the current P/E still screens as overvalued. The model flags the gap more as a caution signal than a precise target level because losses and risk assumptions weigh heavily on that benchmark.
Because management has been pouring US$1.15b into turbines and equipment while talking up long term contracted megawatts, the market is effectively paying a premium today for profits that sit further out on the calendar. That kind of valuation leaves little room for disappointment if earnings or future free cash flow arrive more slowly than hoped, so any position here leans heavily on confidence that the current P/E can be earned into over time. Explore the numbers behind Solaris Energy Infrastructure's P/E valuation.
The Solaris Energy Infrastructure Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Solaris Energy Infrastructure's valuation puzzle leaves off and spell out the specific earnings, margin and growth paths that would need to hold for the stock to look materially richer or cheaper than today's price. Instead of stopping at a single P/E or model output, they unpack the future that number implies so you can track over time whether Solaris Energy Infrastructure's actual progress lines up with the story behind the valuation, and they live on Simply Wall St's Community page.
One of the top community narratives on Solaris Energy Infrastructure: 32% undervalued
"Expanding behind the meter power demand from data centers and large energy users, supported by Solaris Energy Infrastructure contracts covering over 2 gigawatts..."
Discover why this Narrative puts Solaris Energy Infrastructure at 32% undervalued.
Solaris Energy Infrastructure’s price is only one piece of the decision
Before you treat Solaris Energy Infrastructure as just a set of earnings multiples and capital projects, it is worth asking who is steering the ship, how their pay is structured, and whether those incentives really line up with your interests. See who runs Solaris Energy Infrastructure and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com