


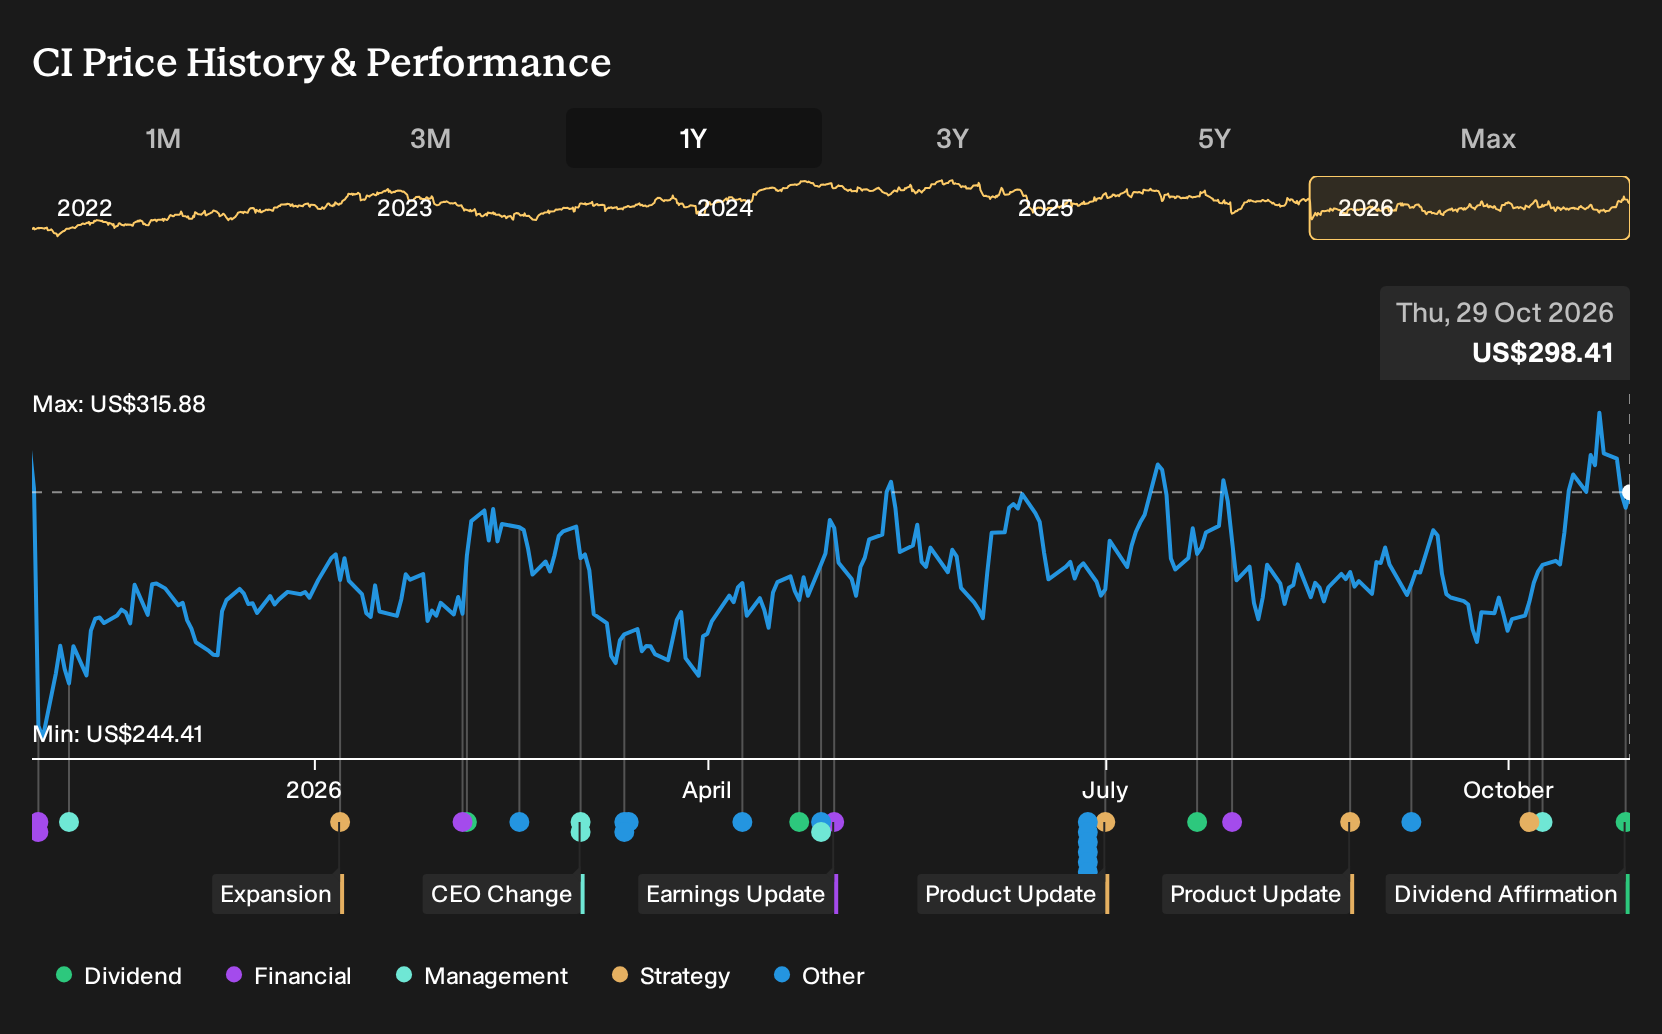
- The Cigna Group's board approved a quarterly cash dividend of $1.56 per share, payable on 17 December 2026 to shareholders recorded on 3 December 2026, and the firm is expected to report higher revenue but lower earnings year over year for the September 2026 quarter.
- The mix of a routine dividend and a projected earnings decline highlights pressure on profitability, even as Cigna Group's revenue base expands.
- This context raises questions about how Cigna Group's investment narrative is affected by the projected earnings decline alongside resilient revenue and the confirmed dividend.
Compare Cigna Group's mix of resilient revenue and earnings pressure with other companies facing similar trade offs by scanning our hand picked list of 30 resilient stocks with low risk scores.
Cigna Group Investment Narrative Recap
Cigna Group may be most appealing if you believe its Evernorth Health Services and Cigna Healthcare operations can keep growing revenue while absorbing margin pressure from contract repricing, higher medical costs, and the ACA exchange exit. In the near term the focus remains on execution in Evernorth and on keeping commercial medical cost trends contained as affordability pressures stay elevated.
The expected earnings softness for the September 2026 quarter, alongside a higher top line, highlights profitability as the key short term swing factor. The dividend decision itself does not materially change the operating outlook or the core risk reward trade off tied to Evernorth margins and commercial cost trends.
The freshly affirmed US$1.56 per share quarterly dividend is the clearest new data point around Cigna Group today. For shareholders, it reinforces that management is comfortable returning cash while still funding heavy investment in the Signature platform, specialty pharmacy, and AI driven care programs that underpin the longer term earnings story.
This payout also sits alongside existing balance sheet considerations, including a high level of debt. As a result, execution in Evernorth and Cigna Healthcare matters even more. If margin pressure in Pharmacy Benefit Services or resistance to higher employer pricing worsens, that could make the dividend policy harder to sustain at the current level over time.
What The Analyst Scenario Implies For Cigna Group
Cigna Group's narrative projects US$324.7b revenue and US$7.8b earnings by 2029. This assumes 4.8% yearly revenue growth and an earnings increase of about US$1.4b from US$6.4b today.
Uncover why Cigna Group's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Cigna Group from 5 members of the Simply Wall St Community span from about US$318.90 to roughly US$937.27, so opinions are wide apart. Some see earnings pressure from Evernorth and affordability issues as a real brake. Others focus on specialty pharmacy growth and AI driven cost savings as potential offsets. Explore those viewpoints directly before deciding how this dividend story fits your own thesis.
Explore 4 other Cigna Group fair value estimates, including one that suggests it could be worth just $318.90.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cigna Group research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cigna Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cigna Group's overall financial health at a glance.
Looking For More Ideas Beyond Cigna Group?
Once you understand how Cigna Group fits your portfolio, it can help to compare it with a broader watchlist. Use the Simply Wall St Screener to find other companies with balance sheets, income streams, or dividends that match the kind of risk profile you prefer.
- If you want companies that combine financial resilience with lower risk scores, start by reviewing our 30 resilient stocks with low risk scores which might better match a cautious approach.
- If your focus is on income, consider stocks offering different yield levels or payout profiles by checking out the 7 dividend fortresses which could complement Cigna Group in a diversified income strategy.
- If you are looking for underfollowed opportunities with solid fundamentals, review the 18 high quality undiscovered gems which may align with a higher conviction, higher research-effort style.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com