


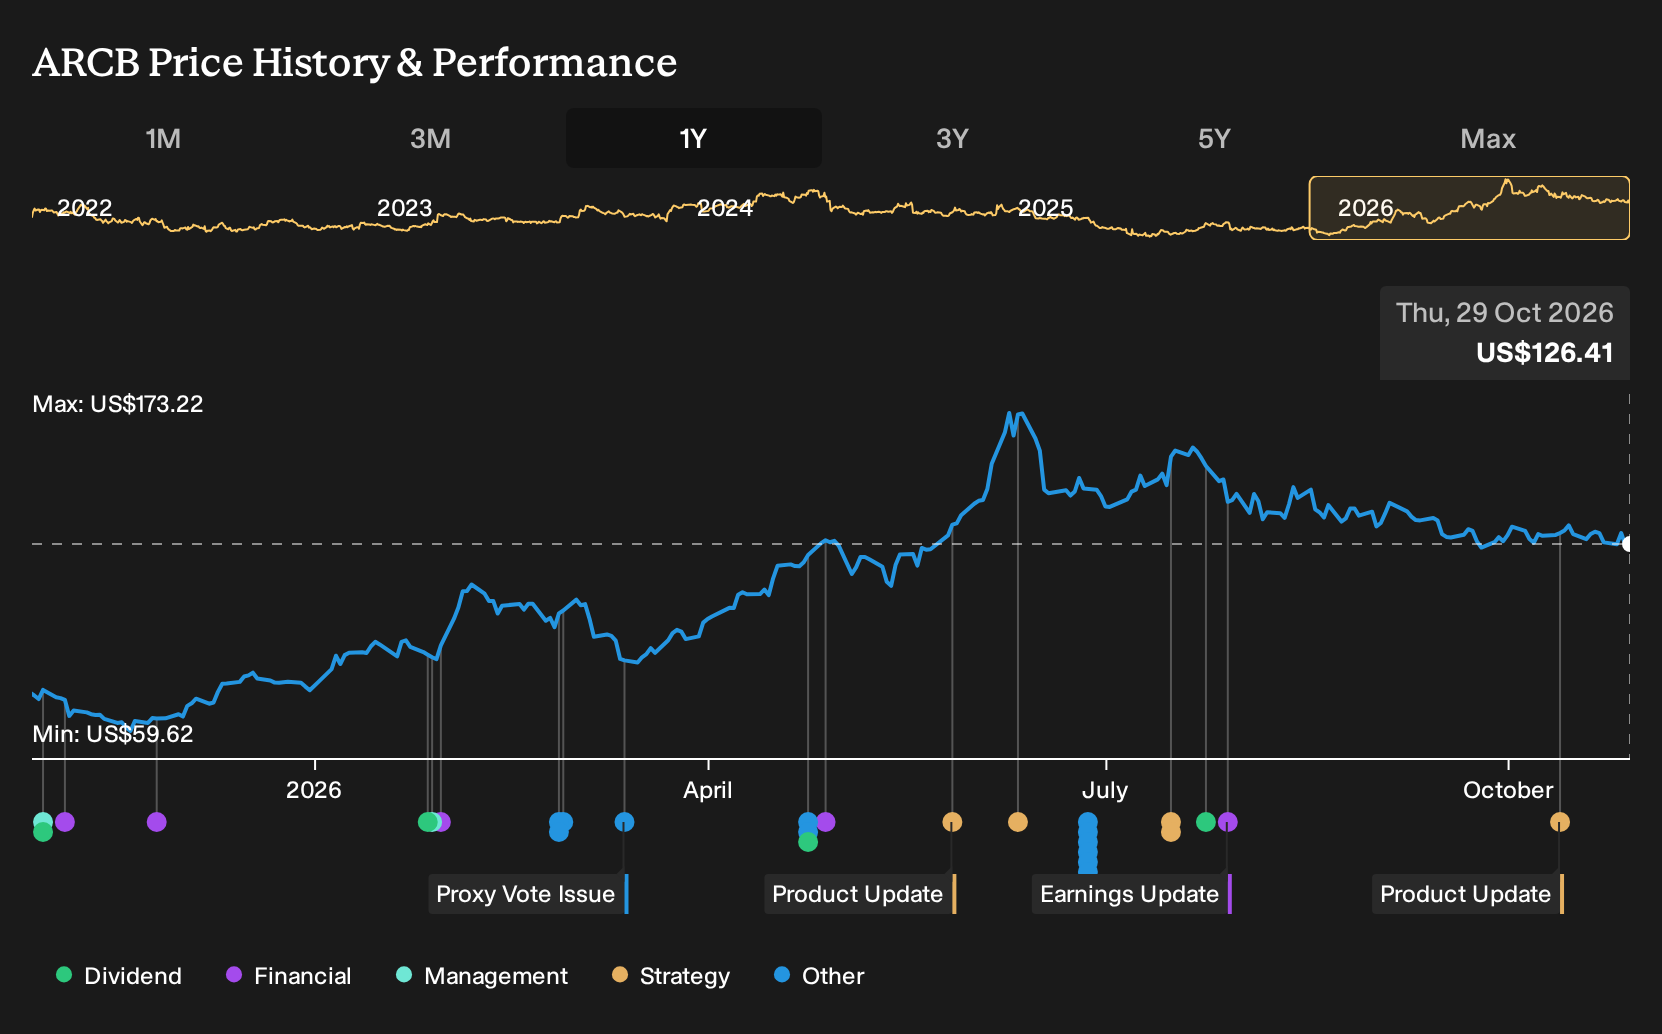
- ArcBest is scheduled to report results for the quarter ended September 2026, with analysts expecting higher earnings supported by stronger revenue for the period.
- The key angle is whether recent efficiency and cost actions will allow ArcBest to translate that revenue performance into meaningfully better profitability than what consensus expects.
- This analysis considers how ArcBest's potential earnings beat, if it occurs, could reshape the existing investment narrative around efficiency and margins.
Compare ArcBest's earnings setup with a curated list of transport and logistics players that also score well on efficiency and balance sheet strength using the list of solid balance sheet and fundamentals (23 results).
ArcBest Investment Narrative Recap
For ArcBest, the big picture to focus on is an efficiency story. The idea is that a more digital, asset light mix and a leaner LTL network can turn relatively modest freight demand into healthier earnings over time. The coming quarter matters mainly as a proof point on that execution rather than a make or break event.
The most important near term catalyst is whether recent cost work and technology rollout show up in cleaner margins despite muted industrial volumes and a heavier freight mix. The biggest risk is that weaker yields and higher insurance or claims costs keep squeezing profitability, leaving limited improvement even if revenue looks fine.
The current setup around the November 4 release ties closely to ArcBest's push into optimization and digital tools like ArcBest View, which aim to make quoting, booking and tracking more seamless. Earnings expectations that are tied to higher revenue only really help if these platforms and the reworked network allow the logistics operation to run more productively.
Freight mix, pricing discipline and cost control sit at the center of that story. If heavier shipments continue to pressure revenue per hundredweight while expenses such as labor and insurance remain elevated, the upside from higher engagement in the Asset Light and Managed Solutions segment could be harder to see in reported margins, keeping execution under scrutiny.
ArcBest's long term narrative centers on analysts projecting US$5.4b in revenue and US$426.4m in earnings by 2029. This projection assumes revenue growth of 8.8% per year and an earnings increase of about US$410.1m from current earnings of US$16.3m.
Uncover why ArcBest's fair value indicates a 34% potential upside to its current price, which could narrow quickly if ArcBest's efficiency story gains broader attention.
Exploring Other Perspectives
One alternate view on ArcBest focuses on digital risk. Some analysts worry that online freight platforms could blunt ArcBest’s edge, so their pre earnings models only penciled in revenue of about US$5.2b and earnings of roughly US$395.2m by 2029. You can treat this more cautious stance as one reference point and compare it with your own read on the latest numbers.
Explore 2 other ArcBest fair value estimates, including one that suggests as much as 39% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your ArcBest research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for ArcBest. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ArcBest's overall financial health at a glance.
Looking for more ArcBest investment ideas?
If this ArcBest earnings setup has you rethinking your watchlist, broaden the search and let the Simply Wall St Screener surface other opportunities with clear financial traits that match your style.
- For readers who want potential upside paired with disciplined balance sheets, scan a curated 30 high quality undervalued stocks that already clear a basic quality and fundamentals bar.
- If capital preservation ranks high for you, focus on sturdier businesses through a 30 resilient stocks with low risk scores where volatility and risk scores are kept in check.
- For those hunting for under-the-radar stories before they reach wider attention, filter a 18 high quality undiscovered gems that already show meaningful financial strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com