


SkyWest has delivered a powerful share price run over the past few years, yet the real question for anyone looking at the stock today is whether that move still lines up with the earnings the business is generating. With the shares recently closing at US$96.54, the focus naturally shifts to what the profit stream behind that price tag really supports.
- Over the past 3 years the stock has gained 116.9%, which puts a lot of weight on whether the current earnings base can carry that kind of re-rating.
- Recent profit growth, ongoing fleet additions and meaningful debt reduction can support a view that SkyWest's earnings profile and cash generation may be changing in ways that matter for valuation.
- There is a second opinion on SkyWest worth weighing. See what analysts think SkyWest's shares could be worth.
For investors, the debate is whether SkyWest's current earnings justify a share price around US$96.54 or whether the recent run has moved ahead of what the profit stream can reasonably support.
If you are weighing whether SkyWest's earnings still support a strong multi‑year share price run, it can help to compare that profile with 30 high quality undervalued stocks.
Is SkyWest Still Cheap on Earnings?
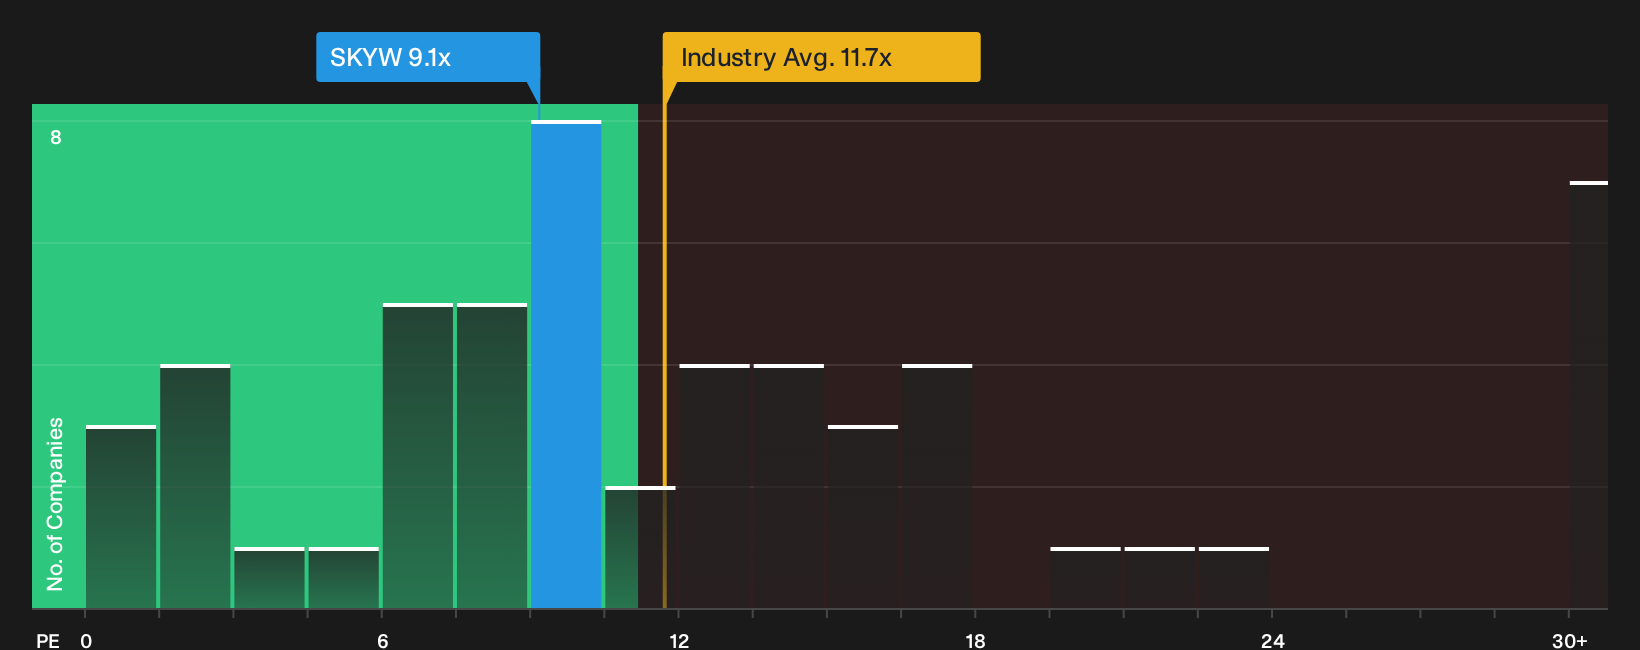
The P/E ratio fits SkyWest because earnings are now a key anchor for how the stock trades. On this yardstick, the shares change hands at roughly 9.1x earnings, compared with an Airlines sector average around 11.7x and a broader peer group near 13.1x.
That puts SkyWest at a discount relative to what the business specific fair multiple would suggest, based on its mix of growth prospects, margins, size and risk profile. Because management has just reported a US$120 million quarterly profit alongside continued fleet investment and debt paydown, the current gap between the 9.1x P/E and those higher reference points indicates that the stock is still priced below what many similar businesses command. Explore the numbers behind SkyWest's P/E valuation.
The SkyWest Narrative: What Would Justify Today's Price?
Narratives for SkyWest pick up where the P/E comparison leaves off and spell out which future paths for growth, margins and earnings would line up with a meaningfully higher or lower share price than today’s. Instead of a single ratio or valuation output, you see the underlying earnings story that figure assumes, so you can watch SkyWest's actual progress and judge whether that embedded future still looks realistic.
One of the top community narratives on SkyWest: 23% undervalued
"The current valuation implies the market is discounting SkyWest's progress on deleveraging, free cash flow and fleet upgrades, which reflects a view…"
Discover why this Narrative puts SkyWest at 23% undervalued.
SkyWest's price is only one piece of your decision
Valuation tells you what the market is paying for SkyWest today, but the research also flags specific risk checks that could change how you feel about the story. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com