


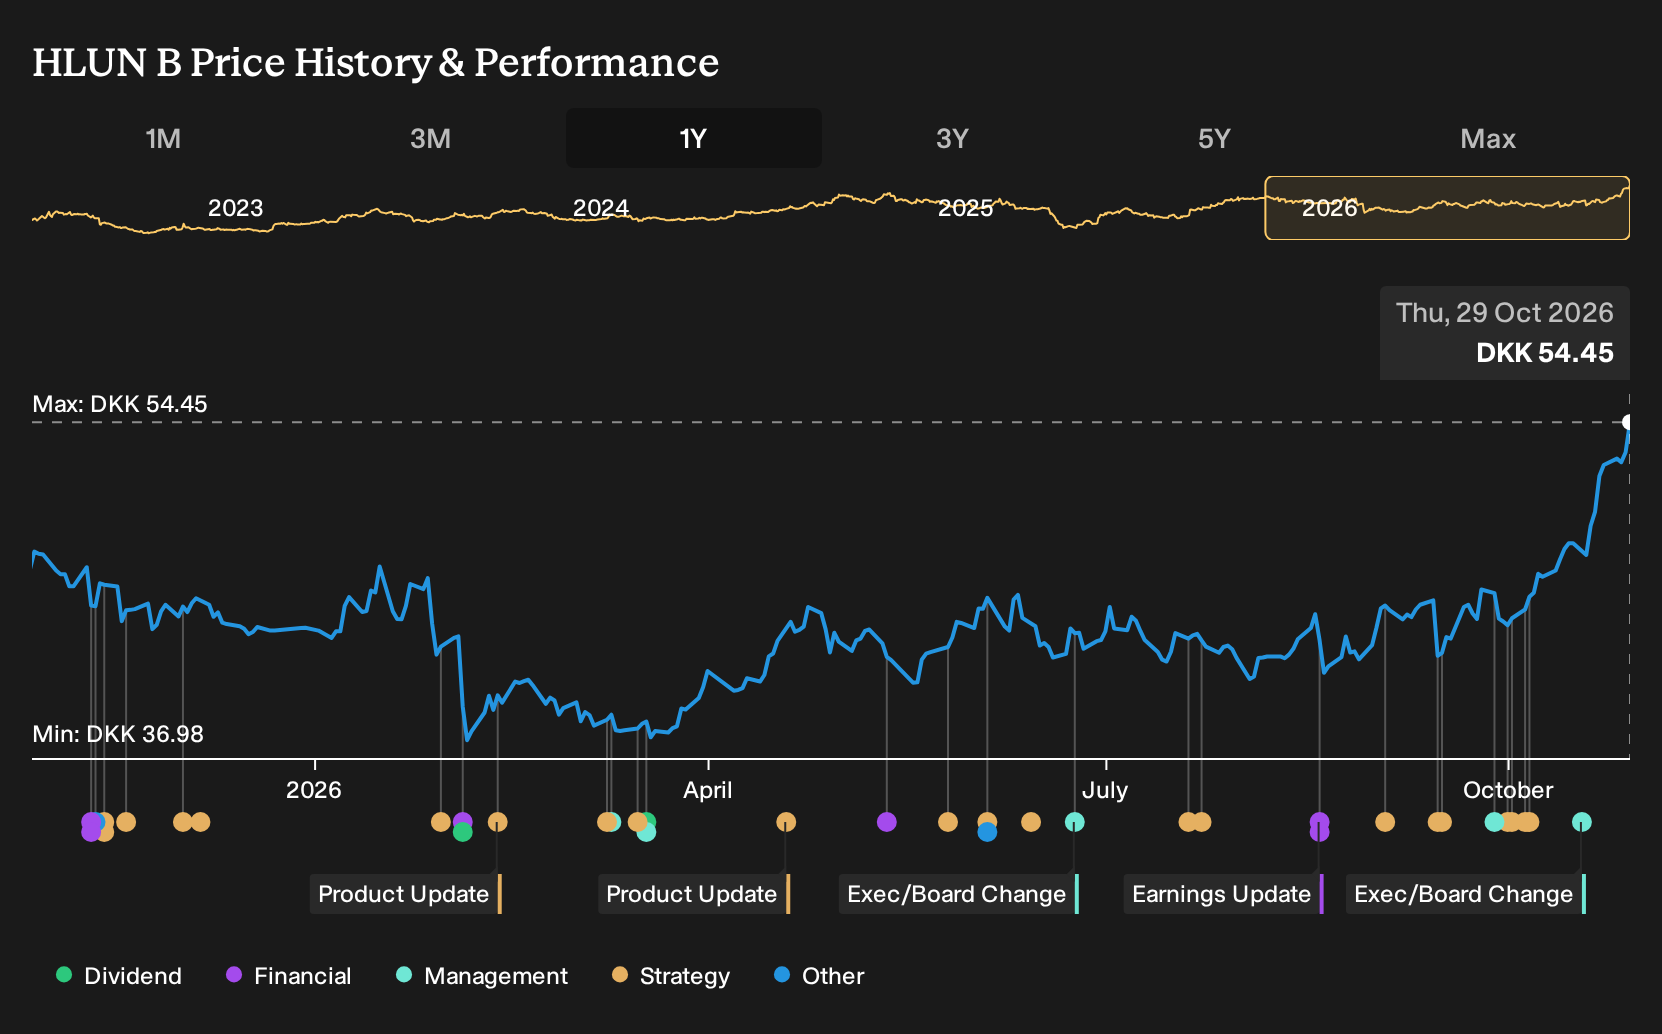
- H. Lundbeck disclosed that Chair of the Board Dorothea Wenzel, who joined the Board in 2021 and became Chair after the March 2025 AGM, plans to step down at the 2027 AGM as the company advances its Focused Innovator strategy.
- The planned handover of Board leadership during the shift into the Scale phase may influence how Lundbeck balances execution risk, oversight of R&D spend and commercial focus for its concentrated neuroscience portfolio.
- We will now look at how Lundbeck's investment narrative could be affected by the planned 2027 Board leadership transition.
Scan how H. Lundbeck's planned leadership shift compares with peers preparing for their own next phase by reviewing the hand picked 220 resilient stocks with low risk scores.
H. Lundbeck Investment Narrative Recap
Lundbeck asks you to believe that its Focused Innovator model can keep turning heavy R&D spend into migraine and CNS drugs that matter commercially, while a concentrated set of brands stays resilient. The planned 2027 chair transition looks orderly and, based on today’s information, does not materially shift the near term story.
The key near term swing factor still sits with execution on Vyepti, Rexulti and the Abilify long acting franchise and how well newer launches offset pressure from older products. Biggest risk remains concentration. Any stumble in clinical progress or uptake for a few therapies could matter more than who holds the gavel in the boardroom.
Against this leadership news, the Focused Innovator strategy itself is the announcement that matters most. Management is now talking about moving from a transformation phase into a Scale phase, where the goal is to turn pipeline work and commercial changes into more durable cash generation.
For you, the question is whether Lundbeck can keep R&D at roughly 20 to 25% of revenue and still protect earnings while revenue is forecast to decline about 3% a year and profit about 5.3% a year. Execution on that plan looks more important than the planned handover of the chair role in 2027.
H. Lundbeck's current narrative is based on analysts expecting revenue to decline by 2.0% a year, with earnings today at DKK 3.9b and consensus pointing to DKK 3.9b again in 2029, indicating no change in earnings levels over that period.
Uncover how H. Lundbeck's fair value indicates a 6% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternative angle is margin pressure. Some of the lowest Lundbeck analysts already saw higher R&D and competition as a squeeze point, with forecasts built on revenue drifting to about DKK 23.7b and earnings easing toward DKK 3.4b by 2029. Those pre news estimates sketch a more pessimistic story that could shift again after this board update.
Explore 3 other H. Lundbeck fair value estimates, including one that indicates as much as 8% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your H. Lundbeck research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for H. Lundbeck. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate H. Lundbeck's overall financial health at a glance.
Looking for more H. Lundbeck investment ideas?
If this H. Lundbeck boardroom story has you reassessing concentration risk and future cash generation, it can help to widen the lens and compare it with other listed businesses that fit different quality or income profiles using the Simply Wall St Screener.
- For investors who care most about financial resilience and balance sheet strength, review a list of solid balance sheet and fundamentals (203 results) that can help you stress test ideas beside H. Lundbeck.
- If your focus is on valuation and finding potentially mispriced opportunities, scan a 200 high quality undervalued stocks that may offer different risk return trade offs than a single neuroscience specialist.
- For readers who want income on top of potential capital gains, consider a 221 dividend fortresses that could complement or substitute a position in H. Lundbeck depending on your goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com