


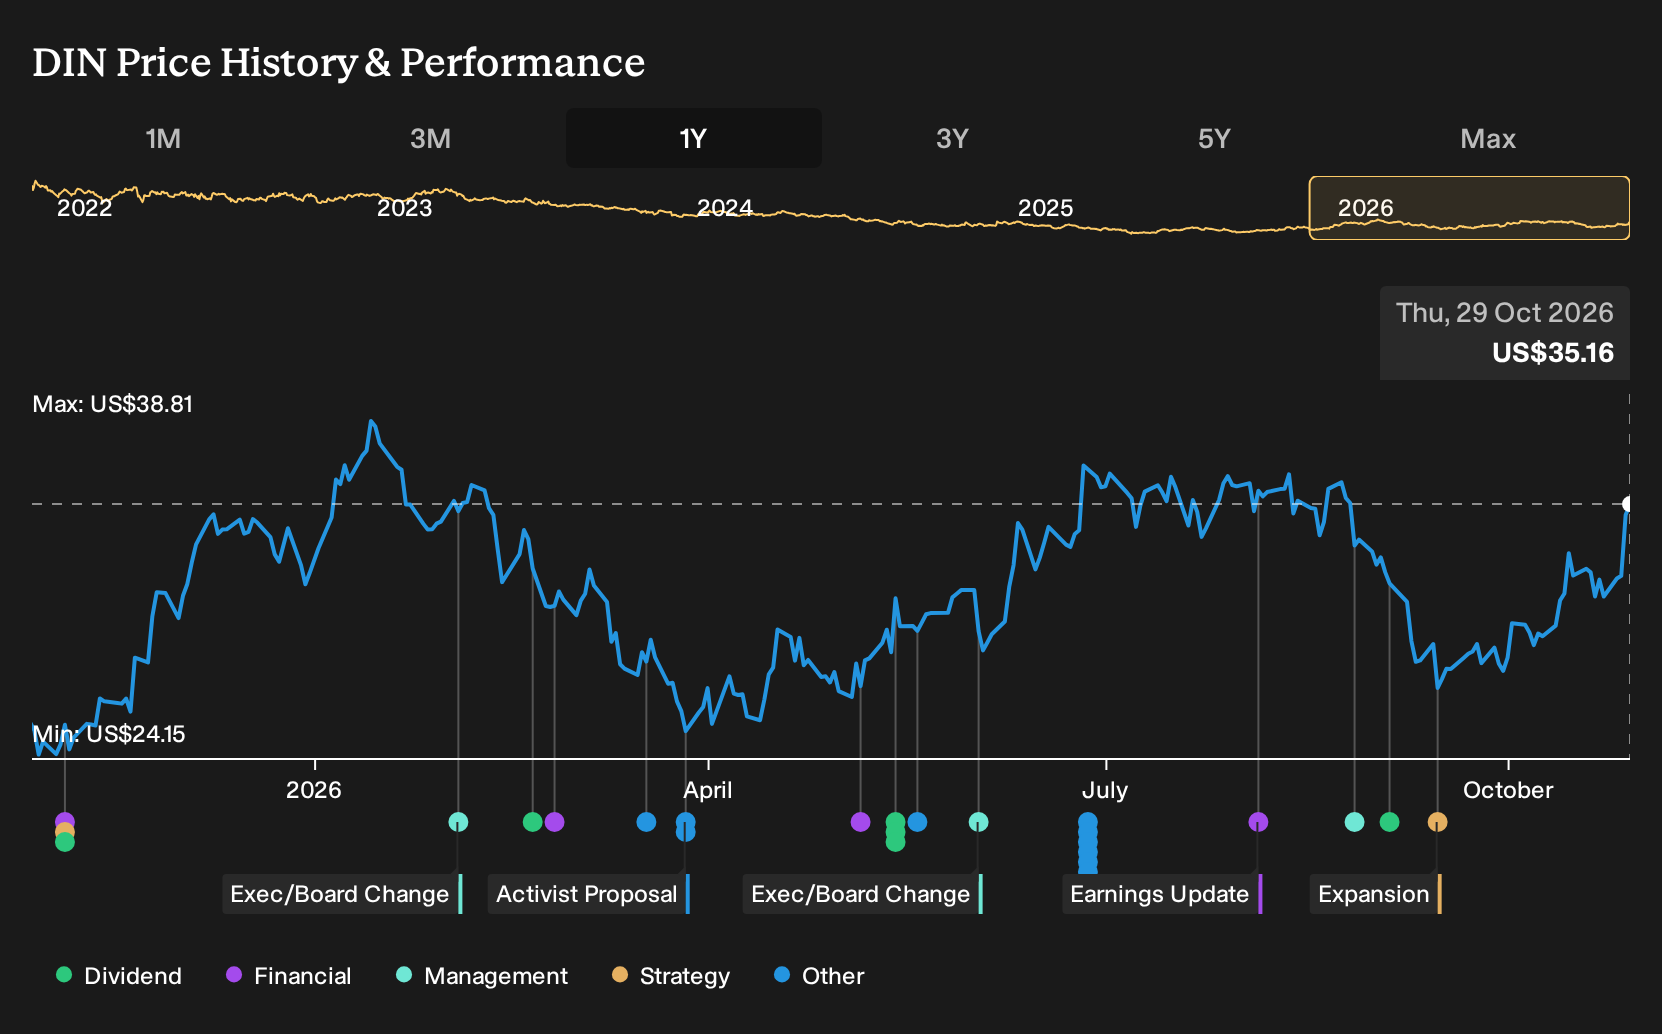
If you only looked at Dine Brands Global’s latest quarterly figures, with revenue and net margin pulling in different directions, you might not expect much of a payoff. Investors who held Dine Brands Global over the past year are up 45.8%, including dividends. That sits against earlier arguments that the shares were either 12% rich or 17% cheap at the starting line. If you were deciding on 29 October 2025, what would you have focused on to judge that risk?
The easy part of this move is behind Dine Brands Global. Zero in on 30 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Dine Brands Global
The shares cost US$25.22 at the start of the period, and the debate around Dine Brands Global hinged on whether Applebee's and IHOP could turn digital engagement into something more durable.
The bullish story pointed to a Fair Value of US$28.15, a price that would only make sense if digital loyalty, off premise sales above 20%, and international openings pushed revenue higher while margins improved from 6.6% to 8.0%.
The cautious view anchored on a Fair Value of US$21, tied to concerns that changing consumer tastes, rising labor and real estate costs, and pressure on franchisees would keep revenue growth modest and margins nearer 6.3%.
What The Results Changed For Dine Brands Global
The key fresh fact for Dine Brands Global was the Q2 2026 report, where revenue reached US$240.9 million and net income excluding extras was US$4.2 million. Net margin moved down to 1.7% from 5.7% a year earlier, so profitability compressed even as the top line was higher. That pattern affected both the bullish and cautious cases.
The lesson is simple. When a thesis leans on margin expansion, you track net margin first. Check whether each new quarter moves that percentage toward the original claim or away from it.
What Dine Brands Global’s Price Now Asks You To Believe
Today Dine Brands Global trades at US$35.16. The selected Narrative’s Fair Value sits below that level, which frames the current quote as paying up for execution on dual-brand stores, remodels, value menus and a heavily franchised, securitized balance sheet.
A buyer now is effectively betting those moves translate into healthier franchisee economics and sturdier systemwide sales. The question is how that assumption holds up against the Narrative’s concerns about cost inflation, construction closures and pressure on free cash flow.
"Although dual-brand Applebee's IHOP conversions are currently delivering higher sales and margin flow through on the incremental revenue, the modeled 900 unit opportunity over about 10 years relies on sustained franchise appetite and capital. These could be constrained if recent construction related closures and the higher cost to add the second brand weigh on unit level returns, which would cap the expected uplift in systemwide sales and royalties."
One Narrative disagrees with today's price. → See where this Narrative says Dine Brands Global should trade
Looking Beyond Dine Brands Global
Dine Brands Global leans on franchisees to turn restaurant demand into cash flow. You could look one step earlier in the trip instead.
Before anyone orders pancakes or burgers, they often decide where to stay. One digital platform specialises in that choice, not restaurant traffic.
Its marketplace connects people to places to sleep, activities and extra services. Hosts and guests meet there, while the platform mainly supplies matching and payments.
That focus on stays, experiences and services offers another way to tap travel spending. If trip planning keeps stretching beyond hotels, this model could quietly gain relevance.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 32% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com