


Consumer finance company OneMain Holdings (NYSE:OMF) announced better-than-expected revenue in Q3 2026, with revenue up 7.3% year on year to $1.36 billion. Its GAAP profit of $1.60 per share was 5.5% above analysts’ consensus estimates.
For more on OneMain, read the full research report, available free.
OneMain (OMF) Q3 2026 highlights:
- Net interest income $1.15 billion vs analysts’ consensus estimates of $1.13 billion (6.9% year-on-year growth, 1.6% beat)
- Revenue $1.36 billion vs S&P analysts’ consensus estimates of $1.34 billion (7.3% year-on-year growth, 1.5% beat)
- Pre-tax profit $233 million (17.2% margin)
- EPS (GAAP) $1.60 vs analysts’ consensus estimates of $1.52 (5.5% beat)
- Market capitalization $6.83 billion
"We delivered another strong quarter, building on the positive momentum across our business and demonstrating our ability to drive growth while maintaining rigorous credit discipline," said Doug Shulman, Chairman and CEO of OneMain. "We are confident in our ability to deliver attractive returns for shareholders well into the future."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term. Over the last five years, OneMain grew its revenue at a tepid 5.6% compounded annual growth rate, falling short of our standard for the financials sector.
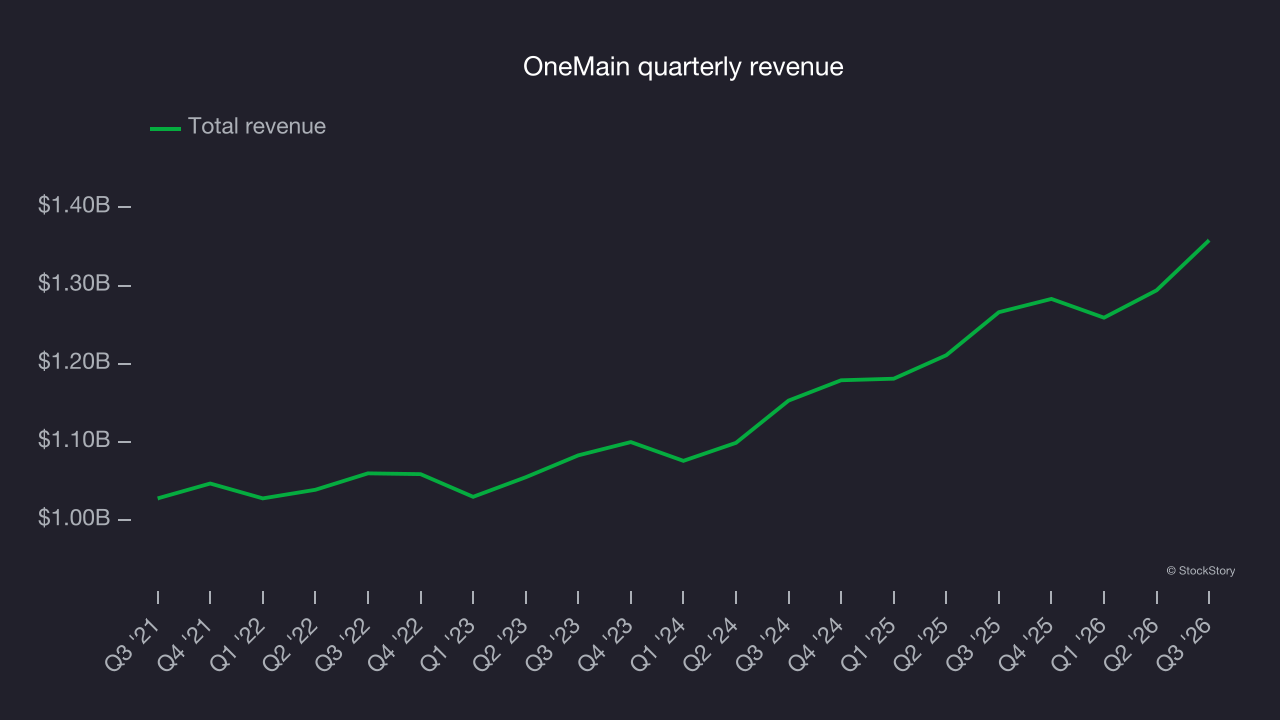
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. OneMain’s annualized revenue growth of 8.3% over the last two years is above its five-year trend, suggesting some bright spots. 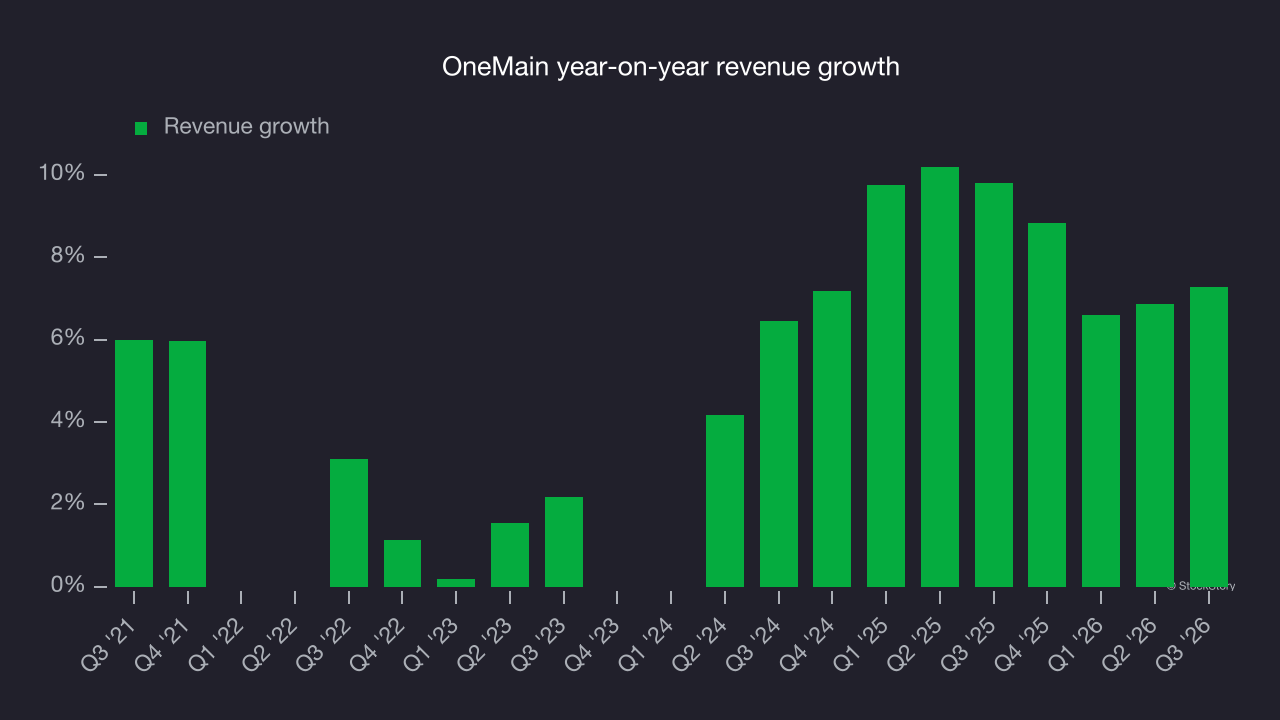 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, OneMain reported year-on-year revenue growth of 7.3%, and its $1.36 billion of revenue exceeded Wall Street’s consensus estimates by 1.5%.
Key takeaways from OneMain’s Q3 results
OneMain’s net interest income and EPS both topped analysts’ consensus estimates, giving its Q3 results some clear positives. Shares remained flat at $59.36 immediately after the release.
OneMain may have had a good quarter, but does that mean you should invest right now? When making that decision, it’s important to consider its valuation, business quality and latest quarterly results. For more on OneMain, read our full research report here (it’s free).