


FedEx (FDX) just paired a stronger third quarter with a higher full year earnings outlook by leaning on premium shipping demand, cost cuts under Network 2.0, and recent portfolio moves including the FedEx Supply Chain sale.
FedEx shares have been grinding higher, with a 7.08% 1 month share price return and a 5.01% year to date gain. The 1 year total shareholder return of 56.17% suggests the market has been steadily re-rating the stock as earnings guidance, portfolio reshaping, and a new CFO appointment reset expectations for both growth prospects and execution risk.
Scan FedEx’s premium shipping momentum against other logistics and infrastructure plays by comparing it with a curated list of 54 AI infrastructure stocks in one place.
FedEx now trades at a discount to both analyst targets and some fair value estimates after a strong guidance reset. Is that gap mispricing execution progress, or a warning that the market’s caution still has teeth?
Most Popular Narrative: 13% Undervalued
FedEx closed at $307.82 against a most-followed fair value estimate of $355.10, so the core debate now hinges on whether its cost and data programs can carry earnings far enough to justify that gap.
Expansion of data and AI driven tools such as delivery time window tightening, aircraft maintenance efficiency and computer vision surcharge capture is turning FedEx's large first party data set into a driver of higher revenue per shipment and leaner operating costs. This in turn directly affects operating income and margin structure.
See why 99 investors see FedEx as 13% undervalued.
Result: Fair Value of $355.10 (UNDERVALUED)
Still, the FedEx narrative leans heavily on flawless AI execution, while exposure to large contracts and weather disruption could quickly challenge those margin and cash flow assumptions.
Find out about the key risks to this FedEx narrative.
Another View: FedEx Through The P/E Lens
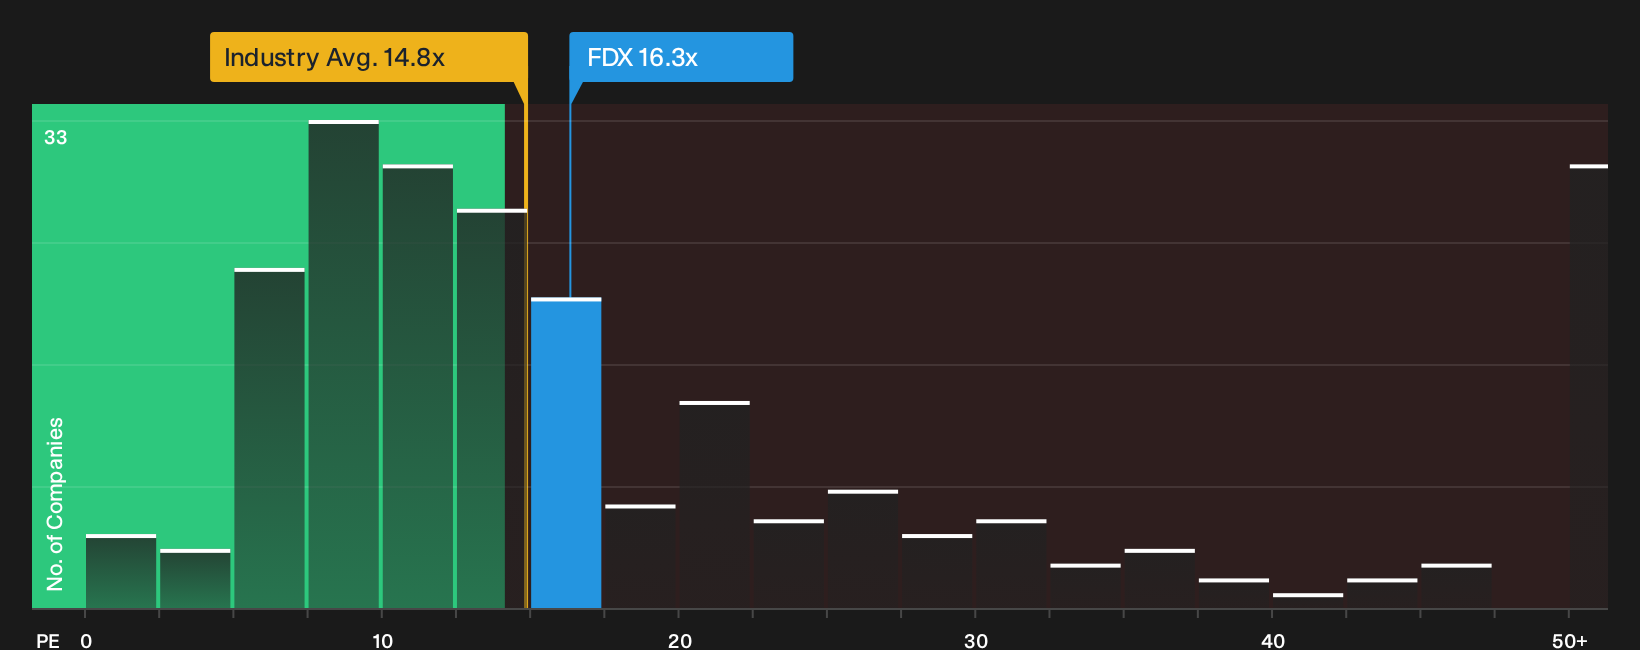
The SWS DCF model paints FedEx as deeply undervalued, with the stock at $307.82 versus an estimated future cash flow value of $578.66. Yet on a simpler P/E check it looks less extreme, trading at 16.3x earnings versus a 14.8x industry average and a 20.1x peer average fair ratio that the market could move toward. Does that gap signal a cushion or a value trap if sentiment cools?
See what the numbers say before leaning on one approach too heavily, then weigh the story against your own expectations for FedEx’s execution and risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of optimism and risk around FedEx right now. Move quickly to test the numbers yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond FedEx?
If FedEx has sharpened your appetite for opportunity, do not stop here. Use the same toolkit across sectors to pressure test your next move with real numbers.
- Target resilient balance sheets that can absorb shocks and still compound potential by scanning a curated list of solid balance sheet and fundamentals (23 results).
- Hunt for mispriced quality where fundamentals and valuation line up by combing through a focused 30 high quality undervalued stocks.
- Stack potential income on top of price returns by reviewing a filtered universe of 7 dividend fortresses before yields change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com