


- Gecina has leased the entire 10,300 sq.m 16 Capucines building in Paris to a global tech and data infrastructure security leader on a nine-year firm lease effective from mid April 2027, while relocating its own head office to the Signature building in Saint Lazare.
- The full building lease to a technology tenant and Gecina’s move into Signature highlight current demand for centrally located, service rich Paris offices that can support collaboration and talent attraction.
- We will now look at how Gecina’s long term commitment from a major tech tenant could influence the company’s broader investment narrative.
Scan beyond Gecina and this single Paris lease by sizing up other prime office and infrastructure plays anchored by tech and data tenants in our 54 AI infrastructure stocks.
Gecina Investment Narrative Recap
To own Gecina, you need to believe that prime central Paris offices and well located residential assets can keep attracting tenants even while the broader office market stays soft. The key near term swing factor is lease up and retention in this core portfolio. The 16 Capucines deal and head office move are positive for operations, but not enough on their own to change that bigger picture.
The biggest risk still sits in prolonged weakness in wider Paris office demand and pressure on asset values while Gecina carries debt that is not well covered by operating cash flow. Any further value write downs or slow reletting outside core locations would weigh on earnings and could limit financial flexibility.
The nine year firm lease at 16 Capucines with a global tech and data infrastructure security group looks most relevant to the current thesis. It aligns with the idea that tenants are concentrating into prime, energy efficient, service rich buildings where Gecina is most exposed. For an investor, it gives a clearer view on future cash flows from that asset once the lease starts in 2027.
Operationally, that contract also connects to Gecina’s wider pipeline around assets like Signature, where the head office will move alongside other top tier occupiers. The more these buildings are locked in with long leases at prime rents, the more room management has to focus on tougher spots in La Défense or peripheral submarkets, which still carry the main reletting and value risk.
Gecina's narrative projects €784.6 million in revenue and €756.0 million in earnings by 2028. This projection assumes revenue declines by 3.2% per year and requires an earnings increase of about €247 million from €509.3 million today.
Discover why Gecina's fair value indicates a 65% potential upside to its current price, which could narrow quickly.
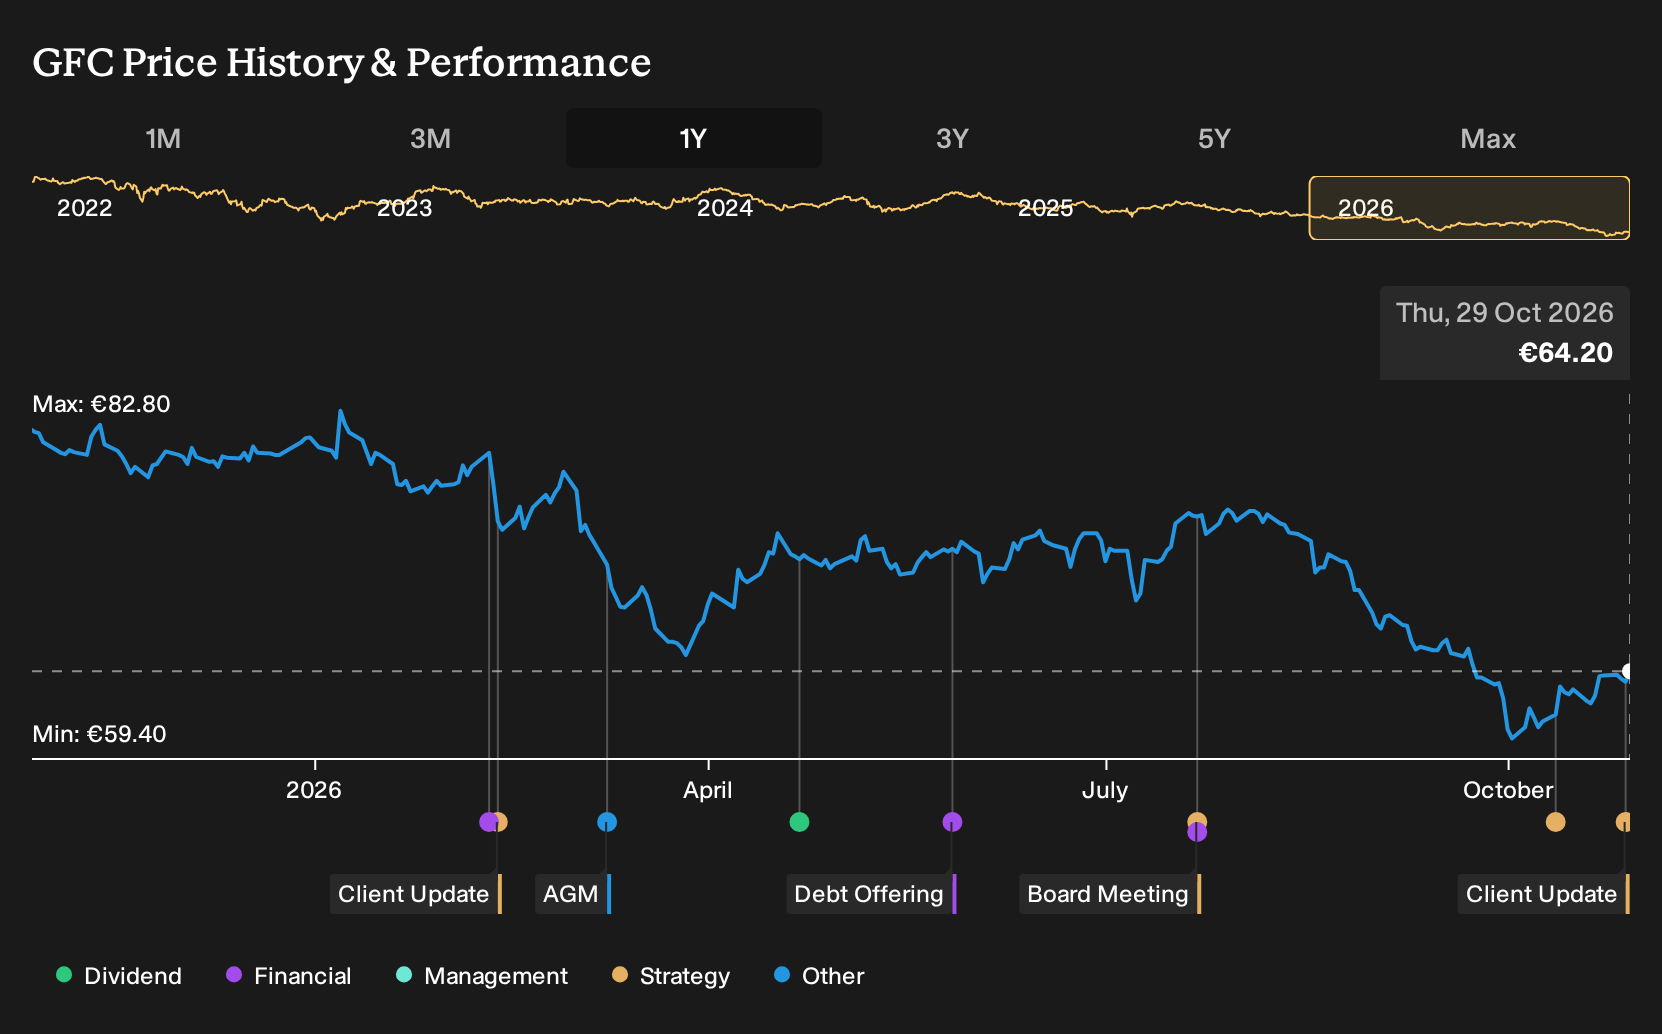
Exploring Other Perspectives
One alternate view on Gecina focuses on revenue risk. The most bearish analysts were assuming revenue would decline about 6.0% a year, with earnings only reaching €547.3 million by 2029 on €718.0 million of revenue. That is far below the more upbeat forecasts you saw earlier. With this new tech lease and head office move, those pre news assumptions may eventually shift.
Explore 3 other Gecina fair value estimates, including one that suggests it could be worth just €70.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Gecina research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Gecina. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gecina's overall financial health at a glance.
Looking For More Gecina Sized Investment Ideas?
If the Gecina story has sharpened your thinking about quality, income and risk, you can apply that same filter across the wider market with a few targeted screeners on Simply Wall St.
- For investors who want potential mispricing with solid fundamentals, start with a curated set of 200 high quality undervalued stocks that may warrant a closer look.
- If dependable payouts matter to you, focus on income opportunities built around 221 dividend fortresses that aim to pair yield with resilience.
- For a focus on resilience and downside protection, narrow your attention to a 220 resilient stocks with low risk scores that could help you prioritize stability first.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com