


CNO Financial Group (CNO) put earnings front and center this week, with third quarter results topping expectations and a higher full year operating EPS outlook giving investors fresh numbers to work with.
CNO Financial Group’s share price has gained 30.73% year to date to $55.17, with a 40.38% total shareholder return over the past year and a very large 3 year and 5 year total shareholder return above 140%, suggesting momentum has been building as earnings surprises and the latest guidance upgrade reshape how investors view its risk and income profile.
Scan how CNO Financial Group compares with other insurance and financial players gaining traction this year by reviewing our hand picked 30 resilient stocks with low risk scores.
CNO Financial Group now appears to be a stronger business based on recent earnings and guidance, but the share price has already moved ahead. The real test is whether that stronger story is already fully reflected in the valuation.
Most Popular Narrative: 2.6% Overvalued
CNO Financial Group closed at $55.17 against a narrative fair value of $53.75, which puts the recent rally up against a fairly tight valuation band that leans on a specific set of execution bets.
The main factor that has to go right is that CNO sustains productive captive distribution and Medicare Supplement repricing while executing its technology modernization, so that recent growth in Worksite, broker dealer assets and ROE does not fade back toward the weaker long term trends seen in premiums, margins and book value per share.
See why 1 investors see CNO Financial Group as 3% overvalued.
Result: Fair Value of $53.75 (OVERVALUED)
Still, the narrative can unravel if external data on soft premium trends persists, or if insider selling near highs continues to signal limited upside to other investors.
Find out about the key risks to this CNO Financial Group narrative.
Another View: Cash Flows Point To Undervaluation
While the CNO Financial Group narrative fair value of $53.75 suggests a slight premium at $55.17, the SWS DCF model presents a different picture. On that cash flow view, CNO screens as undervalued, with an estimated future cash flow value of $65.60, which implies more cushion in the current price. The question is which story carries more weight: the near-term earnings multiple or the longer-term cash stream.
Look into how the SWS DCF model arrives at its fair value.
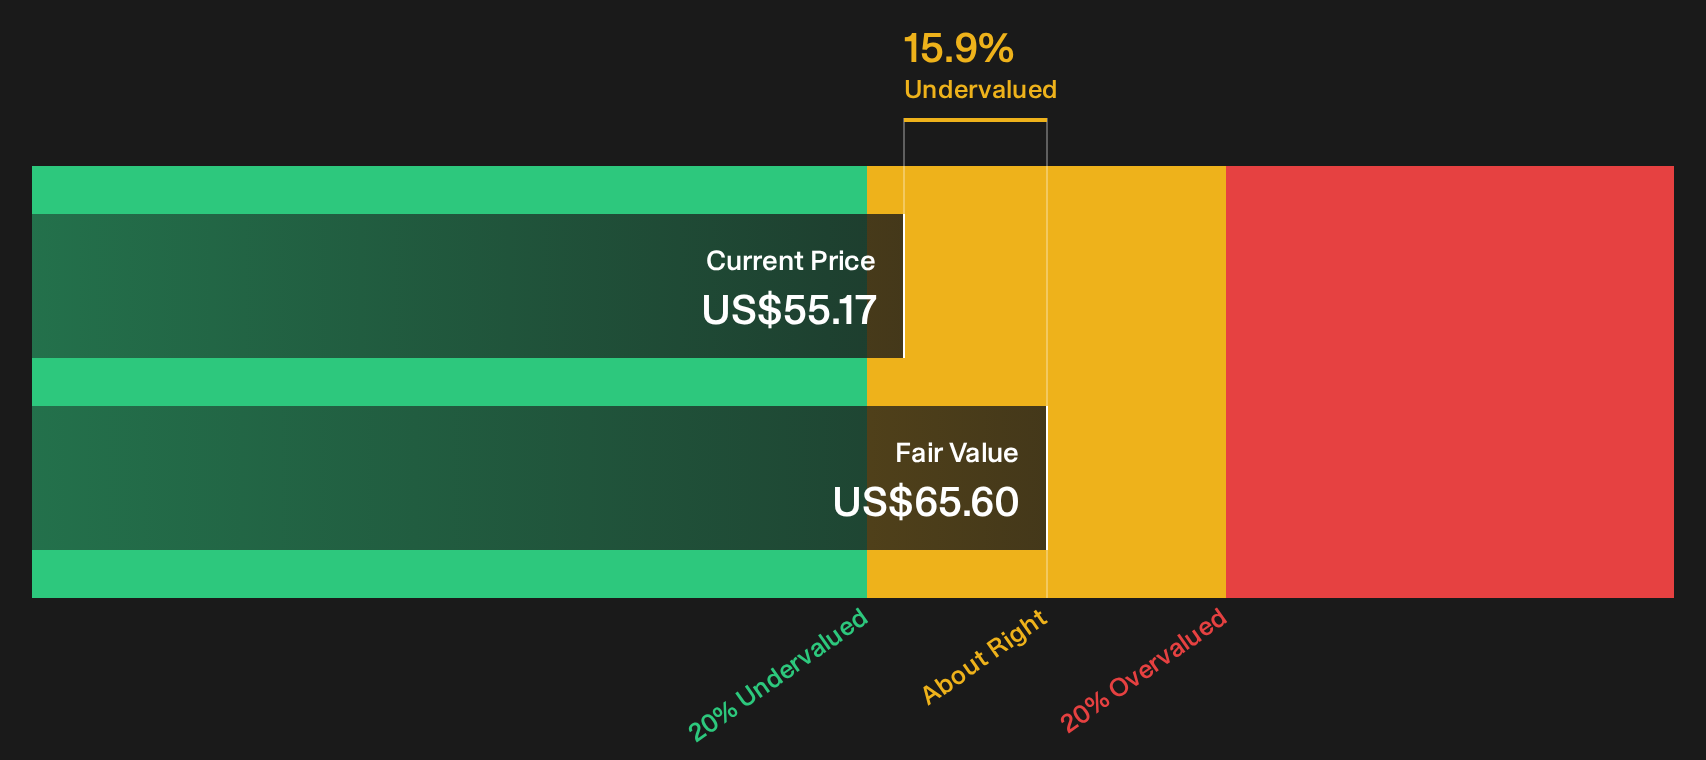
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CNO Financial Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the CNO Financial Group story so far. If you want to move quickly and decide for yourself, weigh both sides by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CNO Financial Group?
If CNO Financial Group has sharpened your focus on quality and valuation, broaden your watchlist now and pressure test your thinking across fresh opportunities.
- Target potential mispricing by scanning a curated pool of quality stocks that look cheap on the numbers through the 30 high quality undervalued stocks.
- Reinforce your income stream by zeroing in on proven payers with strong yields using the 7 dividend fortresses.
- Protect your downside by filtering for companies with robust finances and resilient balance sheets via the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com