


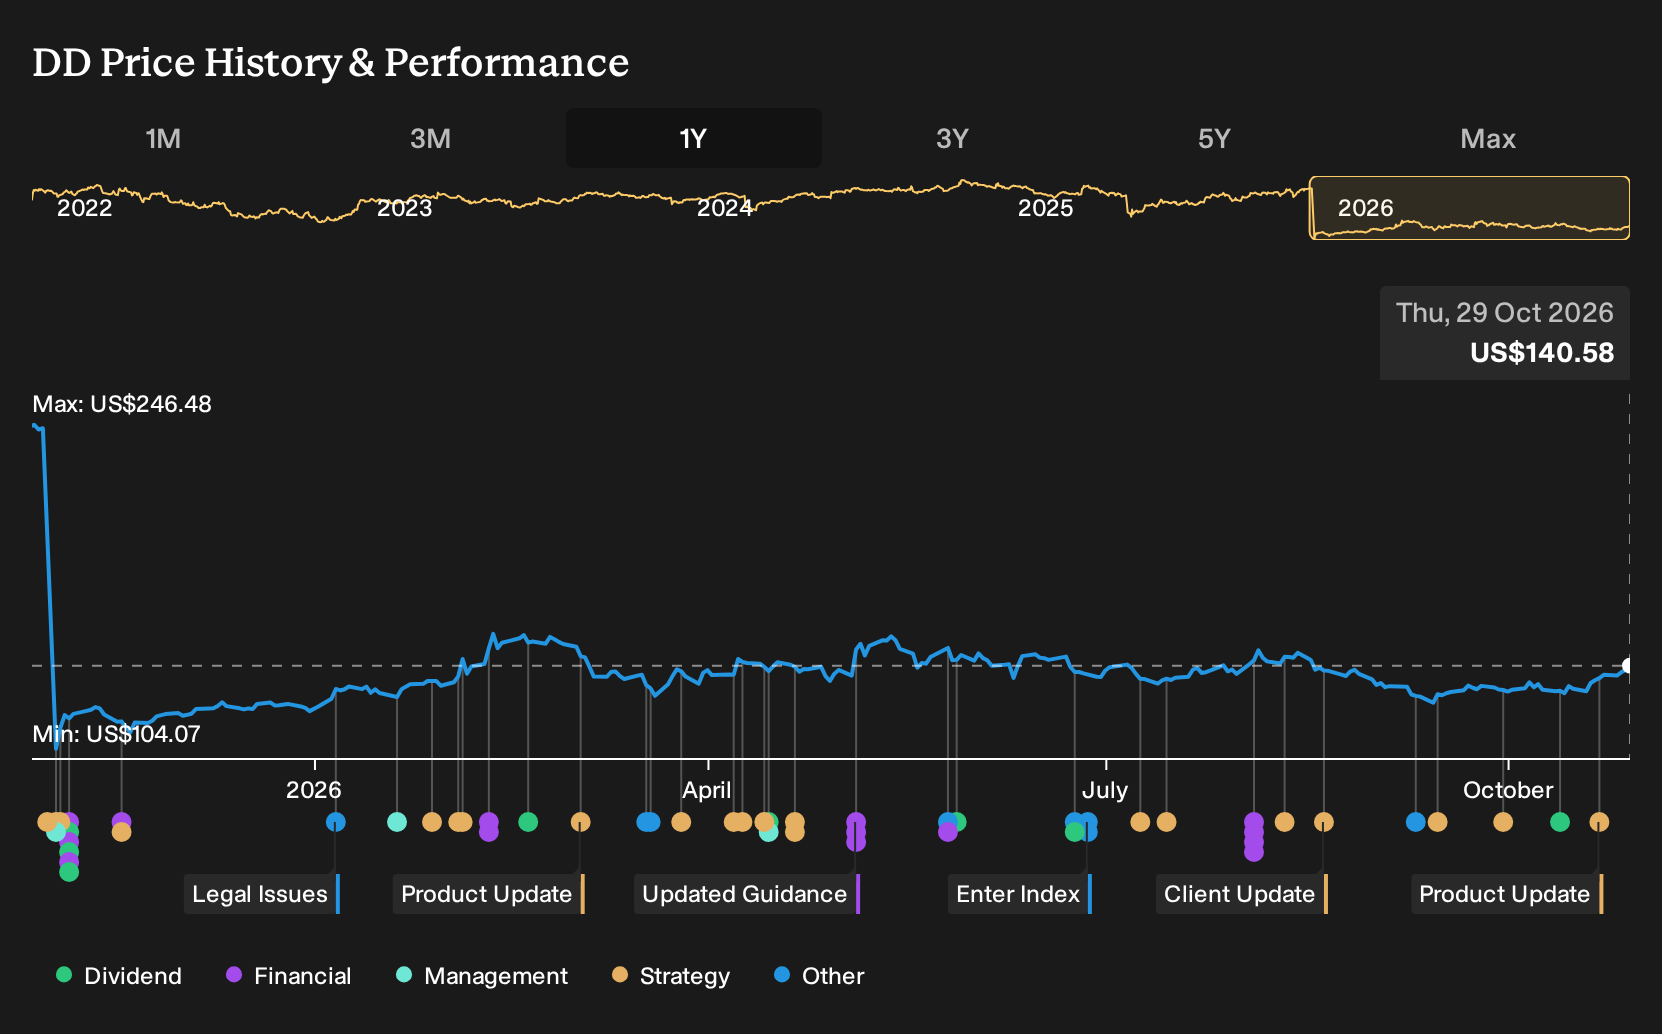
If DuPont de Nemours was sitting on your watchlist instead of in your account, the last twelve months may feel expensive. Investors who held DuPont de Nemours over the past year are up 39.9%, including dividends. That outcome raises a sharper question. Back on 29 October 2025, could a focus on electronics, healthcare and water, supported by specific revenue growth and margin assumptions, have helped you identify this setup before it occurred?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
DuPont de Nemours has already moved. Pinpoint other ways to investigate the theme among 36 healthcare AI stocks.
The Argument You Would Have Been Weighing Up On DuPont de Nemours
The shares cost US$82.16 at the start of the period, which meant any decision on DuPont de Nemours hinged on which story about its future you found more convincing.
The bullish narrative saw a focused electronics, healthcare and water specialist with a Fair Value of US$92.67, or 13% above the start price. That view leaned on 3.0% revenue growth assumptions and a 12.7% profit margin, supported by an expected future P/E of 27.9x over a 3 year window.
The bearish story carried a Fair Value of US$47 and focused on concerns about long term ESG and PFAS burdens. That case highlighted rising environmental regulation and litigation as ongoing risks to profitability and future earnings growth for DuPont de Nemours.
What The Results Changed For The DuPont de Nemours Story
DuPont de Nemours posted Q2 2026 revenue of US$1,819m and net income of US$187m, up from US$1,749m and US$13m in Q2 2025, with net margin moving from 0.7% to 10.3%. That shift in profitability supported parts of the bullish electronics, healthcare and water thesis, while ongoing PFAS settlements and new ESG targets kept the cautious case alive. Overall, the evidence cut both ways.
The decision back in October 2025 hinged on whether higher margins in refocused segments would actually show up in the accounts. For any other stock built on a similar profitability story, you would want to track changes in net margin alongside segment mix, rather than relying only on revenue or guidance headlines.
What DuPont de Nemours Buyers Are Being Asked To Believe Now
Today DuPont de Nemours trades at US$141, after a 39.9% gain over the past year. The selected Narrative still places its Fair Value above that level, based on a focused portfolio in healthcare, water and industrial applications.
The argument leans on productivity programs, free cash flow and capital returns. A buyer now has to judge whether sustained 3% net productivity of COGS can keep offsetting cost pressures and environmental spend.
"Ongoing productivity programs that target 3% net productivity of COGS each year, coupled with already delivered COGS reductions and efforts to push cost of poor quality below the current 4% of sales, create room for further operating EBITDA margin expansion and earnings growth if execution continues."
The price and this Narrative do not agree. → Uncover what this Narrative says DuPont de Nemours is actually worth
Looking Beyond DuPont de Nemours
Once you understand DuPont de Nemours, your eye can shift sideways to infrastructure. AI hardware still needs something more basic than specialty materials.
All that processing power only matters if data centers stay online. Reliable power and cooling turn racks of chips into usable computing capacity.
Another business concentrates on that plumbing behind the scenes. It builds systems that move heat away from equipment and keep electricity flowing.
Instead of chemicals or membranes, its expertise is thermal control and uptime. As AI buildouts grow denser, that kind of backbone can shape what is possible.
That argument has a Narrative and a number behind it. → See the company one Narrative values 66% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com