


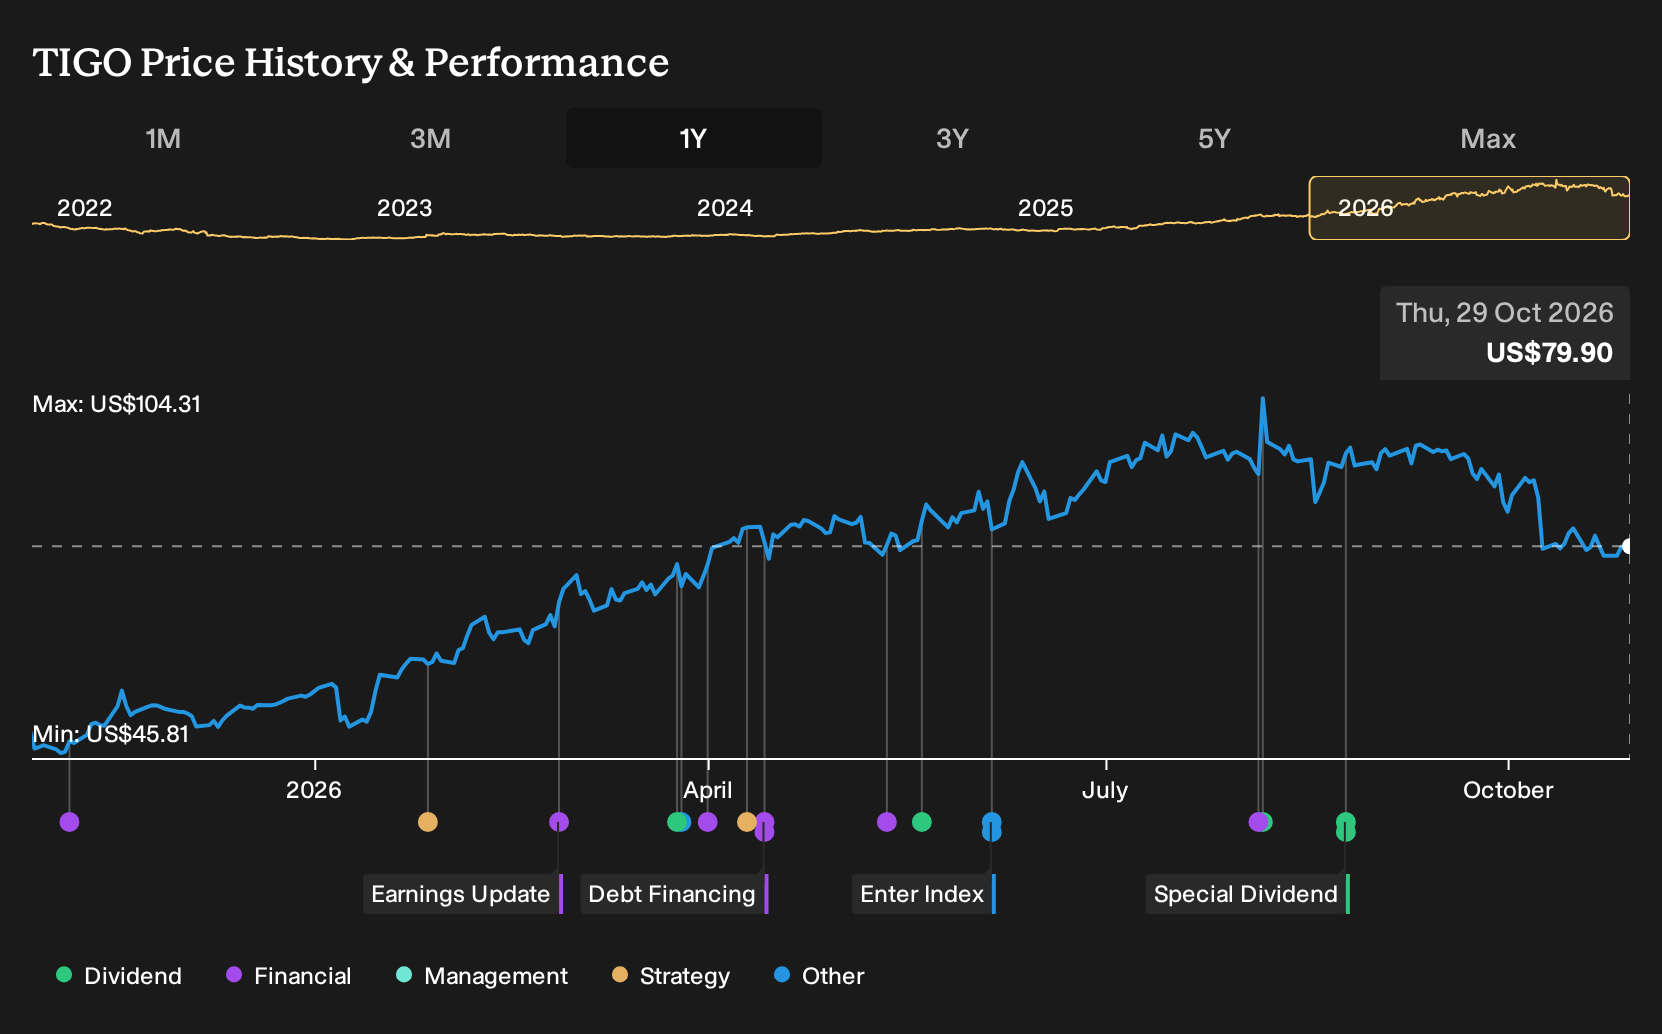
If Millicom International Cellular sat on your watchlist rather than in your portfolio over the past year, the result may feel expensive. Investors who held Millicom International Cellular over the past year are up 79.4%, including dividends. That jump invites a blunt question. Back on 29 October 2025, when analysts were arguing over whether rising smartphone use would really translate into profitable broadband and postpaid growth, what could have helped you judge that assumption more clearly?
If the move has made Millicom International Cellular harder to judge, start where the gap is still open and scan 30 high quality undervalued stocks.
The Argument Millicom Investors Were Really Weighing
The shares cost US$46.56 at the start of the period, and anyone looking at Millicom International Cellular then was effectively choosing between two very different but plausible stories.
The bullish camp pointed to a Fair Value of US$55, essentially the price implied if revenue grew 3.3% a year with profit margins settling at 10.7% and the stock trading on a 15.5x future P/E.
The bearish view argued for a Fair Value of US$36, built on assumptions of revenue growth of only 1.0%, profit margins easing to 8.9%, and a 13.2x future P/E multiple.
What The Results Changed For The Millicom International Cellular Story
Q2 2026 results gave bulls their best data point. Millicom International Cellular reported revenue of US$2.18b compared with US$1.37b a year earlier, helped by acquisitions and integration progress. That topline outcome supported the optimistic case that more smartphones and broadband would expand the addressable market, although execution costs and deal activity clearly mattered too.
Profit told a harsher story and kept the cautious camp alive. Net income excluding extra items dropped from US$674m to US$108m and net margin moved from 49.3% to 5.0%. The useful takeaway elsewhere is simple. When a thesis leans on higher profitability, track net margin first and only then judge any revenue surge.
What Millicom’s Run Leaves You Paying For Today
Millicom International Cellular now trades at US$79.9, and the selected Narrative’s Fair Value sits below that level. That view rests on the idea that recent operational gains and cash generation could face strain if legal issues, regulation and heavier brand spending absorb more of the economics.
The real question is what has to keep working for this price to hold, especially whether Millicom International Cellular can keep converting its efficiency push and deal playbook into strong EBITDA margins and equity free cash flow while those Ecuador and Guatemala pressures remain live.
"The main thing that has to go right is that Millicom International Cellular needs to keep translating its efficiency culture and M&A playbook into sustained high EBITDA margins and strong equity free cash flow while managing ongoing legal and governance challenges."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Where Millicom’s Story Connects Next
Millicom International Cellular is all about connections on the ground. Your next question is what other links those customers might need.
Households that pay Millicom for mobile and broadband still rely on wider connectivity grids. Another business spends heavily on wireless and fiber networks that carry those flows.
Enterprises chasing secure links, remote work tools and AI connectivity need more than local towers. They look for private networks, dark fiber and long contracts that lock in reliability.
A single provider trying to do everything can stretch its balance sheet. A specialist that already runs those broader pipes could influence where value in telecom shifts next.
That argument has a Narrative and a number behind it. → See the company one Narrative values 18% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com