


- Hanza reported third quarter 2026 sales of SEK 2,487 million and net income of SEK 123 million, with basic EPS of SEK 1.96 from continuing operations, and nine month sales of SEK 7,706 million and net income of SEK 304 million.
- The combination of higher sales and net profit for both the quarter and the first nine months is consistent with stronger operational execution and cost control across Hanza's manufacturing clusters.
- We will now assess how Hanza's higher third quarter and nine month earnings may reshape the existing investment narrative around the business.
Scan how Hanza's earnings momentum compares with other manufacturers by reviewing our hand-picked list of solid balance sheet and fundamentals (203 results) that could handle similar order trends without stretching their finances.
Hanza Investment Narrative Recap
To own Hanza, you need to trust that its cluster manufacturing model, the Horizon restructuring and the Fortaco heavy mechanics carve out all pull in the same direction. The latest quarter, with SEK 2,487 million in sales and SEK 123 million in net income, supports the view that the operating footprint can carry higher volumes without obvious strain.
The short term hinge is execution on integration and component availability. Stronger nine month earnings of SEK 304 million ease concerns around near term profit pressure but do not remove the risk that PCBAs and memory constraints or Horizon related volume loss could still pinch margins if conditions tighten from here.
The Fortaco carve out remains the announcement that matters most against this earnings backdrop. Management has framed it around roughly €170 million in extra annual sales, five factories and a targeted EBITA margin contribution near 9%, which now sits beside a group that has just reported SEK 7,706 million in nine month revenue and SEK 4.88 in basic EPS.
For you as a shareholder, that pairing turns Fortaco into both an opportunity and a test. Higher reported earnings give Hanza a bit more headroom as it absorbs new debt, chases integration synergies and tries to hold net debt to EBITDA below 2.5x, while any stumble on efficiency or component sourcing would quickly show up in profitability for the larger group.
Hanza's current analyst story points to SEK 15.6b in revenue and SEK 938.5m in earnings by 2029, built on assumed 23.0% yearly top line growth and an increase in profit from SEK 336.0m today to the SEK 938.5m consensus, which is roughly 2.8x higher.
Uncover how Hanza's fair value indicates a 10% potential upside to its current price before the market closes this gap.
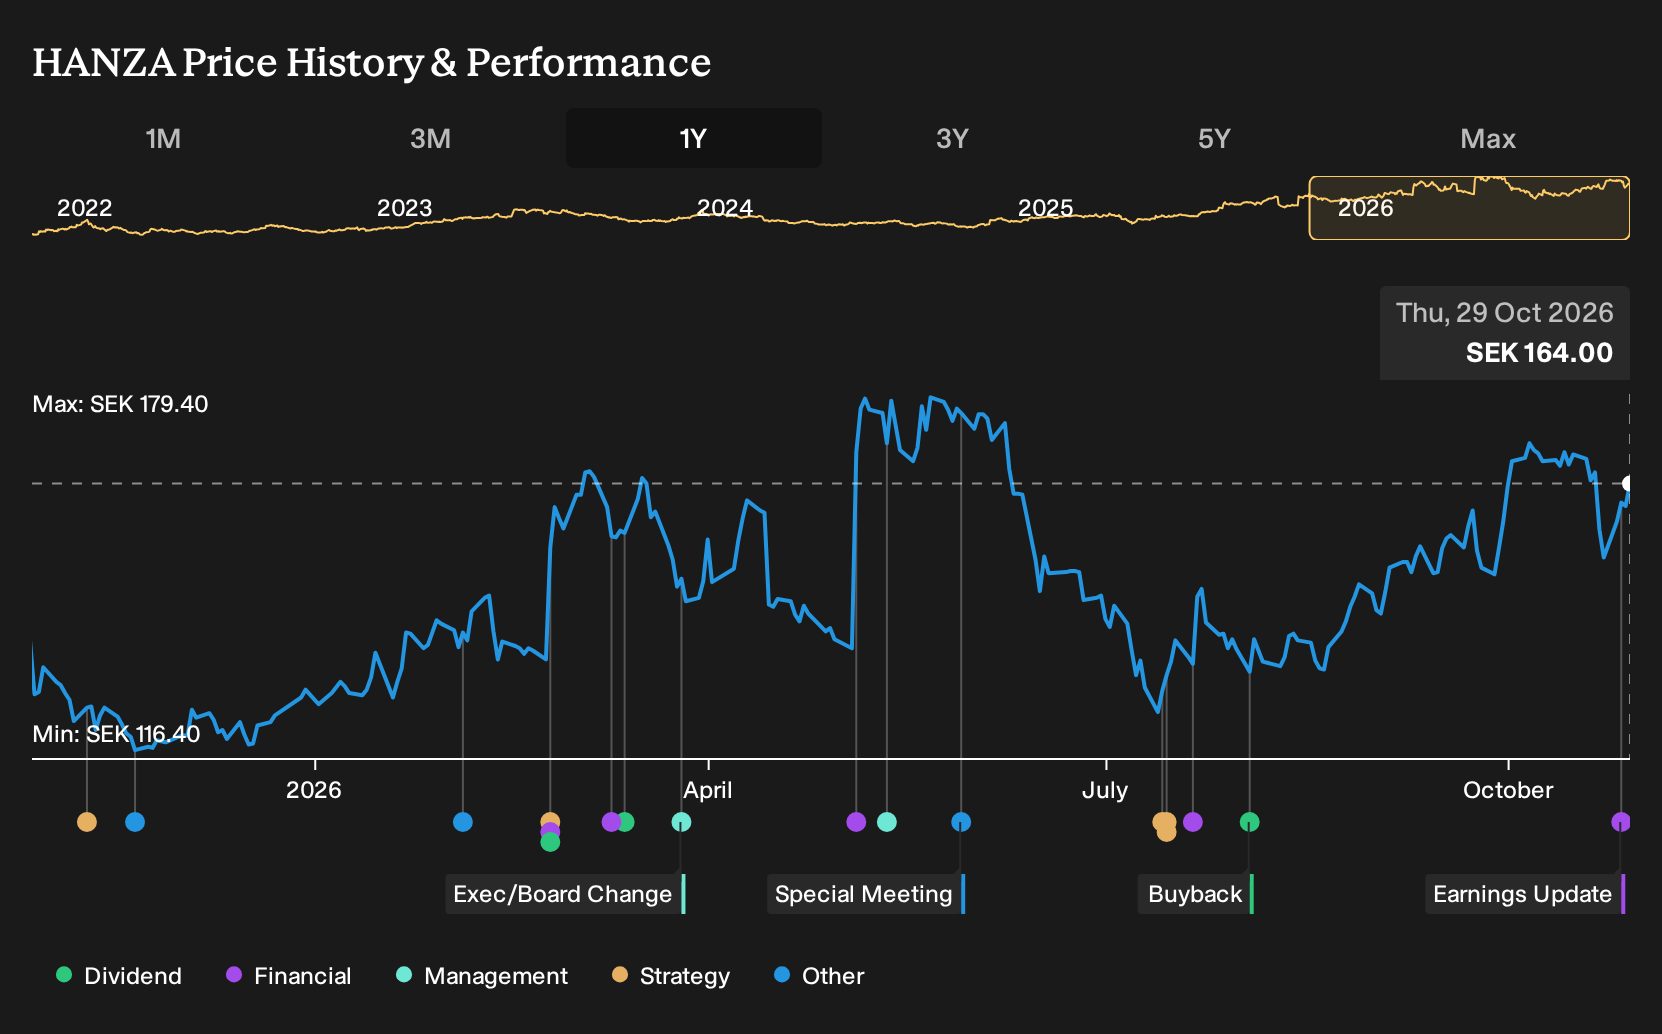
Exploring Other Perspectives
One alternative view on Hanza leans hard into Fortaco as a catalyst. The most bullish analysts were already pencilling in about SEK 16.1b of revenue and SEK 964.2m of earnings by 2029 before this Q3 report landed. You now get to ask whether these fresh numbers push that optimistic script even further or force a rethink.
Explore another Hanza fair value estimate, including one that suggests as much as 62% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Hanza research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hanza. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hanza's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hanza?
If Hanza has sharpened your focus on quality execution and solid finances, it can be useful to widen the lens and see which other companies also line up with your risk and return preferences using the Simply Wall St Screener.
- For investors who want quality at a fair price, scan a 200 high quality undervalued stocks that combine stronger fundamentals with prices that may not fully reflect their underlying strength.
- If resilience matters more than excitement right now, filter for 220 resilient stocks with low risk scores that pair steadier financial profiles with more measured risk scores.
- When you want to move beyond well known tickers, cast a wider net across 605 high quality undiscovered gems that still show robust balance sheets and earnings power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com