


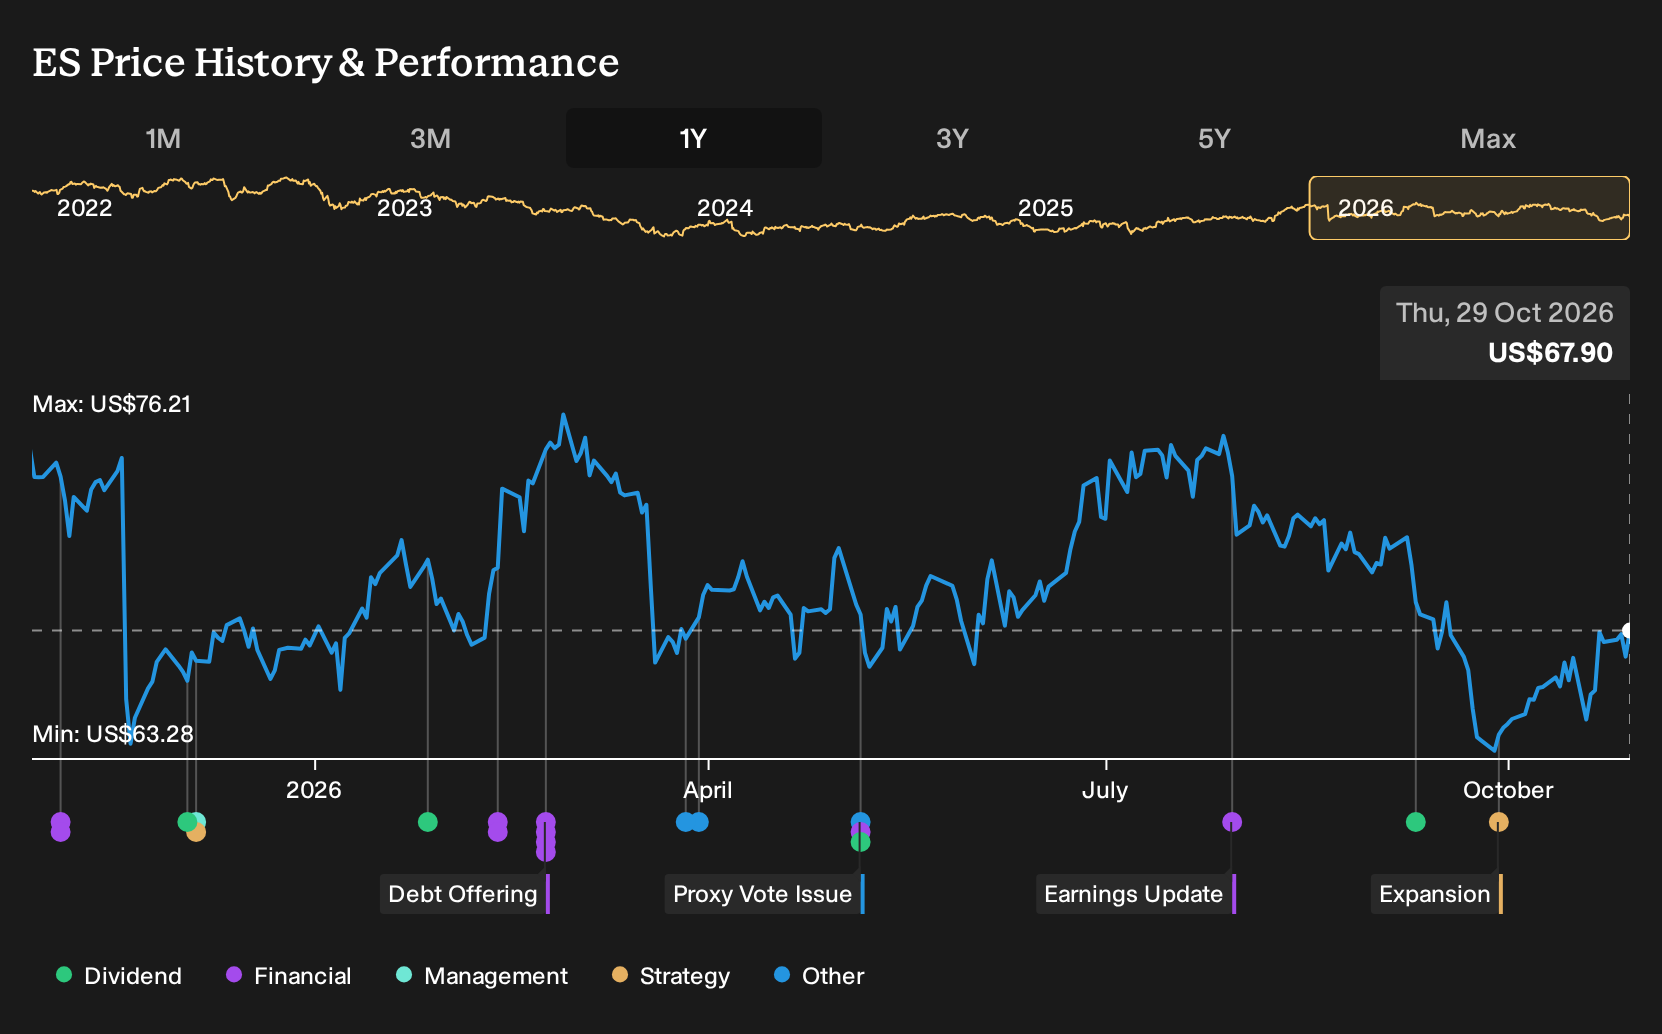
- Eversource Energy is set to report quarterly results for the period ended September 2026, with analysts projecting lower earnings compared with the prior year even though revenue is expected to be higher.
- The combination of anticipated earnings pressure and a negative Earnings ESP alongside a Zacks Rank of #4 signals concern around near term profitability and cost recovery execution.
- Next, the focus will be on how Eversource Energy's long term regulated utility narrative aligns with softer near term earnings expectations.
Pressure test your thesis on Eversource Energy by comparing it with a curated 30 resilient stocks with low risk scores that may be better positioned for steadier earnings and balance sheet resilience.
Eversource Energy Investment Narrative Recap
To own Eversource Energy, you need to believe the regulated utility model and US$26.5b capital plan through 2030 can translate into steady rate base expansion and support future earnings, even with regulatory friction. The current concern sits in the near term. Softer earnings expectations versus revenue highlight pressure on costs, allowed returns and timing of recovery.
Right now, the key near term catalyst is how regulators treat major filings such as the 2026 CL&P case and storm securitizations, because those decisions shape cash flow headroom. The biggest risk is that tighter outcomes on return on equity, refunds or unrecovered storm and project costs dilute that long term investment thesis.
There has not been a specific fresh announcement tied directly to this earnings preview, so the most relevant reference point is still the multi year capex and funding plan that management has laid out. That framework centers on grid modernization, advanced metering, new substations and support for over 2,500 MW of regional generation and storage.
For you, the link to the current earnings setup is straightforward. Execution on that plan, together with outcomes on CL&P rates and storm cost securitization, shapes whether Eversource Energy can absorb items like lower allowed transmission return on equity, interest coverage pressure and potential project cost overruns without eroding its long term regulated utility story.
Eversource Energy's current analyst framework implies revenue of US$15.4b and earnings of US$2.1b by 2029, based on 3.3% yearly revenue growth and an earnings increase of about US$700m from US$1.4b today.
Uncover why Eversource Energy's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view on Eversource Energy leans heavily on tighter regulation as the key risk. The most bearish analysts were pencilling in revenue of about US$14.8b and earnings of roughly US$2.1b by 2029 before this earnings news. That more cautious stance shows how far opinions can differ. It therefore makes sense to explore several forecasts and stress test your own.
Explore 3 other Eversource Energy fair value estimates, including one that suggests as much as 27% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eversource Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eversource Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eversource Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Eversource Energy?
If the Eversource Energy setup has sharpened your view on risk, regulation and earnings quality, it can be useful to line that thinking up against a broader watchlist. The Simply Wall St Screener lets you quickly compare different types of businesses through a fundamentals lens so you can see where Eversource really fits in your portfolio.
- If capital protection and smoother volatility matter most to you, start with a curated group of 30 resilient stocks with low risk scores that screen well on resilience and balance sheet strength.
- If value is your focus and you prefer paying less for quality fundamentals, hunt through a tailored pool of 30 high quality undervalued stocks that combine solid cash generation with more modest pricing.
- If reliable income streams appeal to you, concentrate on the income heavy universe of 7 dividend fortresses that clear a 5% yield hurdle while still aiming to keep payouts supported by underlying cash flow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com