


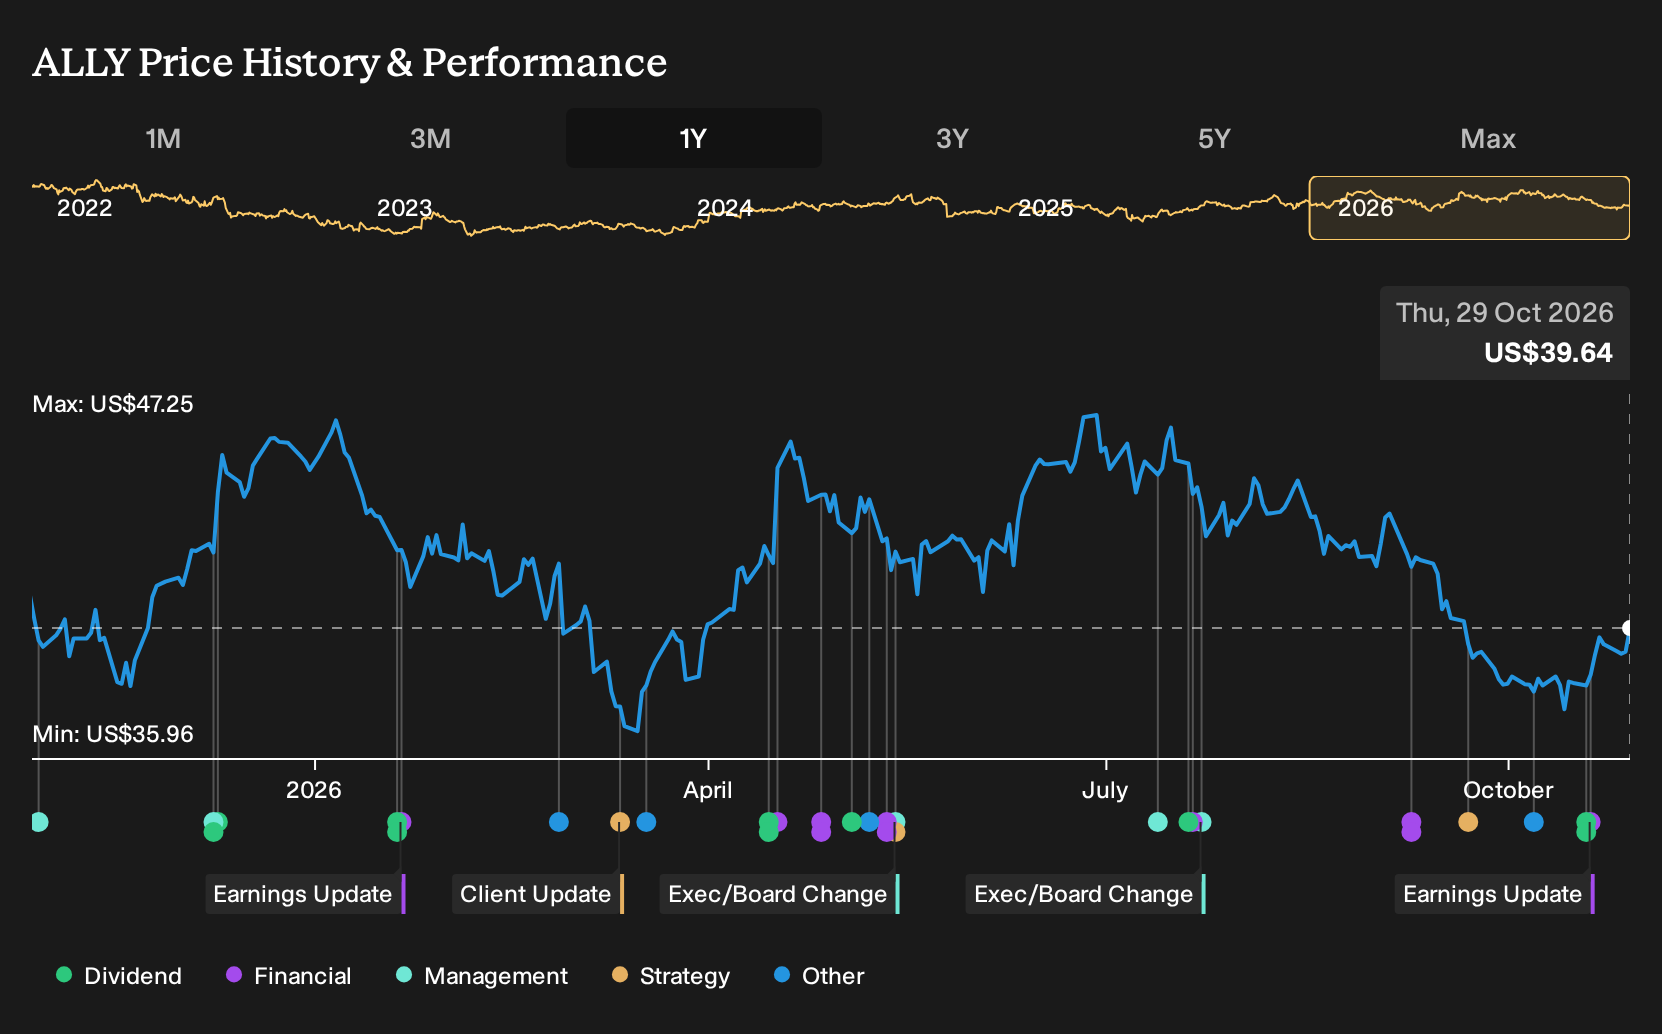
- Ally Financial reported third quarter 2026 net income of US$433 million compared with US$398 million a year earlier and raised its common dividend to US$0.35 per share, with additional preferred dividends declared, all of which were announced in October 2026.
- The combination of higher quarterly earnings, a 17% dividend increase and ongoing buybacks that retired 3.72% of shares reflects management focusing on capital returns alongside core digital banking and auto finance operations.
- We will now explore how Ally Financial's higher common dividend could shape the investment narrative that analysts had outlined before these results.
Scan how Ally Financial's latest earnings, dividend lift and buybacks compare with hand-picked peers by jumping across to our screener of 7 dividend fortresses
Ally Financial Investment Narrative Recap
To own Ally Financial, you need to believe its digital bank and auto finance engine can keep generating solid returns while credit losses, deposit costs and auto residual hits stay within a manageable band. The third quarter result, with US$433 million of net income, broadly supports that thesis without changing it in a dramatic way.
The near term swing factor still sits in auto credit performance and residuals, especially with lease losses linked to Stellantis recalls running through 2026. Competitive pressure in auto lending and from fintechs remains the biggest operational risk, and the latest earnings do not remove that, although they suggest the current playbook is holding up.
The 17% dividend increase to US$0.35 per common share is the announcement that matters most for this story. For an investor, that higher cash payout is a concrete signal that Ally Financial currently has room to share earnings with shareholders while still funding loan growth and maintaining regulatory capital.
It also raises the bar for future execution. To keep that dividend comfortable, the business needs to keep earning through auto cycle bumps, deposit pricing pressure and recall related residual hits. You are essentially judging whether today’s earnings power, plus the buybacks already completed, can offset those risks and keep the capital return path intact.
What Ally Financial's Analyst Forecasts Are Pricing In
Ally Financial's narrative projects US$9.9b revenue and US$1.7b earnings by 2029. This aligns with analyst assumptions of 7.4% yearly revenue growth and an earnings increase of about US$300 million from US$1.4b today.
Uncover how Ally Financial's fair value indicates a 20% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Ally Financial’s Corporate Finance unit as the swing factor. Before this dividend hike and buyback update, they were pencilling in revenue near US$10.7b and earnings around US$2.2b by 2029. Their view is more upbeat than consensus, and this fresh news could eventually shift either narrative.
Explore 4 other Ally Financial fair value estimates, including one that suggests as much as 41% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ally Financial research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Ally Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Ally Financial's overall financial health at a glance.
Looking For More Ideas Beyond Ally Financial?
Once you have a view on Ally Financial, it can help to compare that with other opportunities that fit different risk and income profiles using the Simply Wall St Screener.
- If you want income to do more of the heavy lifting in your portfolio, scan a curated set of higher yielding payers through 7 dividend fortresses.
- For investors who care most about strong finances and resilience, start with a list of solid balance sheet and fundamentals (23 results) to see which businesses keep their foundations tight.
- When you are hunting for future leaders before they are widely followed, focus your research on a 18 high quality undiscovered gems that already show quality traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com