


FTI Consulting (FCN) reset expectations on future profitability, cutting its full year 2026 EPS guidance while keeping revenue targets intact. The updated outlook followed record quarterly sales and an increase to adjusted earnings guidance.
That reset on 2026 earnings landed alongside powerful short term momentum in FTI Consulting, with the share price up 37.21% over the past month and 13.72% over 90 days, even though the 3 year total shareholder return is down 15.13% and the 5 year total shareholder return is 23.05%. This points to renewed enthusiasm after a softer period.
Scan other advisory and consulting stocks showing similar earnings momentum and guidance resets through our curated list of 18 high quality undiscovered gems to see how FTI Consulting compares on fundamentals.
After that kind of snapback and a lower 2026 EPS bar, the question for FTI Consulting now is simple: Does the risk‑reward at US$181.24 still favour new buyers once valuation enters the frame?
Most Popular Narrative: 17% Overvalued
Simply Wall St’s most followed narrative now pegs FTI Consulting’s fair value at $154.50, which sits below the latest close of $181.24 and frames the recent share price surge as running ahead of that model. That gap puts the spotlight on whether the revised 2026 EPS range and ongoing buybacks can justify paying a premium to the narrative view.
The consulting industry trend toward consolidation and pressure on weaker competitors intersects with FTI Consulting's low leverage balance sheet, enlarged US$1.5b revolving credit facility and ongoing share repurchases of hundreds of millions of dollars a year. Together, these factors create scope for continued capital returns and potential earnings per share growth even if headline revenue trends remain mixed.
See why 2 investors see FTI Consulting as 17% overvalued.
Result: Fair Value of $154.50 (OVERVALUED)
Still, the narrative can crack if Economic Consulting remains a drag on earnings, or if elevated legal and SG&A costs keep squeezing FTI Consulting’s profit pool.
Find out about the key risks to this FTI Consulting narrative.
Another View On FTI Consulting’s Value
The headline narrative says FTI Consulting looks 17% overvalued at $181.24, yet the SWS DCF model tells a very different story. On that cash flow view, FCN is trading below an estimated future cash flow value of $365.95, which frames the recent rally as potentially conservative rather than stretched. Which storyline fits your expectations for this business more closely?
For readers who want to see how that cash flow estimate is built and stress test the underlying inputs, Look into how the SWS DCF model arrives at its fair value.
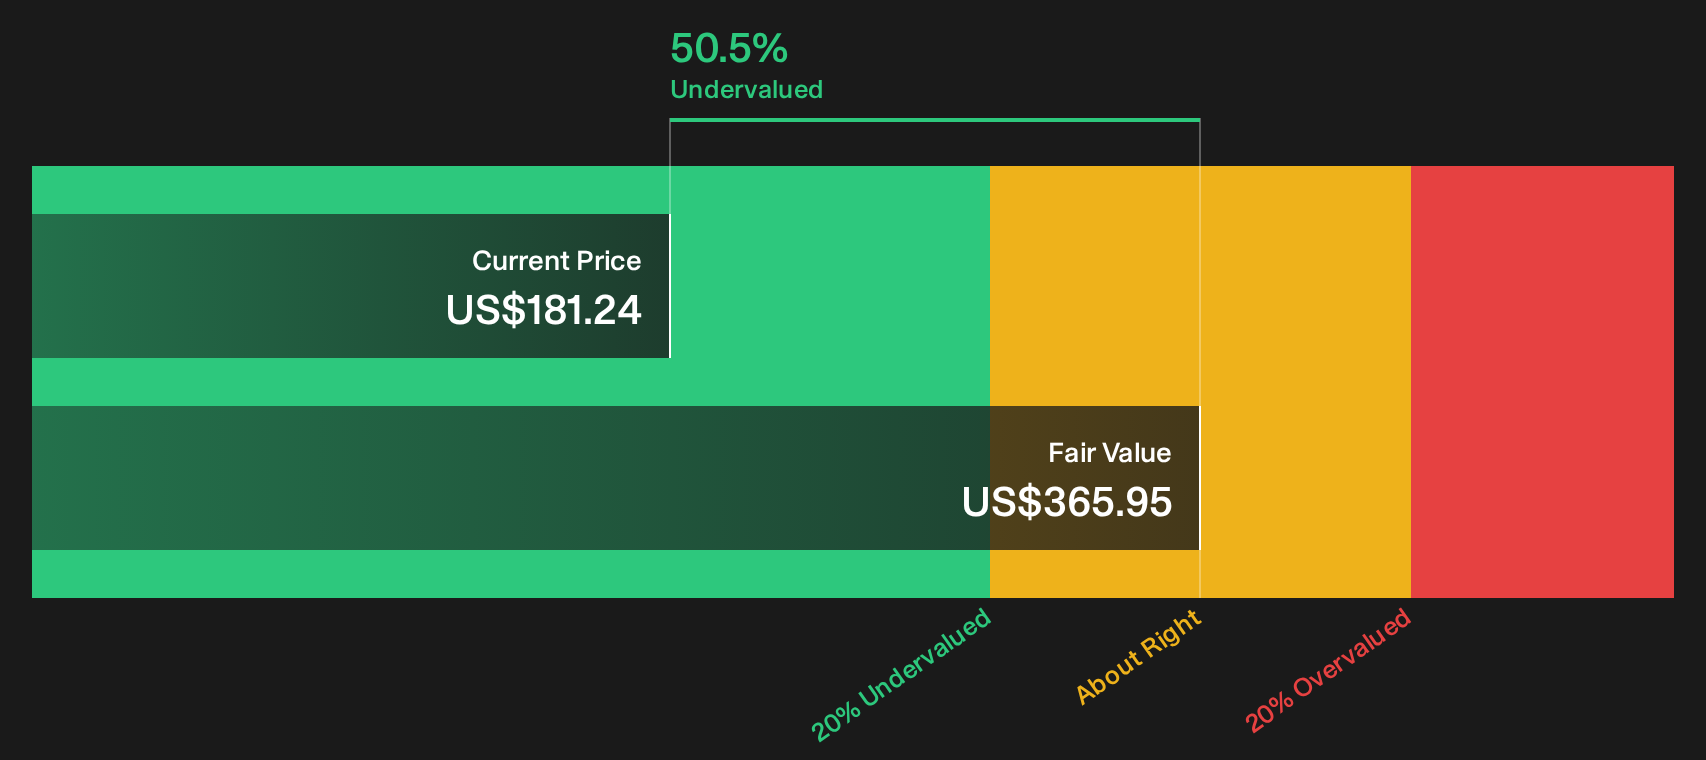
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FTI Consulting for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on FTI Consulting’s value and outlook can feel messy, so move fast, review the underlying data yourself and weigh the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond FTI Consulting?
If FTI Consulting has sharpened your focus on quality, do not stop here. Broaden your watchlist with other focused ideas that match your own risk and return preferences.
- Target resilient cash generators by scanning a curated set of companies that combine quality with attractive pricing through the 30 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies with stronger yields and payout profiles using the 7 dividend fortresses.
- Dial down potential shocks by filtering for businesses with more robust financial positions through the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com