


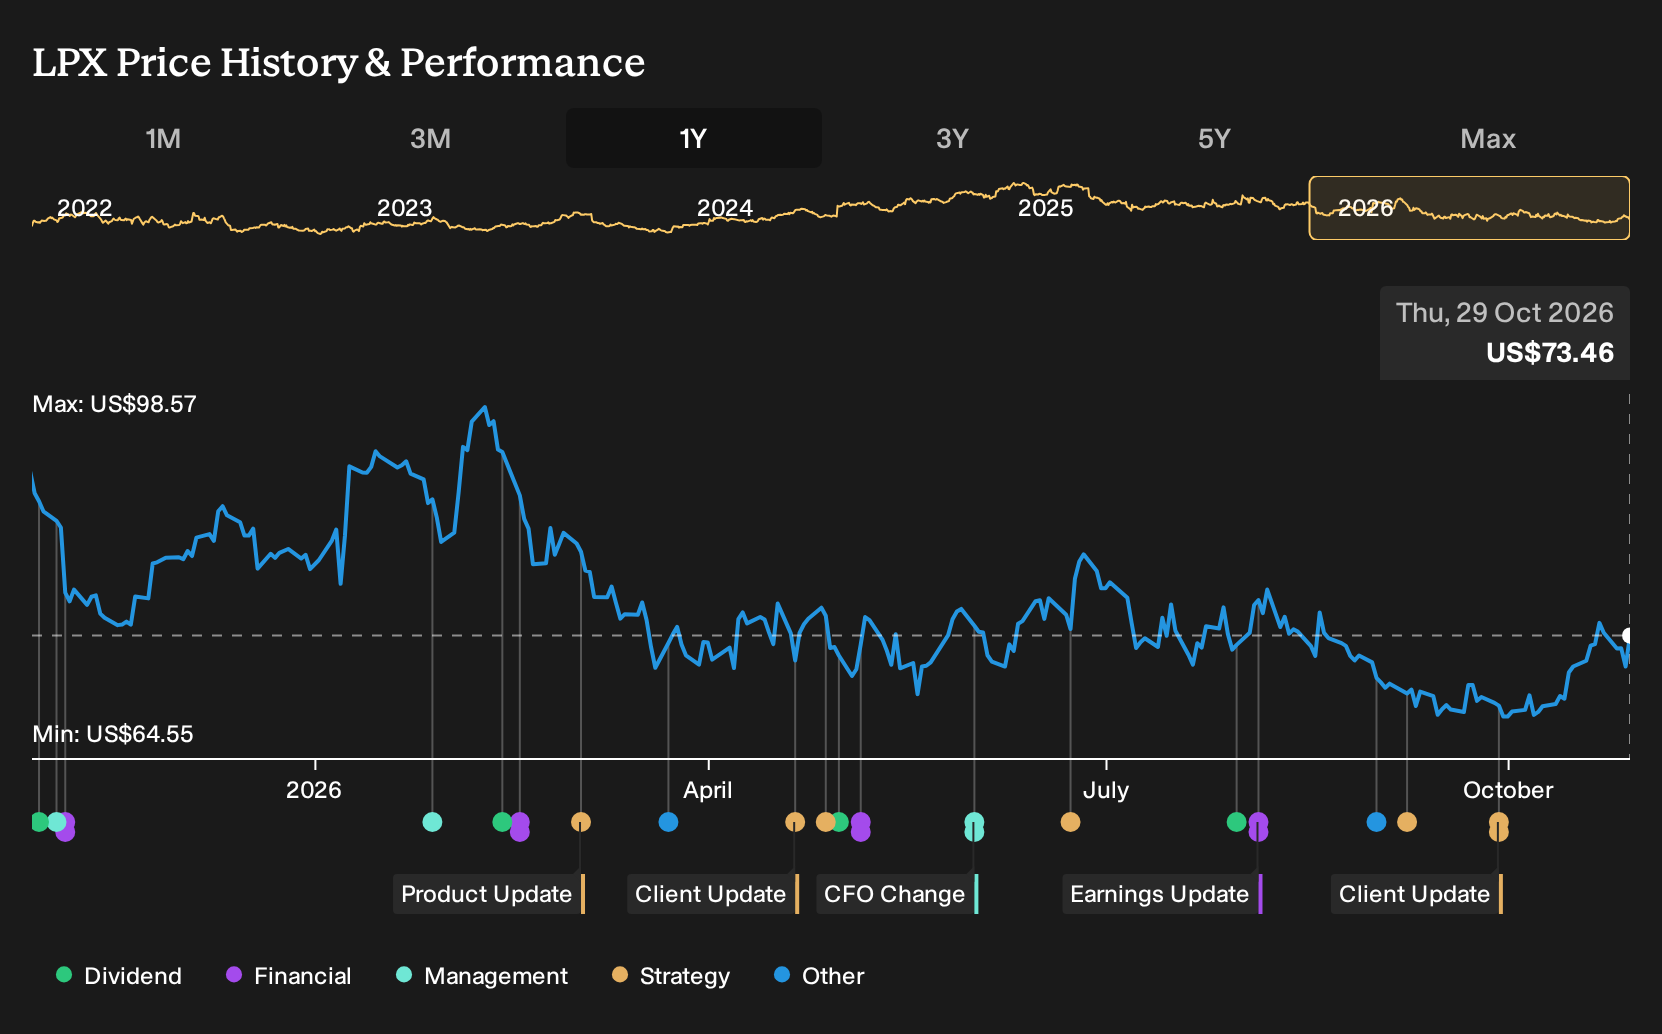
- Louisiana-Pacific is set to report Q3 results on November 3, with consensus pointing to earnings per share of $0.21 on revenue of $674.25 million. Analysts expect these figures to be modestly higher than a year earlier.
- The more striking data point is the 24.4% cut to that earnings estimate over the past month, which highlights near term pressure on profitability even as projected sales edge up.
- The focus now shifts to how Louisiana-Pacific's investment narrative compares with these sharply reduced near term earnings expectations.
Compare Louisiana-Pacific's reset earnings expectations with other construction and building materials stocks by scanning our hand picked list of solid balance sheet and fundamentals (23 results) for potential ideas with sturdier fundamentals.
Louisiana-Pacific Investment Narrative Recap
To own Louisiana-Pacific, you need to believe the siding transition remains intact while the more volatile OSB business stays manageable. The near term story still turns on demand for LP SmartSide and ExpertFinish products, mill efficiency projects, and relationships with large builders and remodel channels.
The sharp reset in quarterly earnings expectations points to pressure on margins rather than a change in direction for the siding mix shift. The biggest swing factor right now is housing and repair activity feeding siding volumes. The key risk is OSB pricing staying weak enough that losses keep dragging on already thin 2.2% net margins.
With Q3 earnings yet to be released and no major fresh corporate announcements tied directly to this print, the most relevant context remains Louisiana-Pacific’s recent capital spending tilt toward siding. Management has earmarked roughly three quarters of 2026 capex for siding growth, while trimming OSB and some maintenance projects by about US$70 million.
That choice puts the spotlight on execution at plants supporting SmartSide and ExpertFinish capacity. Any commentary on the upcoming call around ramp up progress, mill efficiency, and how those projects are tracking against demand will matter more than a single quarter’s US$0.21 EPS line. For you, the question is how that capital plan balances against OSB, input cost, and dividend coverage risks.
Louisiana-Pacific's narrative projects US$3.0b revenue and US$422.6 million earnings by 2029. This assumes 6.9% yearly revenue growth and an earnings increase of about US$368.6 million from US$54.0 million today.
Uncover why Louisiana-Pacific's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The alternate view on Louisiana-Pacific leans heavily on siding demand as a catalyst. The most optimistic analysts were penciling in revenue reaching about US$3.3b and earnings of roughly US$464.8 million by 2029 before this Q3 reset, which is well above the US$3.0b and US$422.6 million consensus path. That spread shows how far opinions can differ. The new earnings cut could shift those narratives, so treat it as a cue to compare bullish and baseline cases for yourself.
Explore 2 other Louisiana-Pacific fair value estimates, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your independent analysis.
- A great starting point for your Louisiana-Pacific research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Louisiana-Pacific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Louisiana-Pacific's overall financial health at a glance.
Looking For More Ideas Beyond Louisiana-Pacific?
If you want to put Louisiana-Pacific in context, it helps to line it up against other companies with different balance sheet strength, growth profiles, and income characteristics. The Simply Wall St Screener can surface a wide mix of opportunities so you can test your own thesis rather than relying only on consensus views.
- For potential value opportunities with solid fundamentals, review a 30 high quality undervalued stocks that combine financial quality with attractive pricing signals.
- If capital preservation matters most to you, filter for steadier profiles using a 30 resilient stocks with low risk scores that focus on resilient balance sheets and lower overall risk scores.
- When you want ideas that the market may be overlooking, scan a 18 high quality undiscovered gems that pair strong underlying metrics with relatively low investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com