


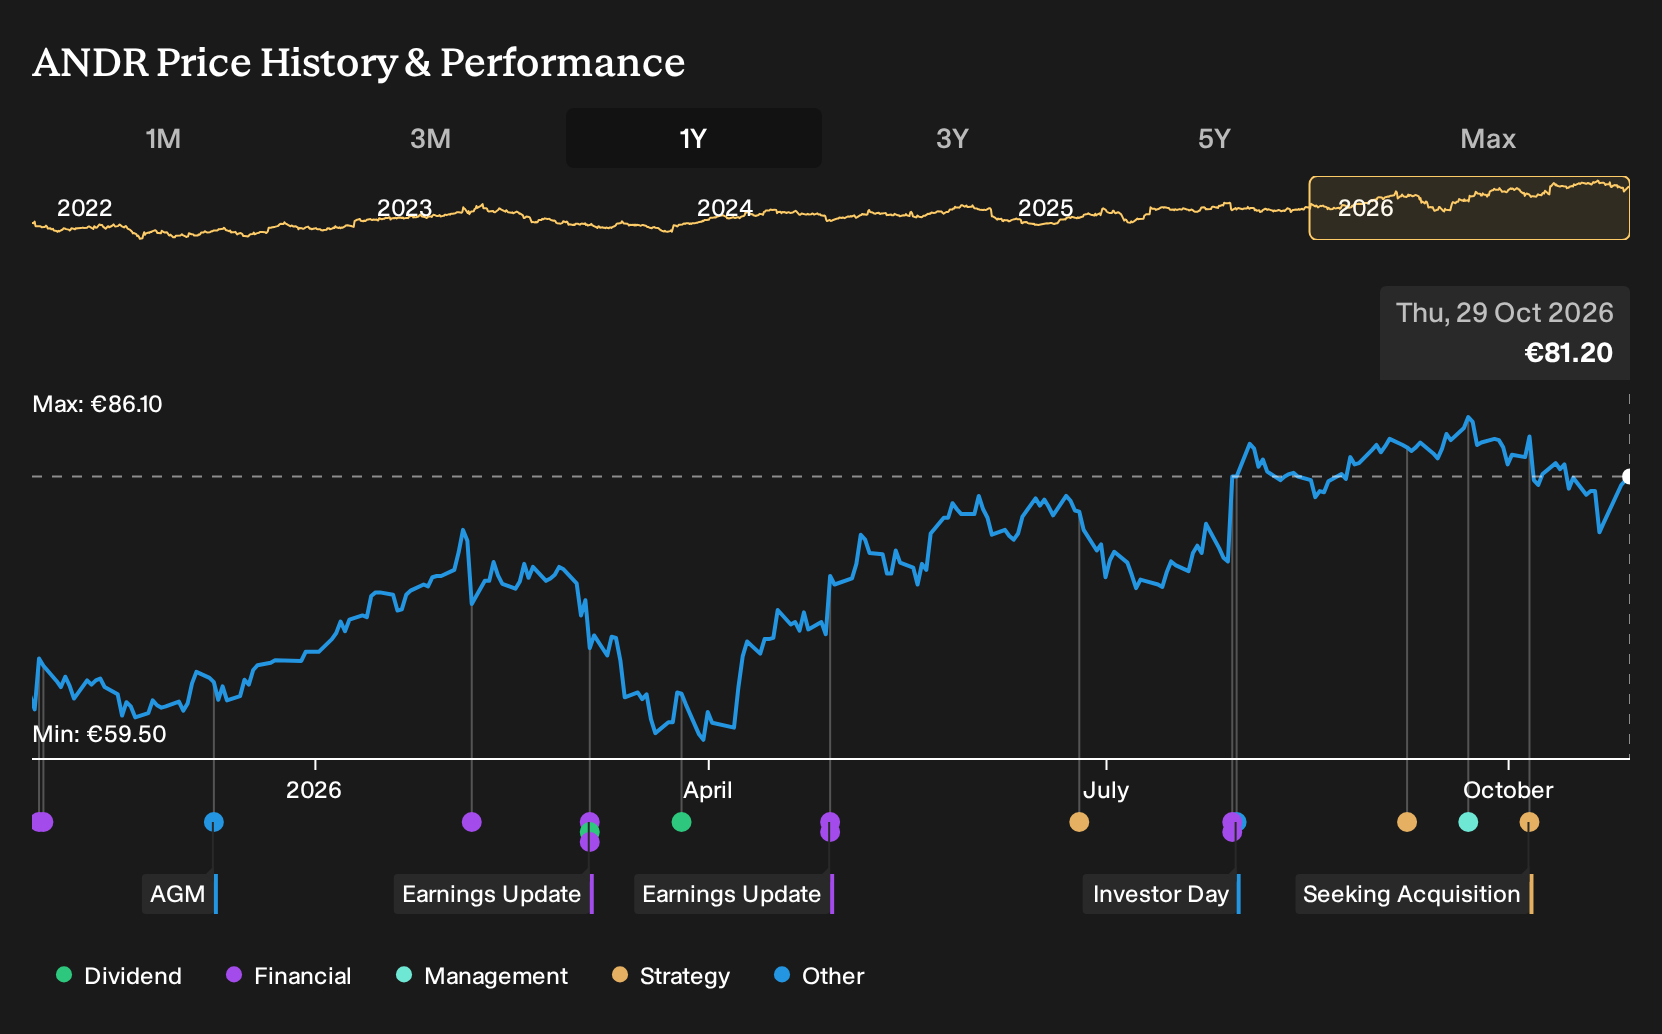
If you only glanced at headlines, the eye catching item was Andritz starting work on Austria's largest green hydrogen plant: a 12.5 MW solar powered electrolyzer meant to turn surplus electricity into seasonal storage. Investors who held Andritz over the past year are up 28.2%, including dividends. If you were deciding back on 29 October 2025, what would you have needed to believe about hydropower, services and legacy pulp exposure to buy into that story?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The move put Andritz in the middle of this trade. Scan 43 power grid technology and infrastructure stocks for other companies exposed to it.
The Two Andritz Stories Investors Had To Weigh
The shares cost €62 at the start of the period, so any investor looking at Andritz had to decide which of two very different stories felt more plausible.
The bullish narrative put fair value at €70.56. That view leaned on strong order intake, a record €10.4b backlog and a higher 44% service revenue mix that was expected to support resilience as hydropower and decarbonization projects moved forward.
The bearish narrative anchored fair value at €43. It focused on the risk that automation and sustainability pressures could leave legacy hydropower and pulp assets exposed, with compliance costs, restructuring and tougher competition squeezing margins over time.
What The Evidence Did To The Andritz Argument
The headline event for Andritz was breaking ground on Austria's largest green hydrogen plant, which backed the bullish idea that hydropower and decarbonization work could keep the project pipeline full. Q2 2026 results showed revenue at €2,050.7m and net income at €109m, with net margin slipping slightly to 5.3%. The evidence cut both ways.
The hinge assumption was that services and energy transition projects would offset pressure in legacy areas. For a different stock, you would test that by tracking the service share of sales, the backlog in newer segments, and any margin change in relation to that mix.
What Andritz's Run Still Leaves You Paying For
With Andritz now at €81.2, the selected Narrative’s Fair Value sits above the current price and leans on cash generation, hydropower heavy orders and a higher service mix as key pillars of the investment case.
The view is that today’s share price still does not fully reflect the cash flow and returns tied to long-duration, service-rich projects.
"Hydropower now accounting for about half of the €12.6 billion to €12.9 billion order backlog, combined with broad demand for grid stability solutions and turbo generators for data centers, means a larger share of Andritz revenue may come from longer-duration projects that can support steadier earnings and potentially more efficient cost absorption over time."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Beyond Andritz
Once you have mapped Andritz to hydropower and grid work, another link appears. You can ask what keeps all that digital load running securely.
New data centers chasing AI capacity create intense heat and power challenges. That is a very different infrastructure problem than dams and turbines.
One specialist business designs power systems and thermal hardware that keep these facilities online. It also supports the equipment through lifecycle and monitoring services.
As AI projects scale, the need for robust backbone systems may evolve. The more interesting angle could sit just one step beyond Andritz.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 66% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com