


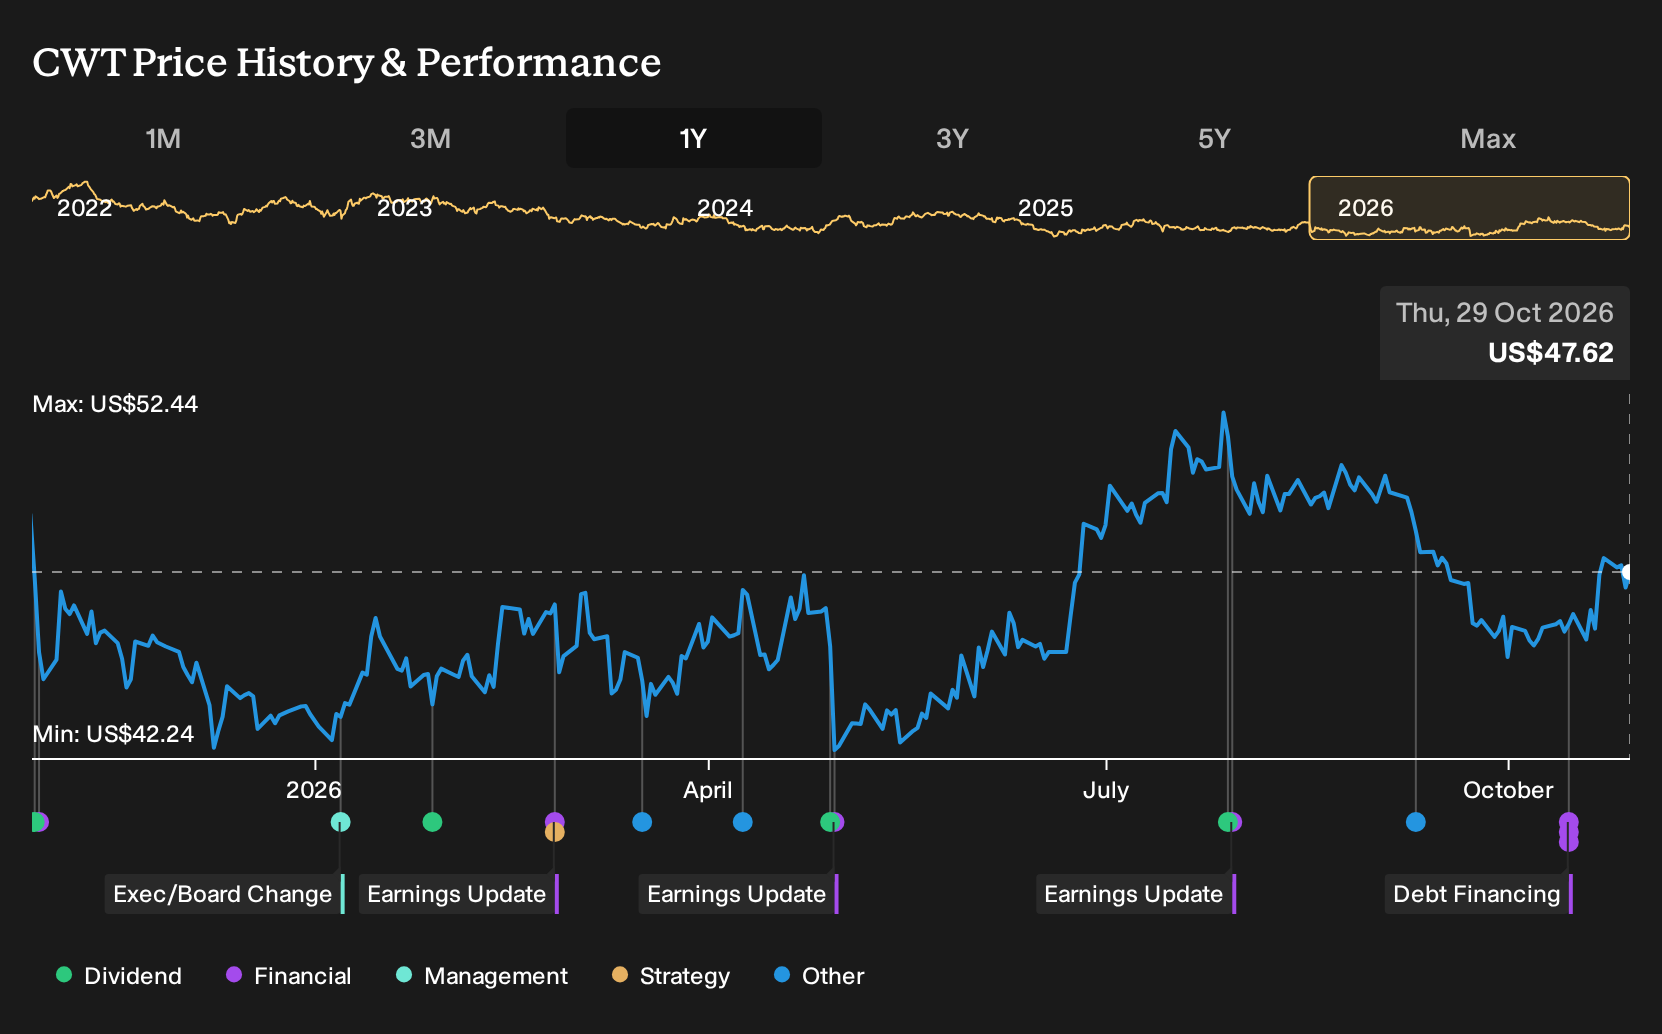
- California Water Service Group reported stronger third quarter 2026 results, with higher net income of $65.4 million, greater revenue supported by authorized rate increases and customer additions, and confirmation of its 327th consecutive quarterly dividend at $0.335 per share payable in November 2026.
- Beyond the dividend streak, California Water Service Group is pressing ahead with infrastructure spending of $425 million over nine months and progressing water system acquisitions in Oregon and Nevada, which together influence how investors might think about its long term earnings capacity and regulatory risk profile.
- We will now look at how California Water Service Group's stronger third quarter earnings relate to the broader investment narrative around its expansion plans.
Scan beyond California Water Service Group and see how other regulated utilities with long dividend track records and heavy capital programs stack up in the 30 resilient stocks with low risk scores.
California Water Service Group Investment Narrative Recap
Owning California Water Service Group means believing that heavy water infrastructure spending, multi state expansion and PFAS recovery can translate into steadier earnings over time. The third quarter showed net income of US$65.4 million supported by higher authorized rates and customer additions, which helps the near term story. The key short term swing factor remains regulatory treatment of its growing capital and PFAS programs across jurisdictions.
The biggest operational risk is that rising depreciation, interest costs and taxes repeat the pressure seen in early 2026 and blunt benefits from the roughly US$425 million invested over nine months. If regulators prove less supportive in newer markets like Nevada and Oregon, the recent earnings strength and expansion narrative may matter less than rate decisions.
The 327th consecutive quarterly dividend at US$0.335 per share, tied to an expected annual payout of US$1.34 in 2026, is the clearest recent signal about California Water Service Group’s confidence in its cash profile. A 59 year streak of annual dividend raises sets a high bar for management to keep funding both the distribution and a sizeable capital plan.
For you as an investor, the catalyst is whether earnings and cash generation from rate base growth, PFAS cost recovery and new systems in Oregon and Nevada comfortably cover that dividend and interest costs. Current data notes that free cash flow coverage of the payout and interest coverage by earnings are pressure points, so execution on infrastructure returns and regulatory recovery remains central to this dividend narrative.
California Water Service Group is currently modeled on analysts’ assumptions that revenue increases by 6.9% per year and that earnings rise from US$133.2 million today to US$200.4 million by 2029, implying about a US$67 million uplift in profit alongside forecast 2029 revenue of US$1.3b.
Uncover why California Water Service Group's fair value indicates a 13% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for California Water Service Group from three members of the Simply Wall St Community cluster between US$41 and US$53.75 per share, which already shows how far opinions can stretch. Those views sit alongside bigger questions around regulatory treatment of PFAS recovery and new state operations. Use these contrasting takes as a prompt to test your own assumptions rather than rely on any single market view.
Explore 2 other California Water Service Group fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Some investors believe that extraordinary investment returns rarely come from following the herd, so they may choose to go with their instincts.
- A great starting point for your California Water Service Group research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for California Water Service Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate California Water Service Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond California Water Service Group?
Once you have a view on California Water Service Group, it can help to cross check your thinking against other companies with different income profiles, balance sheets and dividend habits. That comparison often sharpens your sense of risk and return far more than staring at a single ticker in isolation.
- For investors who care most about protecting capital while still staying in equities, start with a curated set of resilient businesses through the 30 resilient stocks with low risk scores.
- If income reliability matters to you, scan a hand picked group of higher yielding payers with stronger dividend profiles via the 7 dividend fortresses.
- When you want growth potential backed by solid accounts instead of hype, focus on quality companies with attractive valuations using the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com