


Fresh quarterly numbers pushed Monolithic Power Systems (MPWR) into focus, as the company paired stronger than expected third quarter results with upbeat fourth quarter revenue guidance and visible momentum across enterprise data and automotive customers.
Despite the upbeat guidance and fresh leadership appointments, Monolithic Power Systems’ share price has had a choppy few months, with the 30 day return down 11.6% and the 90 day move lower by 15.9%. At the same time, the year to date share price return is up 28.0%, and the three year total shareholder return has climbed to about 160%, pointing to longer term momentum that recent volatility has not erased.
Capitalize on Monolithic Power Systems’ strong quarter by scanning a hand picked set of peers benefiting from similar demand trends using the 54 AI infrastructure stocks.After a record quarter and a pullback that leaves Monolithic Power Systems trading well below both analyst targets and some fair value models, the key question is straightforward: Is the gap still justified or already overdone?
Most Popular Narrative: 33% Undervalued
Against Monolithic Power Systems’ last close of $1,198.81, the most widely followed narrative anchors fair value at about $1,799.80. This incorporates ambitious growth, margin and capital return assumptions that investors need to weigh carefully.
The current valuation and bullish coverage imply that the share price already reflects strong growth, high margins and effective capital returns such as buybacks and dividends, so the stock is priced for continued successful delivery on this growth plan.
See why 85 investors see Monolithic Power Systems as 33% undervalued.
Result: Fair Value of $1,799.80 (UNDERVALUED)
Still, the bullish Monolithic Power Systems narrative runs into real friction if extended capacity is underused or if ongoing investigations and customer order disputes continue to weigh on sentiment.
Find out about the key risks to this Monolithic Power Systems narrative.
Another View: Monolithic Power Systems On Earnings Multiples
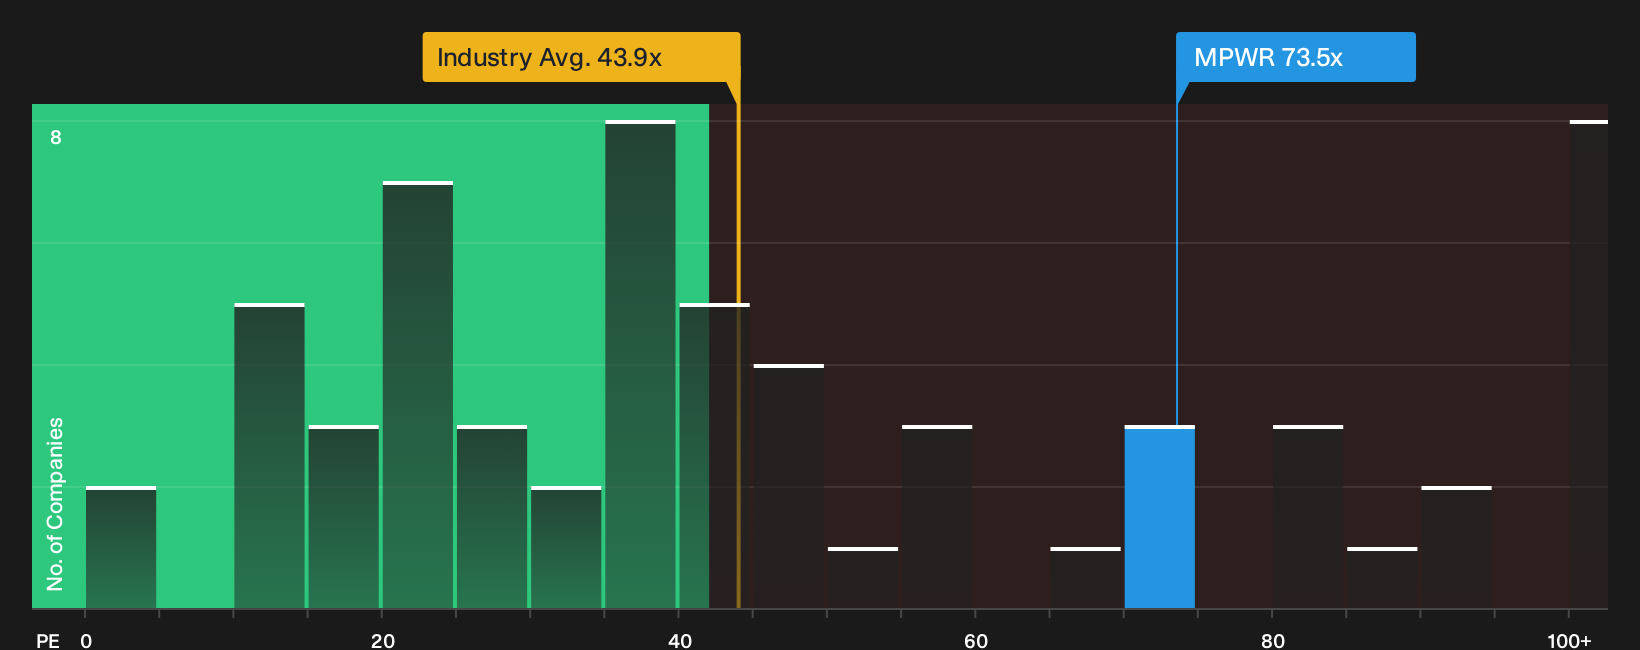
The fair value story built around analyst forecasts says Monolithic Power Systems looks undervalued. A quick reality check on the current P/E tells a different story. The shares trade on about 73.5x earnings compared with 43.9x for the US semiconductor group and a fair ratio closer to 35.2x, which points to meaningful valuation risk if enthusiasm cools.
If the gap between the current multiple, the sector, and that fair ratio closes even part of the way, investors would be relying much more heavily on future earnings delivery than the headline discount to target price suggests. The question is which signal to rely on more right now.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big swings in the Monolithic Power Systems story can feel exciting or unsettling, yet the real edge comes from testing the facts yourself and moving before sentiment settles. Weigh both sides of the debate and focus on the balance of 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Monolithic Power Systems?
If you only focus on Monolithic Power Systems, you risk missing other opportunities that could fit your goals even better, so widen your net using the Simply Wall St Screener.
- Target potential mispricing by scanning a curated set of quality opportunities with the 30 high quality undervalued stocks that match strong fundamentals with appealing valuations.
- Strengthen portfolio resilience by focusing on companies with healthier finances through a dedicated list of solid balance sheet and fundamentals (23 results) tailored to balance sheet quality.
- Get ahead of the crowd by filtering for lesser known quality names using the 18 high quality undiscovered gems that may not yet be on most investors’ radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com