


Key Points
The aerospace company has seen a huge pullback in its valuation.
That's partly driven by broader trends impacting space and defense stocks.
But the business's expanding losses have also factored into the pullback.
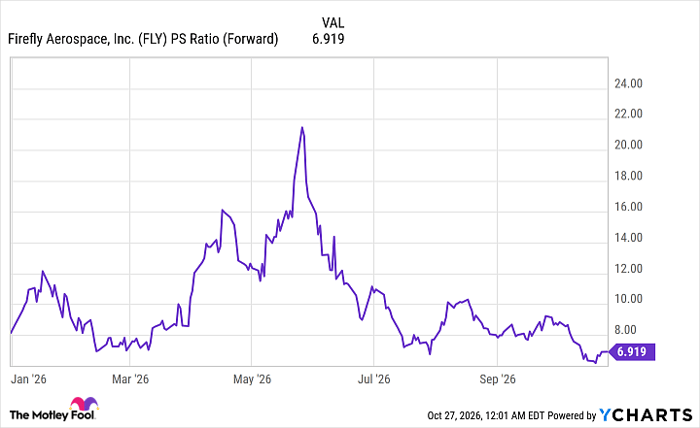
Firefly Aerospace (NASDAQ: FLY) stock has taken investors on a wild ride this year. The company's share price rocketed to its 52-week high in May, but it's seen dramatic valuation drawdowns in subsequent trading. The company's share price is now down roughly 26% across 2026's trading and 70% from its one-year high.
The big sell-offs have occurred despite some big wins for the business, including a successful Moon landing, winning a Pentagon contract, and securing a partnership with defense and aerospace giant Lockheed Martin. So why has the stock been getting crushed?
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Image source: Getty Images.
In order to contextualize why Firefly stock has struggled so much since hitting a peak in May, it's important to look at some trends that have been shaping the space tech and next-gen defense categories.
While the broader market has generally continued to march higher this year, gains have largely been propelled by companies with substantial exposure to the artificial intelligence (AI) market. Defense tech plays were hot early in the year, but momentum faded and many are now down big across 2026's trading.
A corresponding dynamic has played out with space stocks. Companies in the category saw massive valuation run-ups in the lead-up to Space Exploration Technologies' initial public offering, but space stock valuations have generally been under pressure following SpaceX's public debut. Notably, SpaceX has been reframing itself as an artificial intelligence company -- and its AI businesses now generate more revenue than its combined space ventures.
FLY PS Ratio (Forward) data by YCharts
Along with the waning hype cycle and investor industry rotation, concerns about Firefly's expanding losses and financing needs have also factored into the pullback. The company is now valued at roughly 6.9 times expected forward sales.
The business posted an operating loss of roughly $190.9 million across the first half of the year -- expanding from a loss of $112.9 million in the prior-year period. Firefly stock may still be able to bounce back and deliver strong long-term performance, but shifts in broader market dynamics and substantial new contract wins and partnerships may be needed to reverse recent valuation momentum.
Keith Noonan has no position in any of the stocks mentioned. The Motley Fool has positions in and recommends Firefly Aerospace and Lockheed Martin. The Motley Fool has a disclosure policy.