


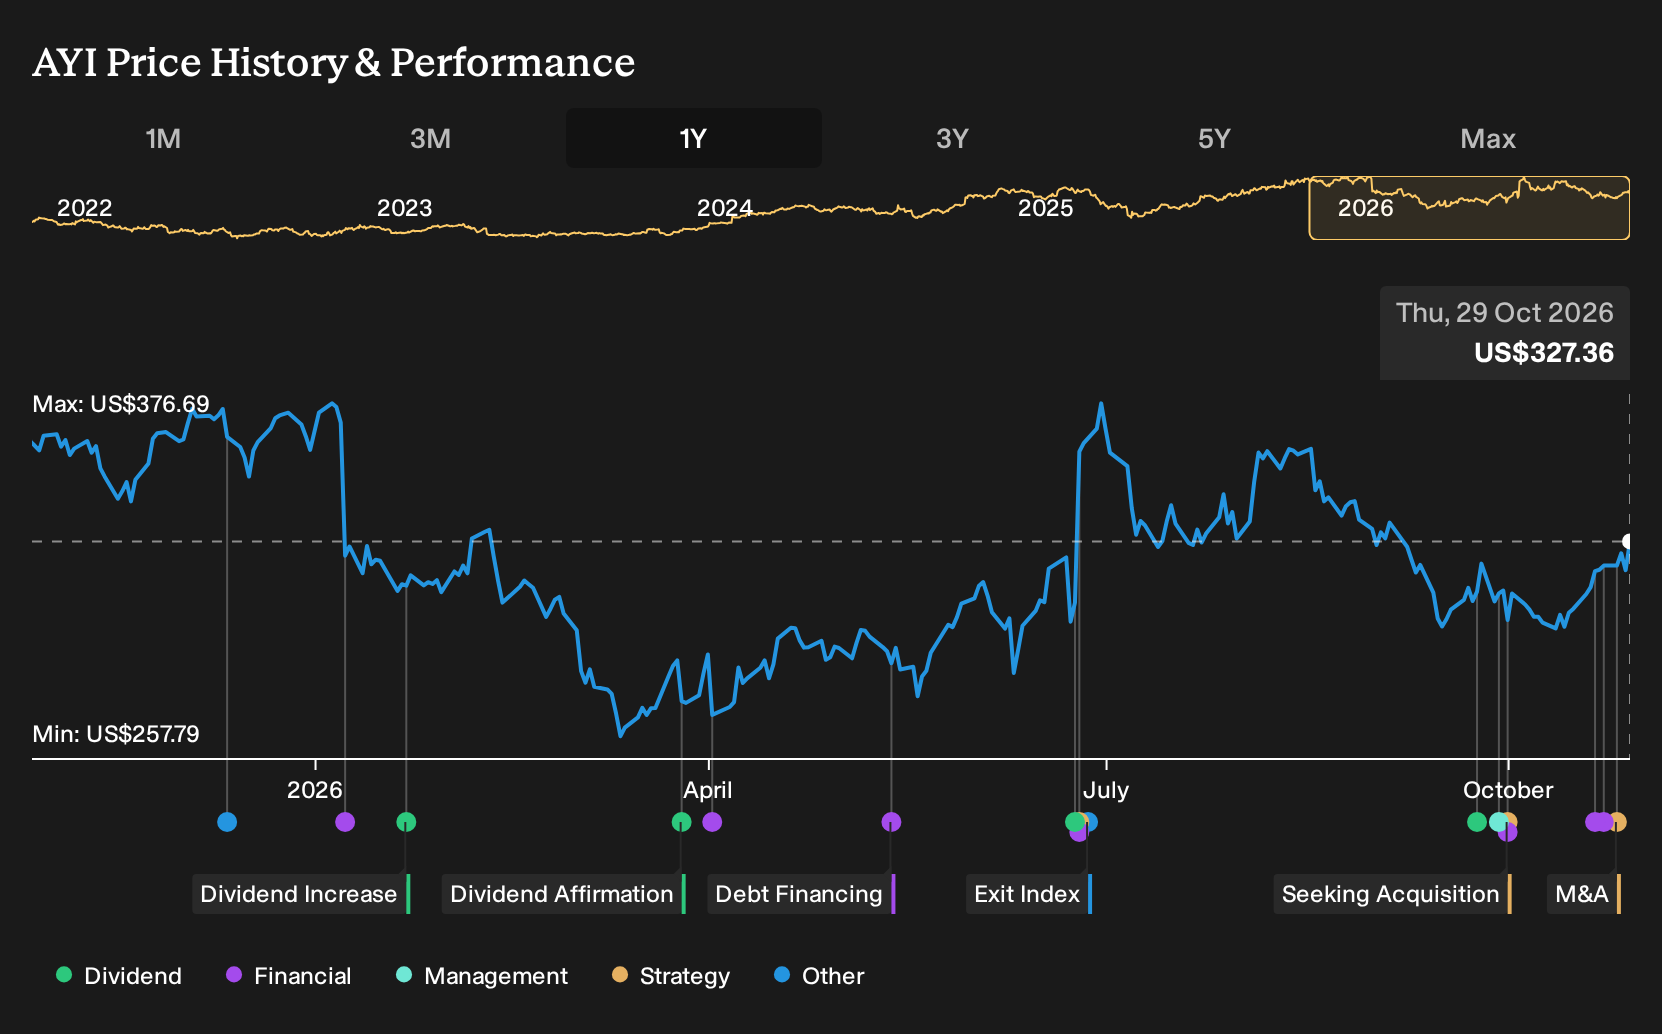
- Acuity Inc. recently filed two shelf registrations, including a US$155.51 million ESOP related offering for 500,000 common shares and a separate universal shelf covering equity and debt securities for future issuance.
- The combination of an ESOP focused raise and a broad omnibus shelf suggests Acuity is preparing flexible funding options while also using equity to deepen employee ownership.
- We will look at how Acuity's investment narrative intersects with the new universal shelf filing and what that might mean.
Acuity Investment Narrative Recap
To own Acuity, you need to be comfortable with a lighting business facing flat to down end markets while the higher margin Acuity Intelligent Spaces segment takes a larger share of revenue. The short term swing factor is how well AIS offsets softness and project delays in Acuity Brands Lighting as customers defer or stretch retrofit and construction timelines.
The biggest near term risk is that tariffs, uneven demand and higher component costs, including memory and labor, compress margins just as AIS faces about 200 basis points of forecast gross margin pressure in FY27. The new shelf registrations do not materially change that operational equation on their own.
The most relevant move is the omnibus or universal shelf registration that covers common and preferred stock, depositary shares and debt securities at both Acuity Inc. and Acuity Brands Lighting. This filing gives the business a ready structure to access capital if it chooses, which matters for execution in AIS and any larger projects or acquisitions.
For you as a shareholder, that flexibility intersects directly with the existing catalysts. AIS already represents about one quarter of sales with gross margins above 60%, and productivity work in ABL targets steady operating margin gains. Having a funding mechanism available can help management support these plans or absorb cost pressure, while you still need to watch valuation, insider selling and slower expected growth versus the broader US market.
How Acuity's Shelf Filings Connect To The Analyst Framework
Acuity's narrative projects US$5.2b revenue and US$664.1m earnings by 2029. This setup assumes 4.1% yearly revenue growth and an earnings increase of roughly US$133m from US$531.3m today.
Uncover how Acuity's fair value indicates a 15% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Acuity focuses on the risk that AIS integration drags on, with the most cautious analysts already assuming only 3.2% annual revenue growth and earnings of about US$654.5m by 2029. That is a more muted story than consensus. With these new shelf registrations in play, those forecasts could shift. Explore both narratives before deciding what fits your view.
Explore 2 other Acuity fair value estimates, including one that suggests as much as 24% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Acuity research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Acuity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Acuity's overall financial health at a glance.
Looking For More Ideas Beyond Acuity?
If Acuity has sharpened your thinking about where to put fresh capital, it can help to line it up against a wider field of potential opportunities. The Simply Wall St Screener lets you quickly filter for different traits, so you can find stocks that match the risk, income or quality profile you actually want.
- If you care most about paying a fair price for solid fundamentals and strong cash generation, start with value focused ideas by scanning 30 high quality undervalued stocks.
- If capital preservation and steadier business profiles matter more to you than chasing maximum upside, narrow the field to companies screened as having more resilient characteristics through 30 resilient stocks with low risk scores.
- If you want to focus on balance sheet strength and cleaner financial footing, concentrate on businesses with sturdier finances using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com