


- Scorpio Tankers reported Q3 2026 net income of US$224.32 million and basic EPS of US$4.91, with nine-month net income of US$828.12 million and basic EPS of US$17.92.
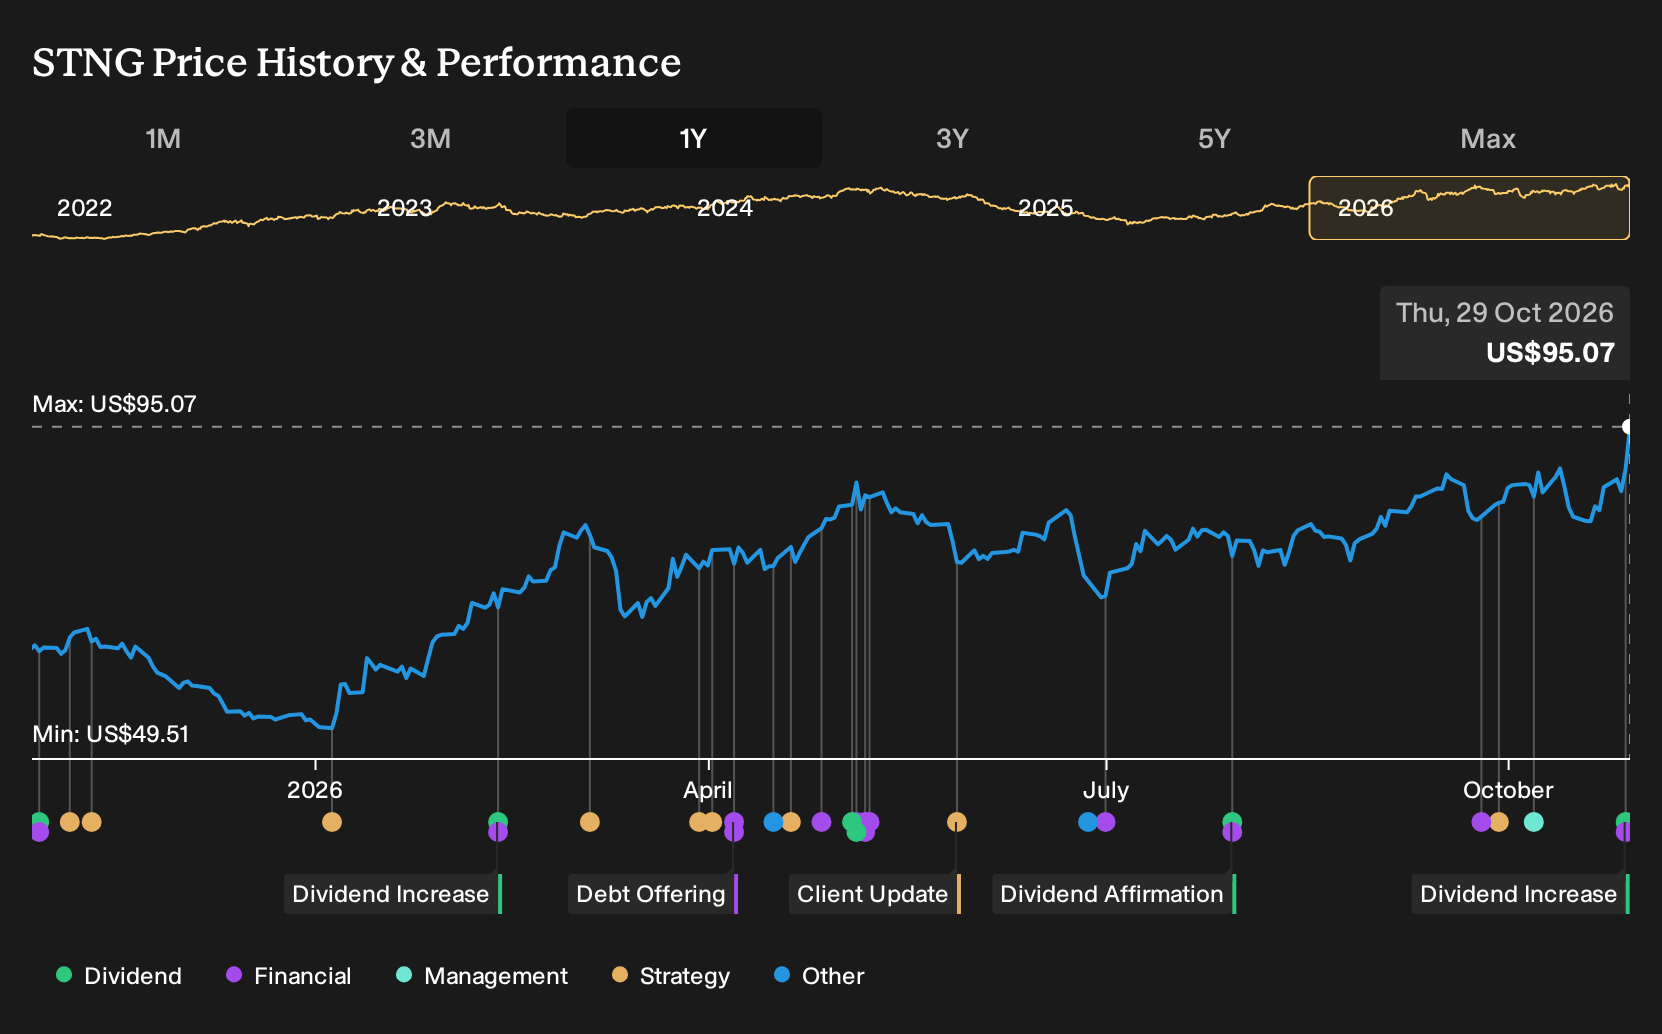
- The board lifted the quarterly dividend to US$0.75 per share and, with 51,078,851 shares outstanding, signaled confidence in cash generation and balance sheet strength.
- The focus now shifts to how Scorpio Tankers’ stronger-than-expected earnings might reshape its investment narrative for long-term holders.
Scan Scorpio Tankers’ results in context by lining them up against a curated 30 high quality undervalued stocks list that combines strong cash generation with balance sheets built to handle tougher shipping cycles.
Scorpio Tankers Investment Narrative Recap
To own Scorpio Tankers, you need to believe that tight product tanker supply and long haul refined product trade can stay supportive enough for its fleet to keep earning solid cash, even if day rates cool from current levels. The Q3 2026 beat and nine month net income of US$828.12 million reinforce that the operating setup is still working. The key short term swing factor remains freight rates. The biggest risk is that a weaker demand backdrop or new vessel ordering erodes utilization faster than the cost base can adjust.
The latest figures also highlight how reliant recent earnings have been on very strong conditions, along with large one off gains, at a time when analysts still model earnings and revenue to decline over the next few years. That gap between current profitability and expected normalization is important. It means this quarter does not remove the core risk that the cycle turns while environmental rules tighten and future capital spending needs rise. It just shows Scorpio Tankers is entering that phase from a very strong position.
The cleanest link between the earnings release and the broader thesis is the dividend change. Scorpio Tankers lifted the quarterly payout to US$0.75 per share, with 51,078,851 shares outstanding as of October 26, 2026, after posting basic EPS of US$4.91 in Q3 and US$17.92 over nine months. That distribution decision sits on top of what management has described previously as a net cash balance sheet and lower funding costs after refinancing. Together, these factors frame how much cash can be directed to shareholders versus fleet renewal when the market tightens or softens.
For you as a shareholder or prospective investor, that higher cash return immediately ties into catalysts and risks. On the one hand, a stronger near term yield can make it easier to hold Scorpio Tankers through future volatility, especially if multi year time charters keep adding revenue visibility. On the other, an enlarged dividend commits more of today’s earnings in a sector that remains cyclical, exposed to regulatory change, and faces the possibility that earnings and revenue move closer to the declines analysts currently forecast if refinery dislocation, voyage distances, or constrained fleet supply start to ease.
Scorpio Tankers' analyst narrative points to forecast revenue of US$731.1 million and projected earnings of US$205.1 million by 2029, based on an assumed 15.6% yearly decline in revenue and an earnings decrease of US$611.3 million from US$816.4 million today.
Uncover why Scorpio Tankers' fair value indicates an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One point the more bearish analysts focus on is future earnings pressure from higher environmental and technology costs for Scorpio Tankers. Before this Q3 surprise, some of them were sketching out 2029 earnings of about US$166.0 million on revenue near US$731.4 million. That is far below the consensus path and shows how sharply opinions can differ. Use this earnings beat and dividend move as a prompt to compare those pessimistic forecasts with your own view of the cycle, and then decide which story feels closer to how you think shipping markets might evolve.
Explore 2 other Scorpio Tankers fair value estimates, including one that suggests as much as 69% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Scorpio Tankers research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Scorpio Tankers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Scorpio Tankers' overall financial health at a glance.
Looking For More Ideas Beyond Scorpio Tankers?
Once you have a view on Scorpio Tankers, it helps to compare it with other opportunities that fit different parts of your portfolio. The Simply Wall St Screener can surface groups of businesses with specific traits so you can stress test your thesis, spread risk, and find alternatives that better match your return and income goals.
- If you want potential upside combined with disciplined financial profiles, review a carefully filtered 18 high quality undiscovered gems that may not yet be widely followed.
- For steadier profiles with an emphasis on resilience, scan a 30 resilient stocks with low risk scores that focuses on businesses with lower risk scores.
- Income focused investors can check a 7 dividend fortresses that highlights companies offering yields from sturdier payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com