


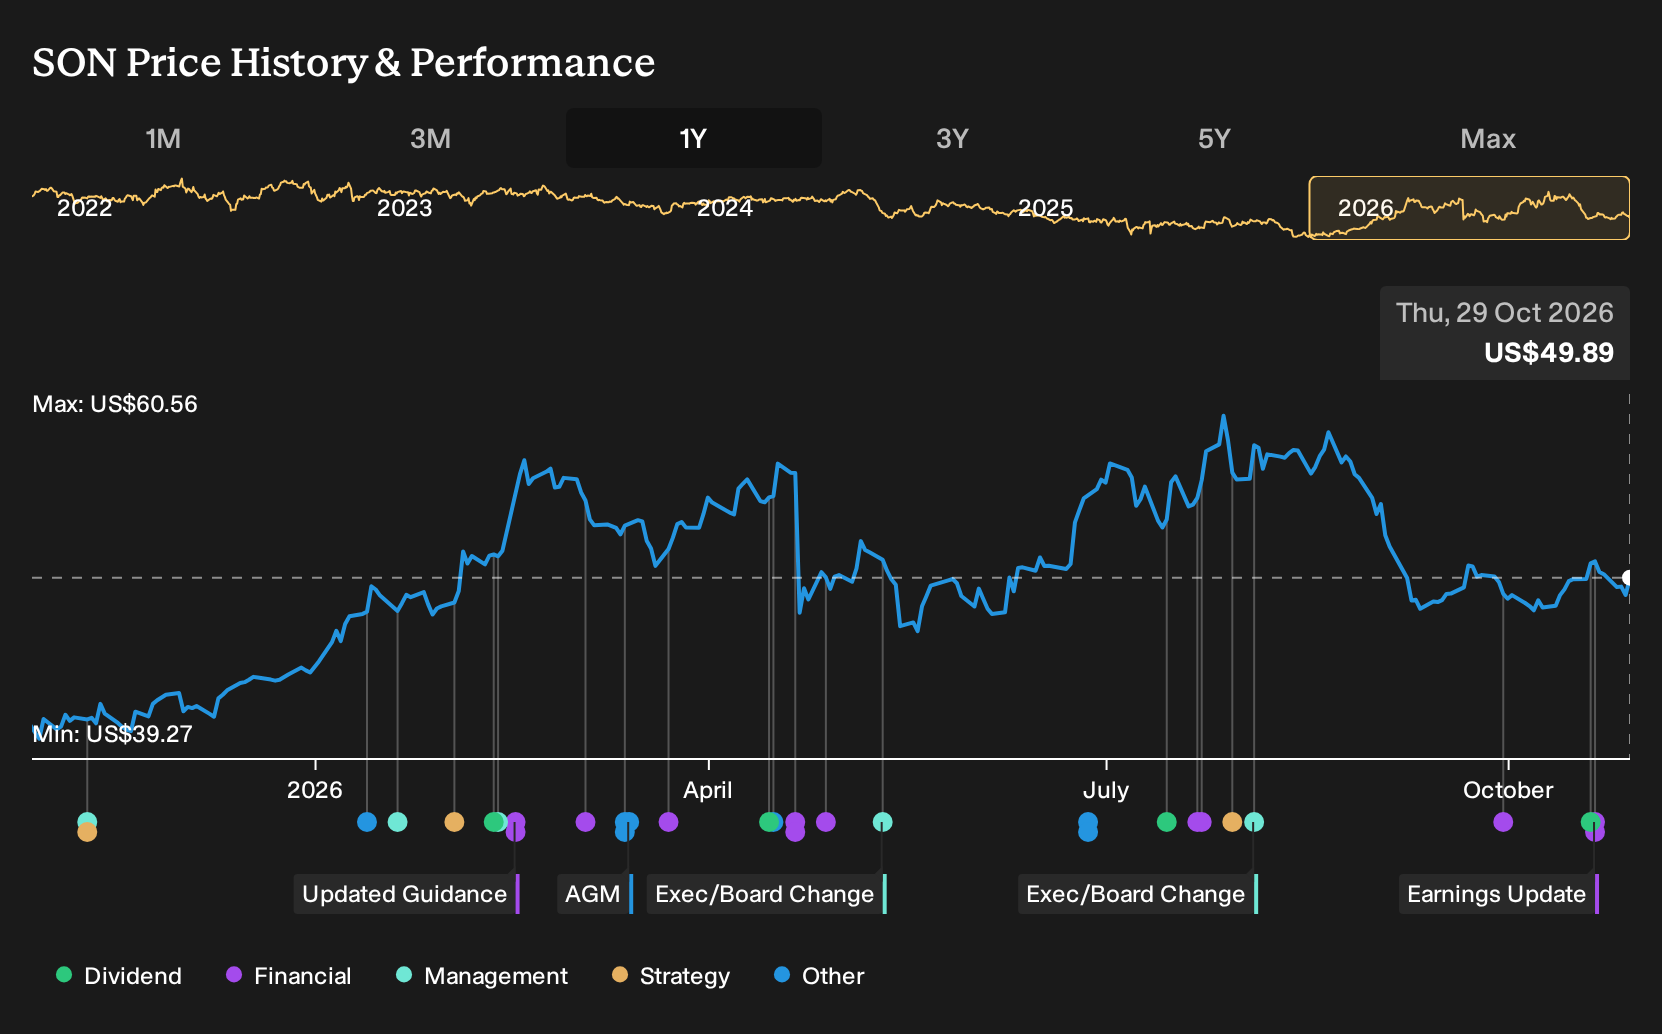
- Sonoco Products reported third quarter 2026 sales of US$2,041.58 million and a net loss of US$732.1 million, alongside lower nine month sales and a loss position for the year to date compared with profits a year earlier.
- The swing from profit to loss, combined with revised 2026 net sales guidance of US$7.20 billion to US$7.40 billion and a maintained US$0.54 quarterly dividend, puts Sonoco Products' cash generation, cost actions and balance sheet priorities under sharper scrutiny.
- We will now see how Sonoco Products' sharp quarterly net loss could reshape the existing investment narrative built around margin improvement.
Pressure test Sonoco Products' latest results against peers by scanning a curated list of solid balance sheet and fundamentals (23 results) that may better align with the resilience you want from a packaging stock under earnings strain.
Sonoco Products Investment Narrative Recap
To own Sonoco Products through this kind of quarter, you need to believe the packaging platform can convert its cost and automation programs into steadier earnings and cash flows. The sharp move into a loss in 2026 puts that belief under pressure because it shifts focus from margin improvement to basic earnings repair and balance sheet resilience.
The immediate catalyst is execution on the multi year profitability performance plan and capital projects, since that is what can support a return to profitability. The biggest operational risk right now is that inflation, tariffs, FX swings and softer demand keep squeezing margins, which could limit how quickly those savings show up in reported results.
The most telling disclosure for that debate is the revised 2026 net sales outlook of US$7.20b to US$7.40b. Management has effectively reset expectations for top line scale this year. That, in turn, frames how much operating leverage is realistically available from footprint work and automation in the near term.
For you as a shareholder, that guidance range becomes a reference point for assessing execution on cost savings and pricing. Any shortfall against it would magnify existing concerns that debt is not well covered by operating cash flow, while delivery within the range would at least support the view that Sonoco Products can fund its margin and growth plans from internal resources.
Sonoco Products' analyst narrative points to US$7.8b in revenue and US$424.3 million in earnings by 2029, based on 1.4% yearly revenue growth and an earnings decline of about US$220.7 million from current earnings of US$645.0 million.
Uncover why Sonoco Products' fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view depends on Sonoco Products achieving those more upbeat synergy and revenue plans. The most optimistic analysts were looking for US$8.0b of sales and about US$500.3 million in earnings by 2029, before this loss making quarter landed. That gap in expectations shows how sharply opinions, and future narratives, could shift.
Explore 2 other Sonoco Products fair value estimates, including one that suggests potential upside of as much as 205% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sonoco Products research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sonoco Products. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sonoco Products' overall financial health at a glance.
Looking for more Sonoco Products sized investment ideas?
Once you have formed a view on Sonoco Products, it often helps to compare that thesis with other opportunities that match the level of resilience, income or mispricing you are targeting. The Simply Wall St Screener can help you quickly surface a few different angles to pressure test your assumptions and widen your watchlist.
- If you care most about quality and downside protection, scan a curated set of resilient businesses through a 30 resilient stocks with low risk scores that aims to keep risk scores tight while still offering room for upside.
- For income focused investing where yield and staying power matter, assess dividend heavy companies by running a 7 dividend fortresses that concentrates on higher payout levels backed by underlying fundamentals.
- When you want to look beyond well known large caps, broaden your opportunity set by reviewing a 18 high quality undiscovered gems that highlights lesser followed stocks with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com