


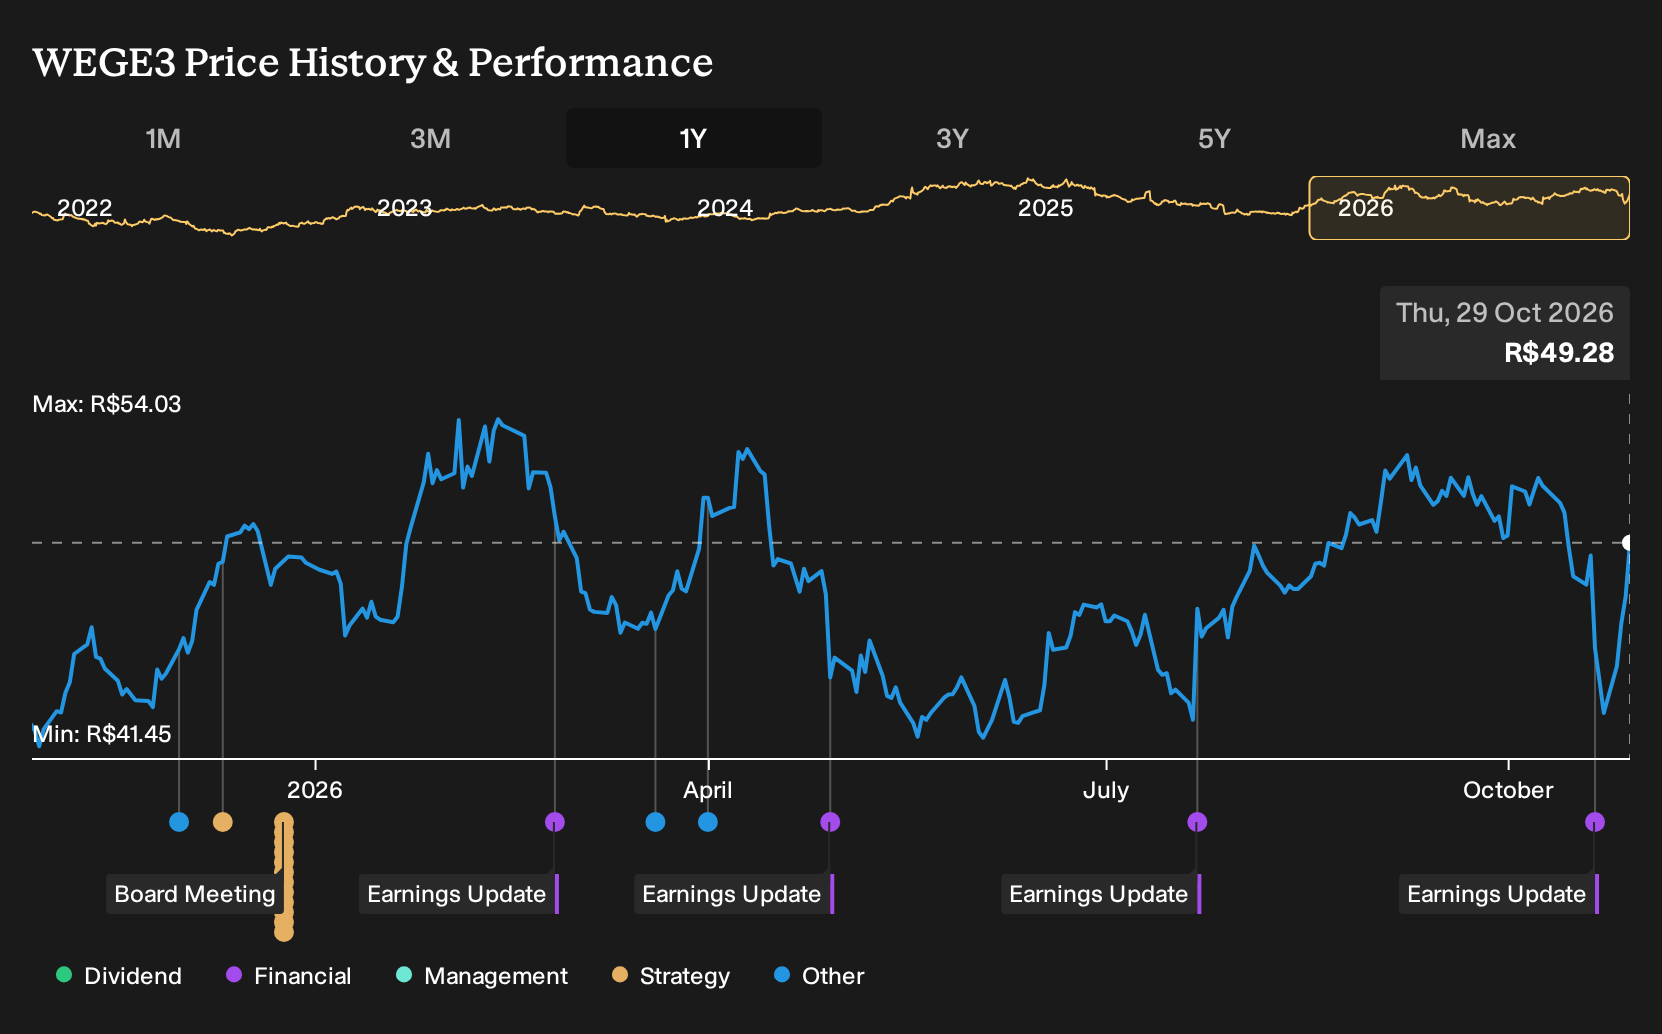
If WEG was sitting on your watchlist instead of in your brokerage account, the last twelve months may feel like a missed call. Holding WEG over the past year would have returned 23.8%, including dividends. That outcome invites a harder question. Back in October 2025, when analysts were split between grid-led expansion and tariff-driven margin strain, what business clues could have helped you judge whether grid modernization and automation were strong enough to outweigh those geopolitical and cost concerns?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
If the move has made WEG harder to judge, start where the gap is still open and scan 200 high quality undervalued stocks.
The Two WEG Narratives Investors Had To Weigh
The shares cost R$42.05 at the start of the period, and anyone looking at WEG then had to choose which story felt more realistic.
The bullish narrative put Fair Value at R$50.82, which is 21% above the start price. It leaned on grid modernization and electrification, assuming strong demand for transformers, synchronous compensators, and energy storage as WEG worked to expand T&D capacity.
The bearish view anchored Fair Value at R$38.8, which is 8% below the start price. It focused on geopolitical strain and tariff risk, with concern that higher copper and logistics costs would squeeze margins if price increases lagged.
What WEG’s Results Actually Tested
The most concrete evidence arrived with WEG’s Q3 2026 filing. Revenue reached R$10.86b and net income R$1.67b, higher than Q3 2025, which gave the grid-led expansion story something to point to. Net margin slipped from 16.1% to 15.3%, which kept the cautious, tariff-and-cost case in play. The evidence cut both ways.
The key assumption investors were really testing was whether revenue growth would come with stronger profitability. When you assess another industrial stock, track net margin alongside sales, not just the top line, to see if the profitability leg of the thesis is actually showing up.
What WEG’s Current Price Already Assumes
Today WEG trades at R$49.28, above where this Narrative’s Fair Value estimate sits. The Narrative argues that much of the appeal of global exposure and long projects is already reflected in the valuation.
Buying at this level means banking on WEG converting new grid, storage and data center buildouts into durable profitability, so how does the risk of underused long cycle assets and tariff friction weigh on that assumption?
"The numbers imply the share price already prices in strong long-term execution on these projects and a continuation of high ROIC and EBITDA margins, leaving limited room for disappointment if growth or profitability soften."
The price and this Narrative do not agree. → Uncover what this Narrative says WEG is actually worth
Go Straight To The Source
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 26% below our estimate - converts rising platform inflows through a unified tech stack into operating leverage.
- Company 2 - 25% below our estimate - expands surgeon use of antibiotic-eluting bone grafts across infection-focused procedures effectively.
- Company 3 - 17% below our estimate - scales preventive wellness clinics and proprietary treatments as consumer health awareness increases.
Three companies from the same screener. Open every one of the 203 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com