


- Silgan Holdings reported third quarter 2026 sales of US$2,040.2 million and net income of US$105 million, with adjusted EPS of US$1.31 topping analyst expectations despite a small revenue shortfall.
- The packaging group paired record adjusted earnings with raised full year EPS guidance and highlighted strong momentum in higher value pharma and fragrance dispensing products plus pet food packaging.
- This article examines how Silgan Holdings' record adjusted EPS and higher guidance may influence the investment narrative that investors have been using.
Silgan Holdings Investment Narrative Recap
To own Silgan Holdings, you essentially need to believe that the move toward higher value dispensing, pharma, fragrance and pet food packaging will keep offsetting softer areas and cost pressures. The latest quarter supports that story on earnings quality, even though reported net income for both the quarter and first nine months lagged last year.
The key near term swing factor is execution on mix and pricing so that adjusted EPS strength does not rely only on short bursts of cost control. The biggest risk is still input cost and volume pressure squeezing cash generation at a time when debt coverage is already flagged as a weak point.
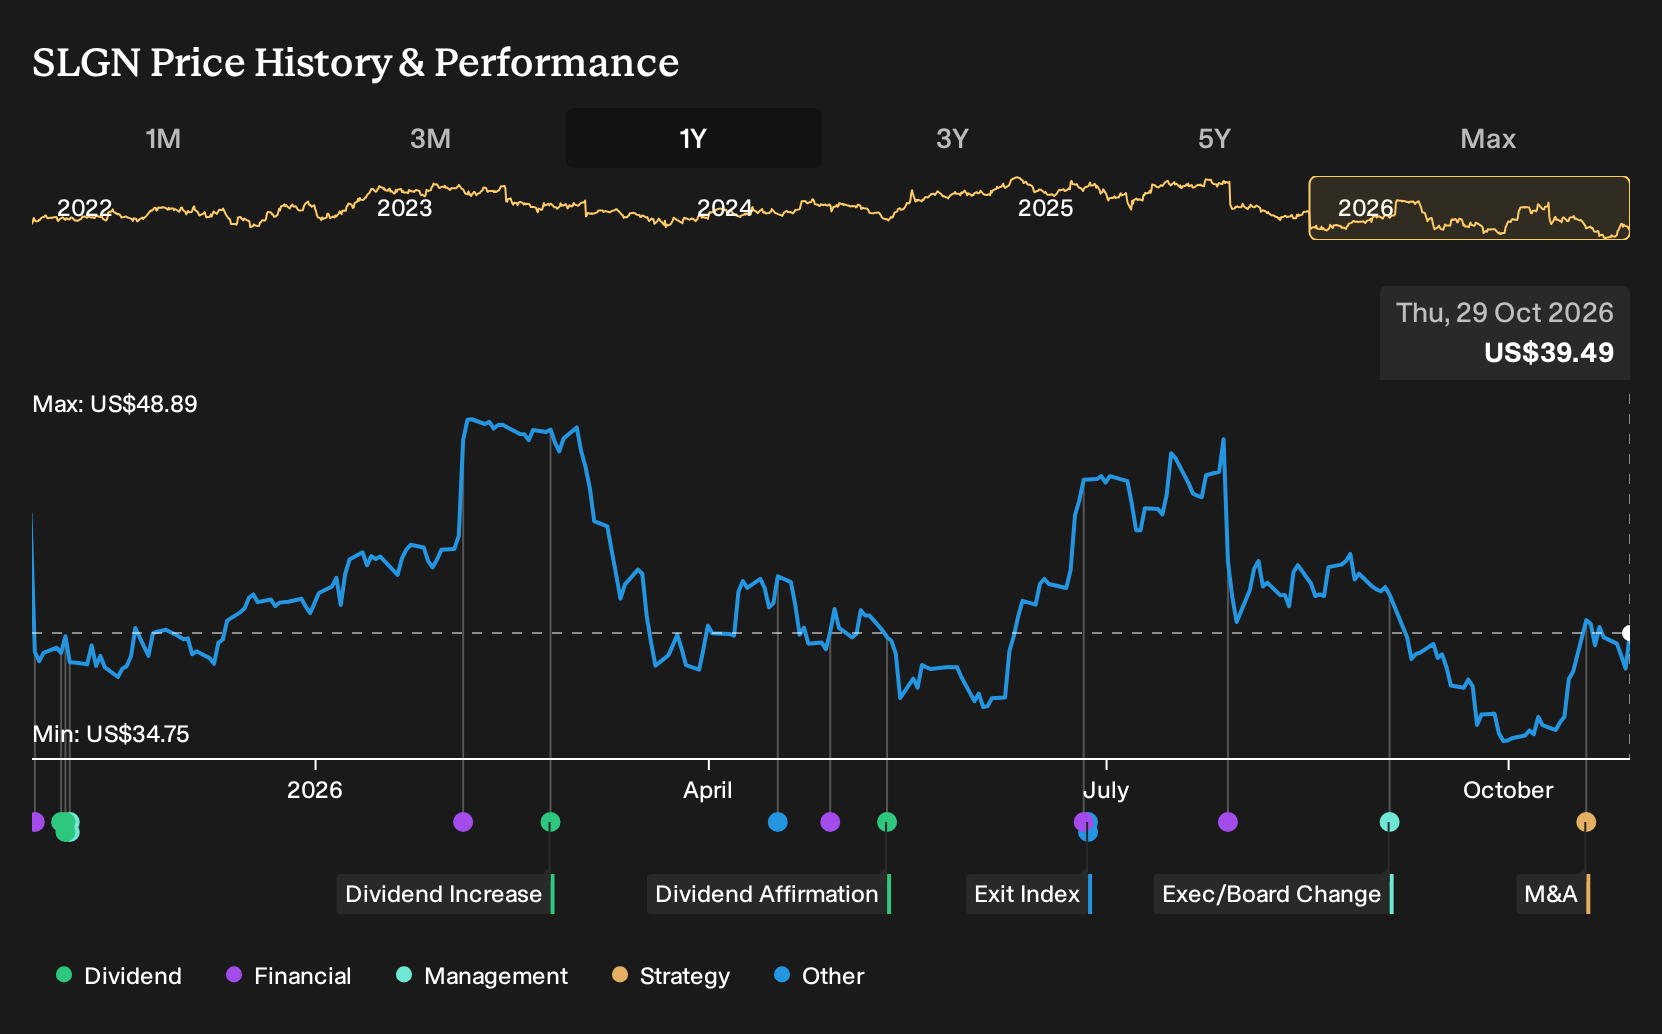
The Trivium acquisition plan is the announcement that matters most against this earnings backdrop. Management framed it as portfolio acceleration with more metal packaging scale, at a time when Dispensing and Specialty Closures and pet food continue to shape the Silgan Holdings story. Integration and financing will sit under the microscope from here.
For you as an investor, the link between Trivium and the current quarter is simple. Any larger footprint in rigid packaging can reinforce the existing catalysts in higher margin dispensing, or it can dilute them if volumes underperform and cash flow stays tight. Execution against synergy targets and leverage goals is the practical catalyst to watch.
What The Current Forecasts Assume For Silgan Holdings
Silgan Holdings' narrative projects US$7.3b revenue and US$460.8 million earnings by 2029. That profile rests on 3.0% yearly revenue growth and an earnings increase of about US$190.5 million from US$270.3 million today.
Uncover why Silgan Holdings' fair value indicates a 32% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One alternate view focuses on free cash flow. The most optimistic analysts were penciling in about US$7.7b of revenue and roughly US$517.7 million of earnings by 2029, versus the consensus US$7.3b and US$460.8 million. That group already saw Silgan Holdings as underappreciated on cash generation. This fresh earnings beat and raised guidance could reshape both narratives, so it makes sense for you to compare several viewpoints before evaluating how compelling that cash flow story appears.
Explore another Silgan Holdings fair value estimate, including one that suggests as much as 191% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Silgan Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Silgan Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Silgan Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Silgan Holdings?
Once you have a view on Silgan Holdings, it can help to compare that thesis with other companies that share traits you care about, whether that is valuation, balance sheet strength, or income potential. The Simply Wall St Screener lets you filter the market quickly so you can focus your time on a short list that actually fits your approach.
- If you care most about paying a fair price for resilient businesses, start with companies that screen as 30 high quality undervalued stocks relative to their fundamentals.
- If balance sheet strength and downside resilience matter more to you than headline growth, narrow the field using a list of solid balance sheet and fundamentals (23 results) to see which firms might better handle tougher conditions.
- If you are building an income focused portfolio, use a screener centered on steady payers and investigate a set of 7 dividend fortresses that combine higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com