


Millrose Properties has had a choppy year on the market, and fresh headlines around both record earnings and securities lawsuits now put a sharper spotlight on what investors are really paying for its profits. The key issue is whether the current share price around US$26 reflects the strength and quality of Millrose Properties' earnings stream.
- The stock is down 12.5% year to date, which puts the focus on whether this weaker run has brought Millrose Properties closer to or further away from an earnings based fair value.
- Record net income alongside a US$250m share repurchase authorization may support expectations for Millrose Properties' future cash generation, especially if management can sustain underwriting discipline while funding its housing related investments.
- The analysts covering Millrose Properties have run their own numbers. See what analysts think Millrose Properties's shares could be worth.
For investors, the debate is whether Millrose Properties' recent earnings justify the price implied by its current P/E against the Fair Ratio benchmark.
If you want a clean comparison point for Millrose Properties' earnings story and lawsuit headlines, a focused screen of 30 resilient stocks with low risk scores is a useful starting point.
Does Millrose Properties Look Undervalued on Earnings?
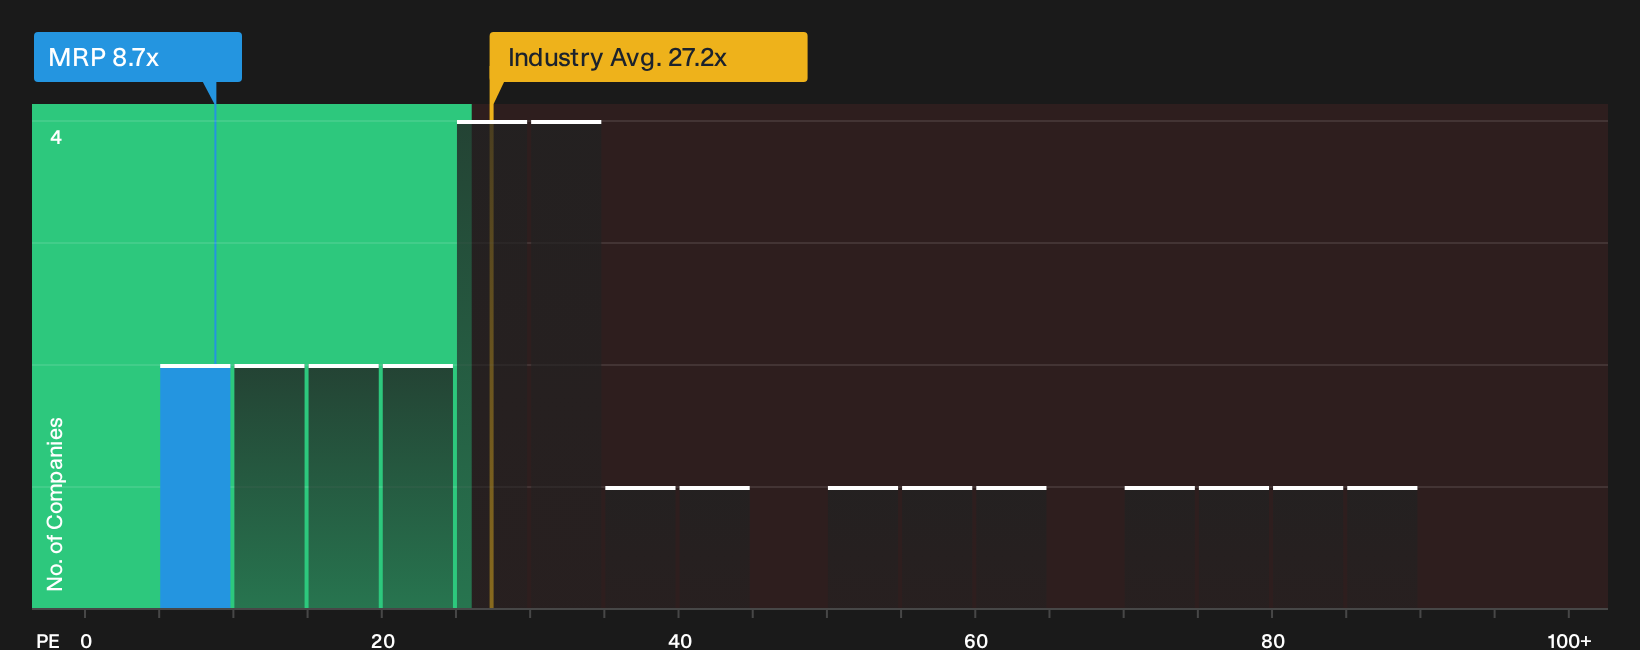
P/E is a useful lens for Millrose Properties because the share price debate is currently anchored to record net income. At roughly 8.7x earnings, the stock trades at a sizeable discount to both the Specialized REITs industry average of about 15.5x and the wider peer group around 18.2x.
The Fair Ratio model, which adjusts for Millrose Properties' sector, margins, size and risk profile, points to a higher multiple than where the shares trade today, which suggests the stock is undervalued on this framework. Because the securities lawsuits filed in 2026 have clouded confidence around reported results, the gap between Millrose Properties' P/E and these benchmarks may be reflecting legal and governance risk more than pure earnings power. Explore the numbers behind Millrose Properties's P/E valuation.
The Millrose Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Millrose Properties pick up exactly where this valuation puzzle leaves off, spelling out what kind of future for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price on the Community page. Each scenario ties its number to a concrete view of where Millrose Properties' performance and risk profile might head next, which gives you something specific to revisit as fresh information comes through.
One of the top community narratives on Millrose Properties: 30% undervalued
"Growing use of development loan receivables and flexible capital structures alongside option agreements allows Millrose to capture a wider share of the builder capital stack..."
Discover why this Narrative puts Millrose Properties at 30% undervalued.
The Millrose Properties story is still missing one piece
Everything so far has focused on what Millrose Properties looks like today, but there is a separate clue in where professional analysts think this business could be a few years from now. Explore where analysts expect Millrose Properties to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com