


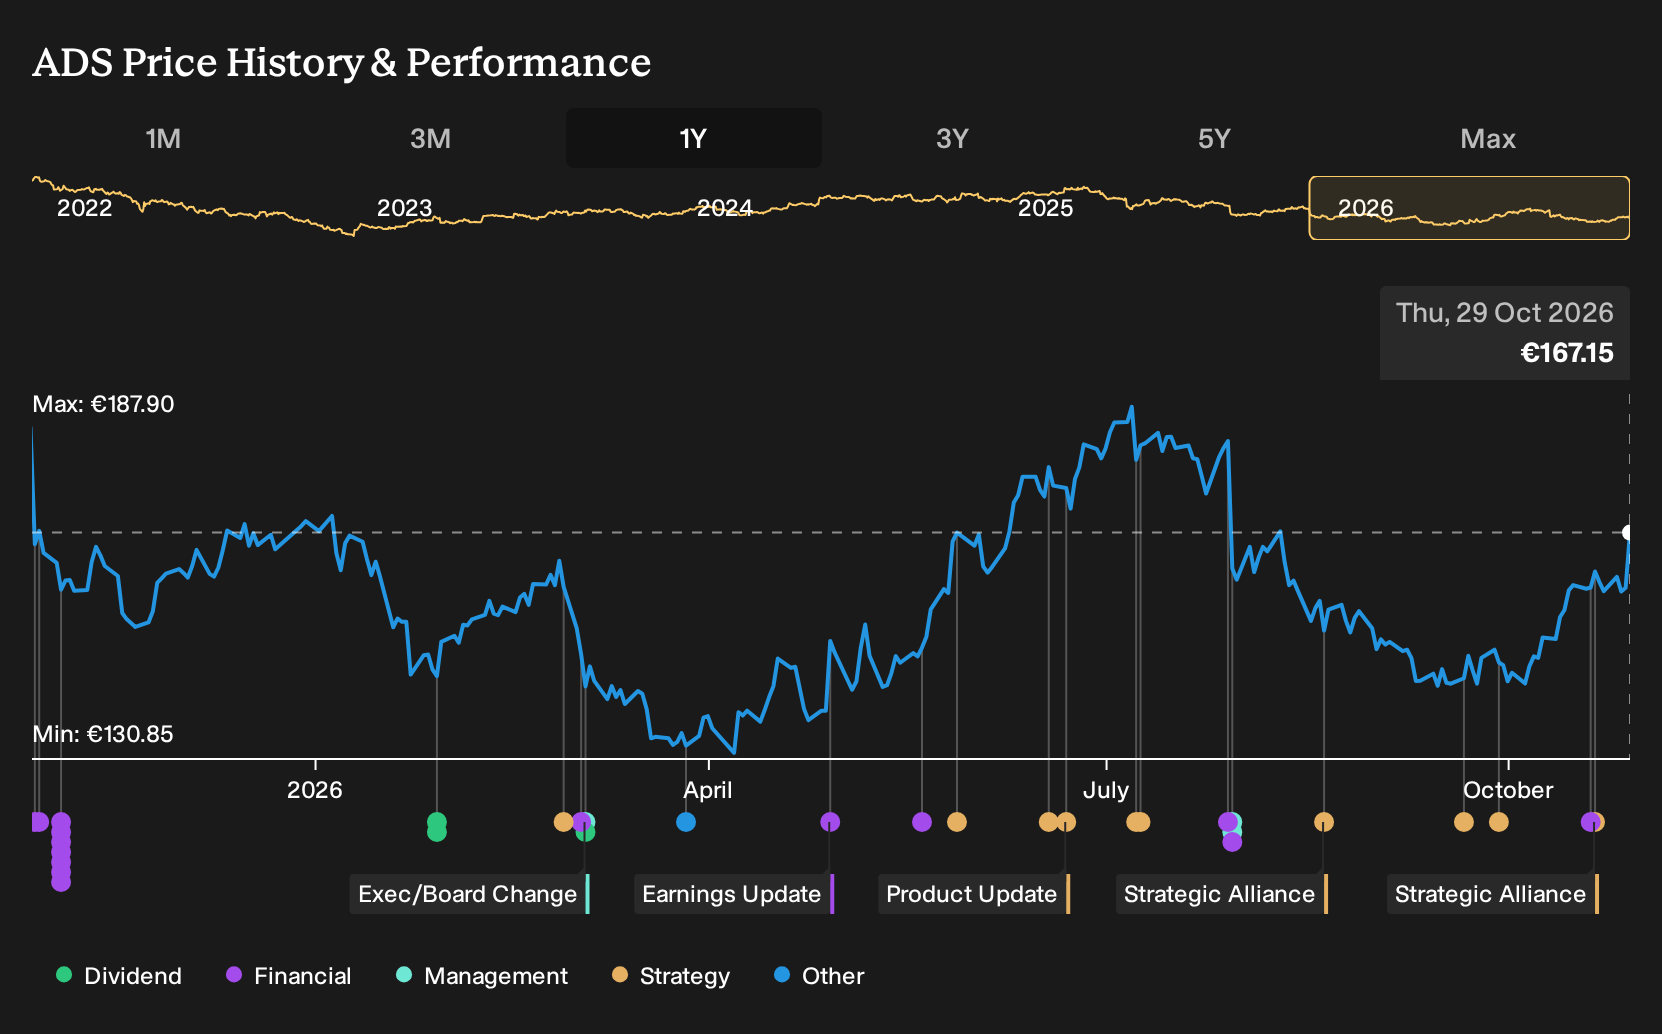
- Adidas reported third quarter 2026 sales of €7,252 million and net income of €706 million, alongside higher earnings per share for both the quarter and first nine months compared with a year earlier.
- The decision to lift full year 2026 operating profit guidance to about €2.5b, while reinvesting roughly €100 million in fourth quarter initiatives, underlines management’s focus on profitability and future operating leverage rather than short term margin maximisation.
- The focus now turns to how adidas’s higher full year profit outlook and record quarterly performance may reshape the broader investment narrative.
See how adidas compares with a curated group of peers by reviewing 200 high quality undervalued stocks, which combine balance sheet strength with solid cash generation.
adidas Investment Narrative Recap
To own adidas, you need to believe the performance engine and direct to consumer push can keep offsetting pressure in lifestyle footwear, tariffs and promotions. The record third quarter and higher full year operating profit outlook point to a business that, right now, is executing well on that mix shift and cost discipline.
The key short term catalyst is continued momentum in performance categories and direct channels translating into resilient gross margins despite heavy discounting by rivals. The biggest operational risk remains tariff and promotional pressure eroding pricing power. The latest results help, but do not remove that risk, so it still deserves close attention.
The raised 2026 operating profit guidance to about €2.5b, even after reinvesting roughly €100 million in fourth quarter initiatives, is the announcement that really matters here. It ties directly into the core thesis around adidas, that disciplined execution in higher margin channels and categories can support earnings quality.
For catalysts, that guidance move makes future quarterly margin delivery a clearer focal point. Any wobble in gross margin resilience or higher than expected promotional activity could challenge that outlook. Conversely, clean execution on these reinvestment projects would reinforce confidence in adidas turning current operating momentum into durable profitability.
What The Current adidas Consensus Assumes
Analysts are effectively asking you to underwrite a bigger adidas by the end of the decade rather than a radically different one. The core assumption is that the existing performance and direct to consumer engine scales, with enough pricing discipline and cost control to lift profitability along the way.
Revenue forecasts call for 7.1% yearly top line growth over the next three years. That kind of pace would usually require a mix of higher unit volumes in performance categories, steadier sell through in lifestyle, and a richer contribution from adidas stores and e commerce compared with wholesale partners.
Earnings today are put at about €1.4b and the consensus points to €2.4b by 2029. That implies an increase of roughly €1.0b in profit over the period. Some analysts sit above that band with estimates up to €2.8b, which shows that views on how far margins can stretch are still quite spread.
Profitability assumptions are just as important as the headline earnings jump. Margin forecasts move from 5.3% today to 7.4% in three years. For an investor, that frames the story less as a pure growth idea and more as an execution test on product mix, channel blend and cost discipline.
On these numbers, the 2029 framework has adidas generating about €32.0b of revenue and €2.4b of earnings. The implied P/E multiple on those future earnings is 16.9x, compared with 19.9x today and a lower current multiple for the broader GB Luxury group at 12.1x. That spread signals that consensus still prices in a quality premium for the business.
adidas' narrative projects €32.0b revenue and €2.4b earnings by 2029. This setup implies 7.1% yearly revenue growth and an earnings increase of about €1.0b from €1.4b today.
Uncover how adidas' fair value indicates a 17% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate adidas story puts far more weight on upside from new performance franchises. Before this quarter’s record numbers, the most optimistic analysts already pencilled in revenue of about €33.7b and earnings of roughly €2.8b by 2029. You can see how far that view stretches from consensus, then decide which version feels more realistic to you.
Explore 5 other adidas fair value estimates, including one that suggests potential upside of as much as 115% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your adidas research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for adidas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate adidas' overall financial health at a glance.
Looking for more adidas investment ideas?
Once you have formed a view on adidas, it can help to cross check that thesis against a wider set of opportunities using the Simply Wall St Screener.
- For investors focused on stability, consider companies with stronger resilience profiles by reviewing the 220 resilient stocks with low risk scores to filter for businesses with lower risk scores.
- If balance sheet strength is a priority, look through the list of solid balance sheet and fundamentals (203 results) to find stocks that pair robust finances with solid fundamentals.
- For those hunting for overlooked opportunities, scan the 605 high quality undiscovered gems to spotlight high quality businesses which may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com