


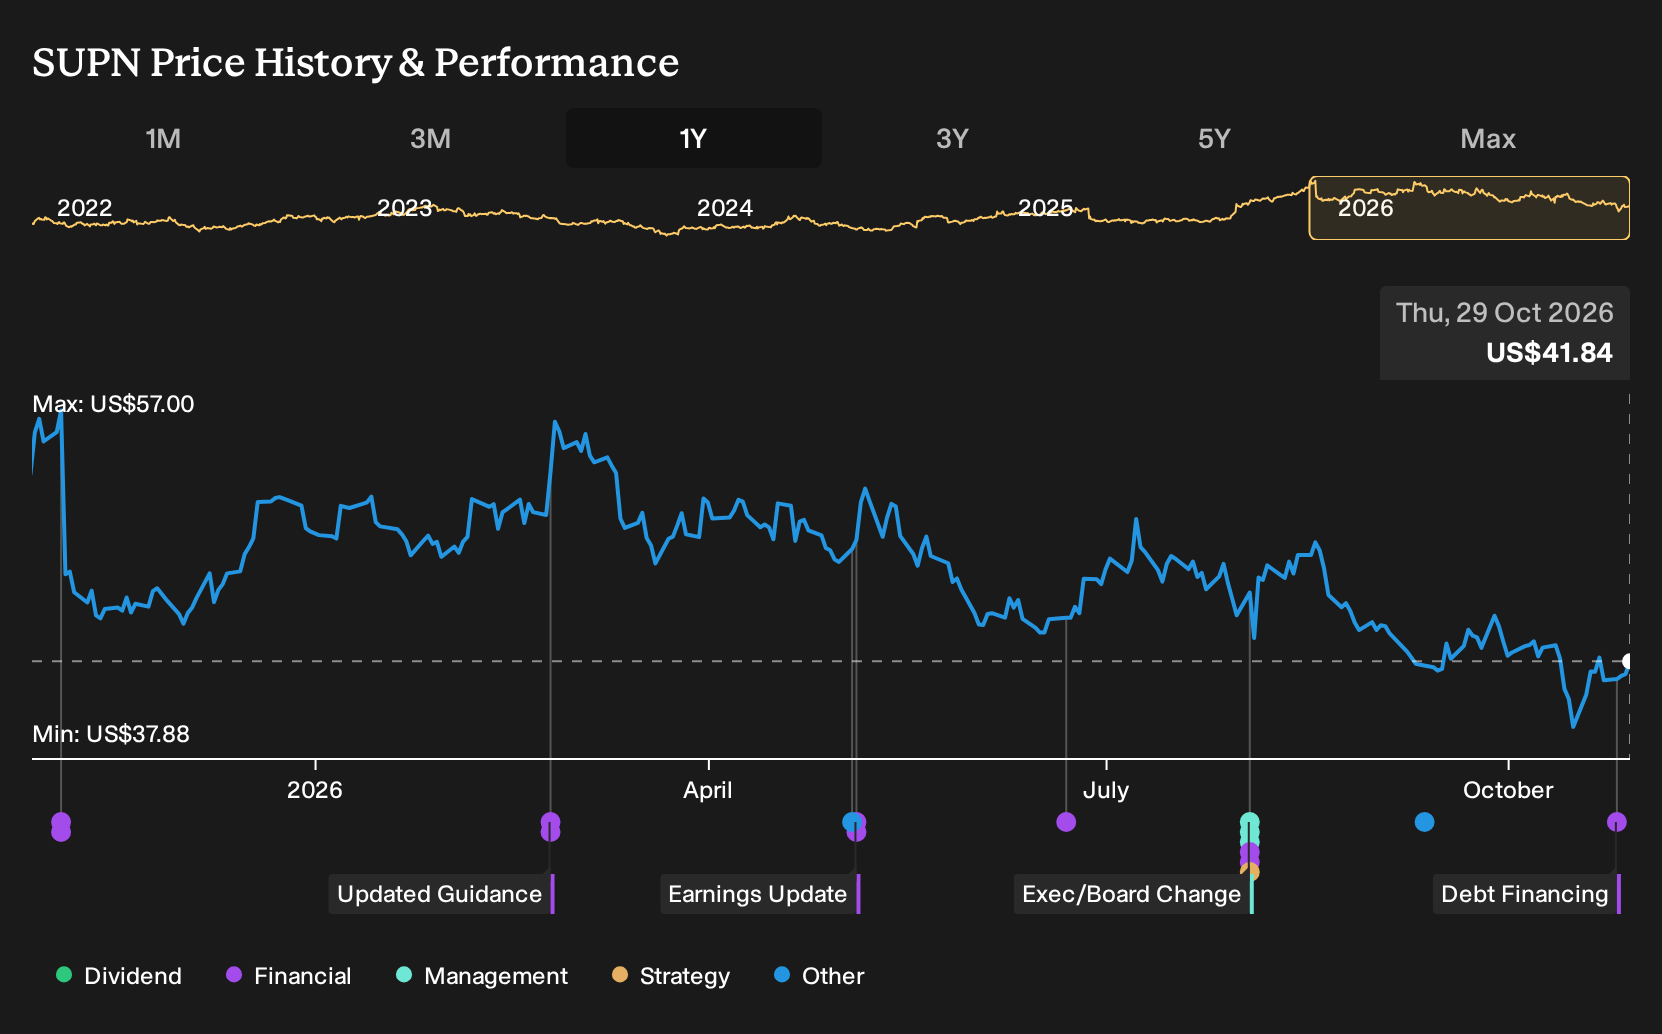
- Supernus Pharmaceuticals reported Q3 2026 revenue of US$226.77 million and net income of US$20.91 million, raised full year sales guidance to a range of US$875 million to US$900 million, and affirmed US$55 million of expected 2026 intangible asset impairment charges.
- The business combined record quarterly revenue and a swing back to profitability with plans for a new credit facility after terminating an unused UBS line ahead of its pending Indivior merger.
- We will now look at how Supernus Pharmaceuticals' raised 2026 revenue outlook could reshape the investment narrative for the merged CNS platform.
Scan how Supernus Pharmaceuticals stacks up against other CNS-focused players by reviewing a curated list of 36 healthcare AI stocks riding similar treatment and earnings catalysts.
Supernus Pharmaceuticals Investment Narrative Recap
To own Supernus Pharmaceuticals, you need to believe the combined CNS platform can turn record quarterly revenue into durable profitability while absorbing ongoing investment and impairment noise. The Q3 swing to a US$20.91 million profit, along with higher 2026 revenue guidance, supports that case in the near term. The key short term catalyst is execution around the Indivior merger and keeping core products growing through integration.
The biggest risk right now sits in operational complexity. Management still expects a full year operating loss and US$55 million of 2026 intangible impairments, which can mask underlying progress. If merger synergies, ONAPGO ramp, and the broader pipeline do not translate into cleaner earnings and better cash economics, the bullish CNS platform story weakens.
The raised 2026 revenue outlook to US$875 million to US$900 million, together with tighter guidance on GAAP operating loss of US$5 million to US$40 million, is the announcement that most directly frames this quarter. It indicates that management sees enough momentum in ONAPGO, Qelbree, and legacy XR products to support a bigger top line while still absorbing sizeable non cash charges.
For you as an investor, the practical question is how this outlook interacts with the Indivior tie up. A richer standalone revenue base and narrower loss range can give the future combined entity more room to pursue cost synergies and fund CNS trials without leaning as heavily on new borrowing. However, integration execution and the US$55 million impairment guidance keep risk on the table.
Supernus Pharmaceuticals' current earnings are a loss of US$109.9 million, with analyst consensus pointing to earnings of US$176.7 million on forecast revenue of US$1.8b by 2029. That outlook assumes revenue grows at 28.2% per year and earnings improve by about US$286.6 million by the 2029 estimate year.
Uncover why Supernus Pharmaceuticals' fair value indicates a 48% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community range from about US$61.75 to roughly US$380.90, which shows how far opinions on Supernus Pharmaceuticals can stretch. Some community members may focus on the raised 2026 guidance and merger synergies, while others concentrate on integration risk and ongoing impairment charges. Investor views clearly diverge, so it can be useful to explore several of these alternative perspectives before forming a stance.
Explore another Supernus Pharmaceuticals fair value estimate, including one that suggests it could be worth just $61.75!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Supernus Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Supernus Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Supernus Pharmaceuticals' overall financial health at a glance.
Looking for more Supernus Pharmaceuticals style investment ideas?
If you want to put what you have learned from Supernus Pharmaceuticals to work, a broad watchlist of other opportunities can help you stress test your thinking and avoid anchoring on a single stock.
- For investors hunting for mispriced quality, scan a curated set of companies that screen as potentially cheap on fundamentals through the 30 high quality undervalued stocks.
- If capital preservation sits high on your list, focus on businesses that pair steadier profiles with stronger risk checks using the 30 resilient stocks with low risk scores.
- When balance sheet strength is your main filter, start with companies that combine lower leverage with healthier fundamentals by using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com