


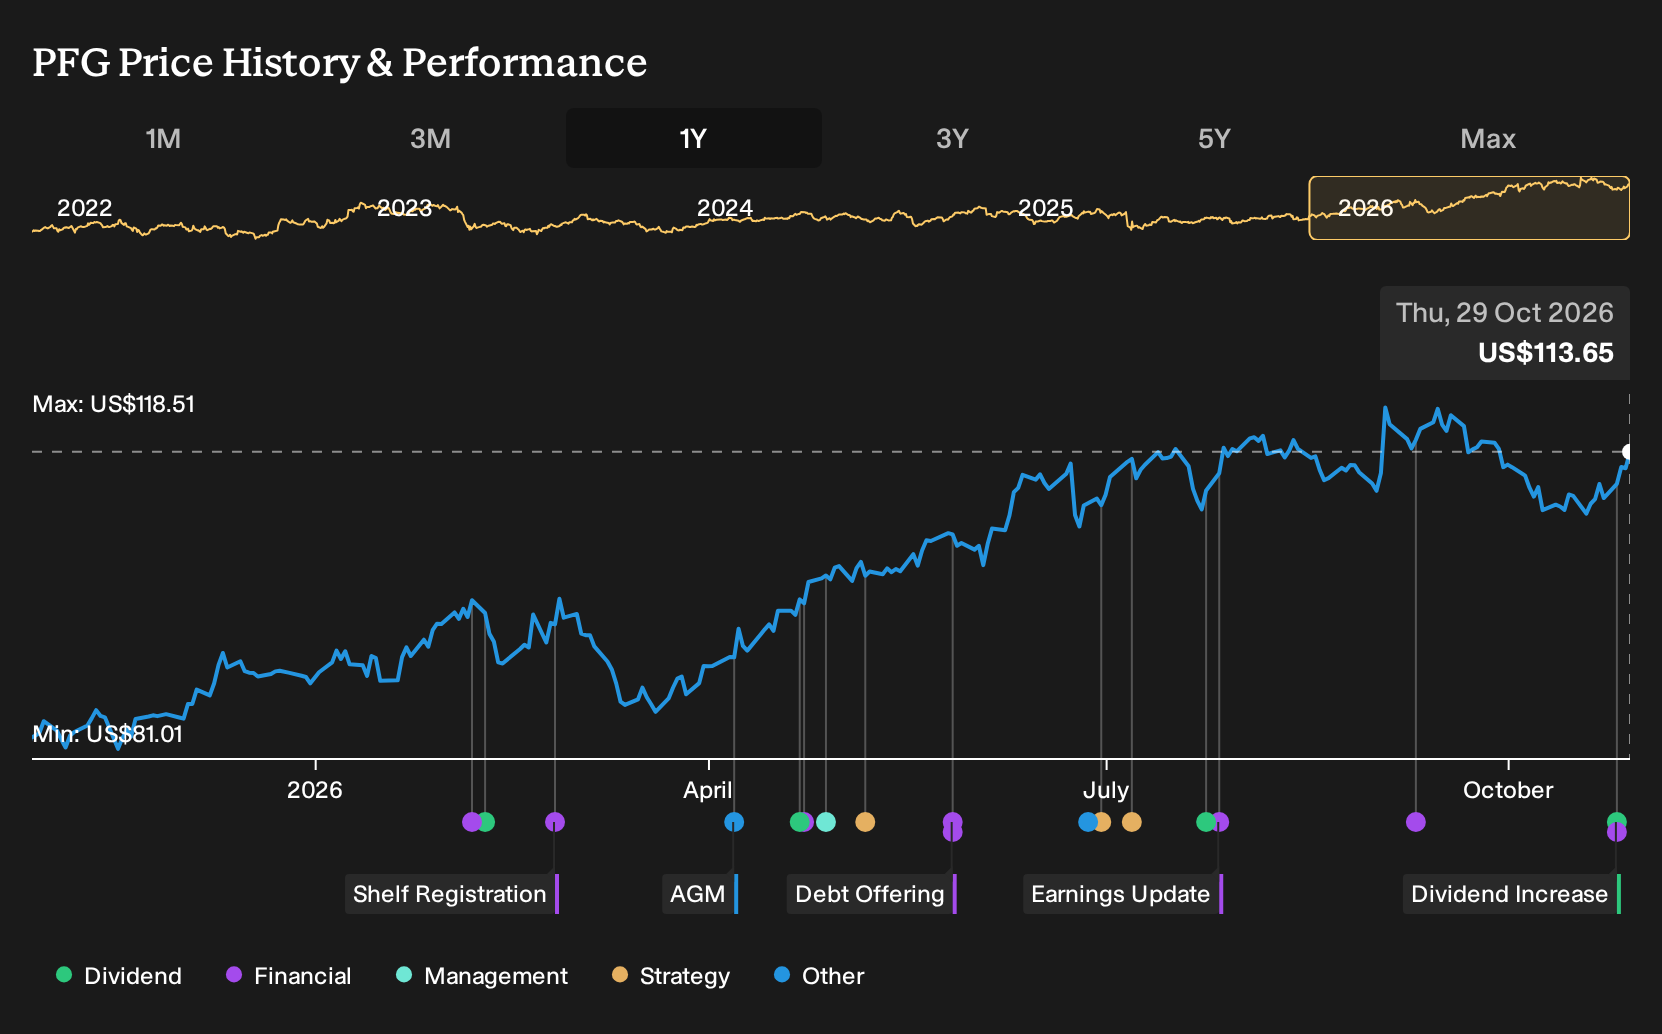
- Principal Financial Group raised its fourth quarter 2026 dividend to US$0.85 per share and reported third quarter revenue of US$4,616.4 million and net income of US$631.9 million, both above the prior year period.
- The company reported higher basic EPS and stronger adjusted non GAAP EPS alongside US$429 million of third quarter capital returns, while still facing US$11 billion of active equity outflows that matter for future asset management fee trends.
- We will look at how Principal Financial Group's investment narrative is influenced by strong third quarter earnings and the higher dividend.
See how Principal Financial Group's combination of rising dividends and recent earnings compares with other income oriented opportunities using our curated 7 dividend fortresses
Principal Financial Group Investment Narrative Recap
To stay invested in Principal Financial Group, you need to be comfortable with a fee based retirement and benefits engine that leans on steady deposits, disciplined capital returns, and tight cost control. The big short term swing factor is whether strong Retirement and Income Solutions earnings and Specialty Benefits margins keep offsetting pressure in asset management.
The main risk right now is clear. Continued US$11b level outflows from active equity strategies, combined with fee rates at the low end of the firm’s historical band, could weigh on asset management revenue. Recent results and the dividend lift do not remove that concern, although they reduce near term earnings anxiety.
The most relevant development is the US$0.85 per share fourth quarter dividend, up 1 cent from the third quarter and 8% from the prior year period. That move, coupled with US$429m of capital returns in the third quarter, signals the board’s willingness to keep returning cash while the business absorbs equity outflows.
For you as a shareholder, this dividend decision ties directly into the catalyst thesis. It leans on Principal Financial Group continuing to generate strong cash flow from retirement, benefits, and fee based platforms even if active equity remains under pressure. The higher payout also increases sensitivity to any future hit to margins or investment management fees.
What The Current Analyst Framework Implies For Principal Financial Group
Principal Financial Group's current analyst playbook centers on earnings and revenue targets that extend beyond the latest dividend move. Forecasts call for US$19.6b of revenue and US$2.4b of earnings by 2029. Those figures are based on an assumed 7.7% yearly revenue growth rate.
Analysts are anchoring those 2029 earnings projections on an increase from US$1.6b of earnings today to US$2.4b in a few years. That step up implies an US$800m earnings increase from current levels if the consensus view plays out. For you, the gap between today's profits and the forecast line helps frame how much execution risk you are taking on for Principal Financial Group over that period.
Principal Financial Group's narrative projects US$19.6b revenue and US$2.4b earnings by 2029. This would require 7.7% yearly revenue growth and an earnings increase of about US$800m from US$1.6b today.
Uncover why Principal Financial Group's fair value indicates a valuation gap that is roughly in line with the current price.
Exploring Other Perspectives
One alternate view focuses squarely on Principal Financial Group’s valuation risk rather than the equity outflows. The most bearish analysts were working off revenue of about US$19.2b and earnings of roughly US$2.5b by 2029, yet still saw a much lower P/E and price target. Those assumptions came before this Q3 beat and dividend increase, so you may see those narratives shift as fresh data filters through.
Explore 2 other Principal Financial Group fair value estimates, including one that suggests it could be worth just $111.17.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Principal Financial Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Principal Financial Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Principal Financial Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Principal Financial Group?
Once you have a view on Principal Financial Group, it can help to line it up against other listed businesses with different strengths so you can see where the real trade offs sit.
- If you care most about resilient balance sheets and steady fundamentals, start with this list of solid balance sheet and fundamentals (23 results) to compare against Principal Financial Group.
- For those hunting for potential mispricing, widen your research to a curated 30 high quality undervalued stocks that may offer a different mix of quality and price.
- When you want to widen your opportunity set beyond well known tickers, scan this 18 high quality undiscovered gems and see which profiles line up with your own income and risk goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com