


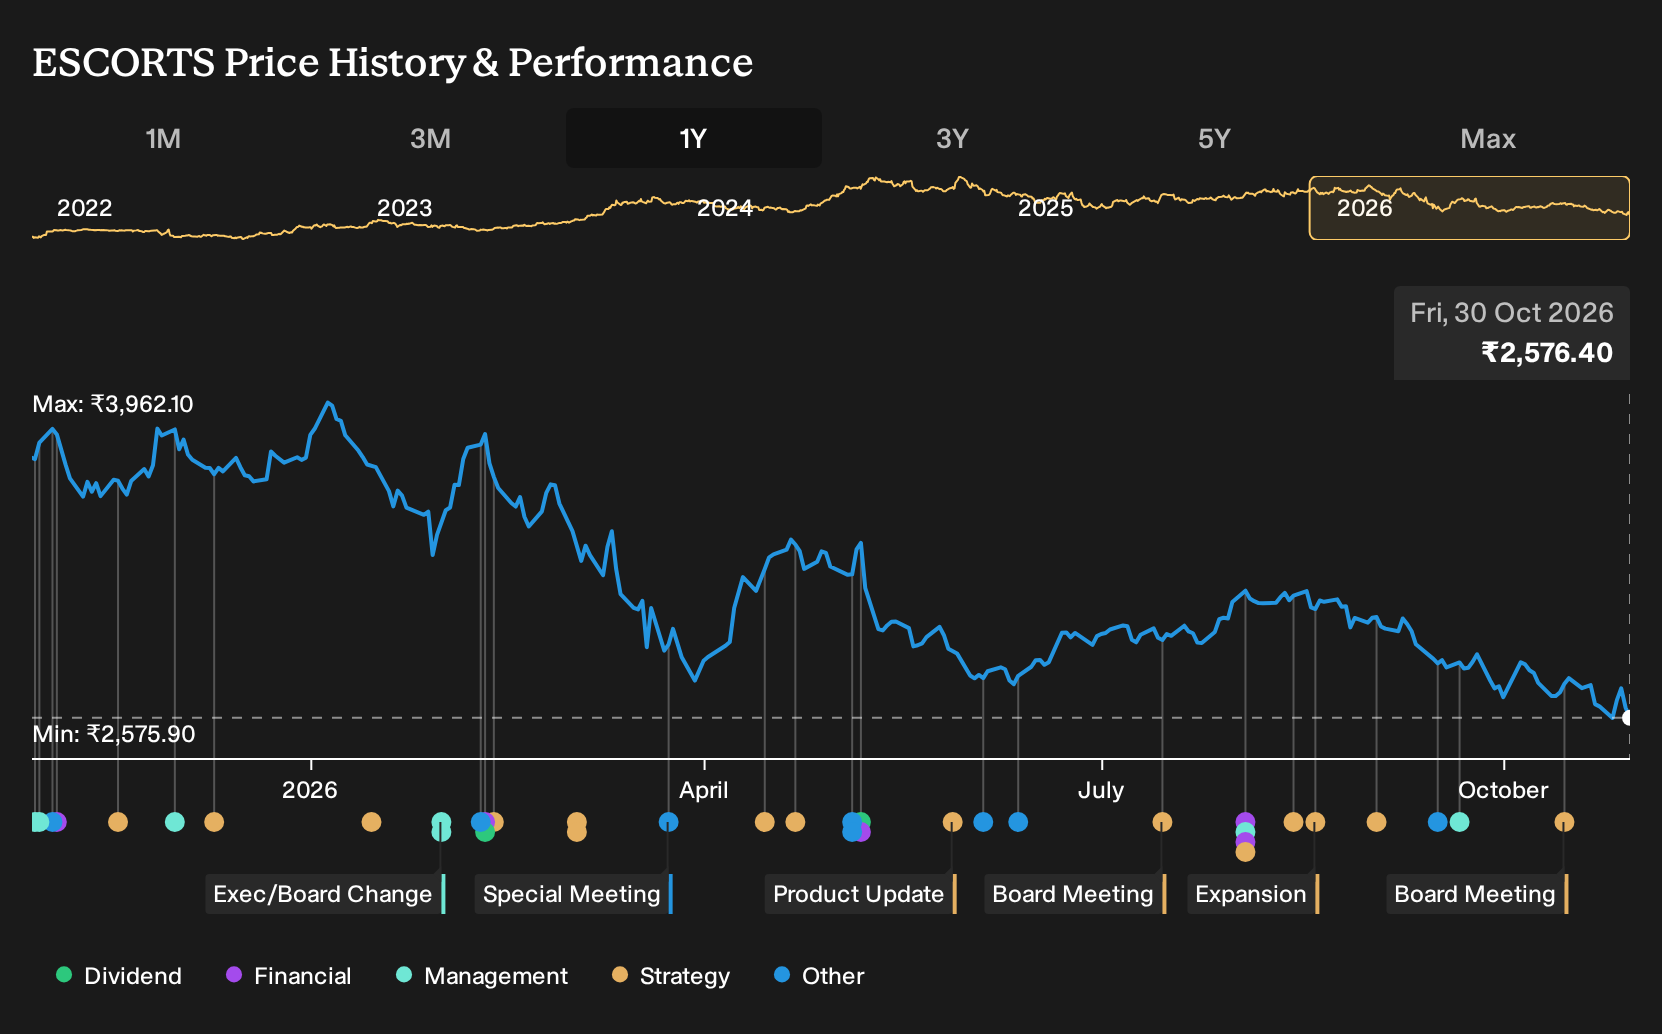
Escorts Kubota just reported higher revenue and slightly higher net income, yet the share price told a very different story over the same stretch. Investors who held Escorts Kubota over the past year are down 30.8%, including dividends. If you had been weighing a purchase back on 30 October 2025, and you knew only the upbeat analyst debates and export ambitions, what early cracks would you have focused on to judge that risk?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Escorts Kubota has already moved. See which of 200 high quality undervalued stocks still trade below our estimates.
The Two Escorts Kubota Stories Investors Were Arguing About
The shares cost ₹3,714 at the start of the period, and anyone looking at Escorts Kubota then was choosing between two quite different stories that both sounded reasonable.
On the optimistic side, the Narrative put Fair Value at ₹3,998, 8% above the start price. It leaned on rapid global food demand, rising mechanization, and Kubota led exports, as well as a belief that revenue could grow 16.0% a year even if profit margins eased slightly.
The more cautious Narrative set Fair Value at ₹3,517, 5% below the start price. It still assumed 14.9% annual revenue growth and Kubota integration, but highlighted concerns that weak regional performance, supply chain dependence, and rising input costs could limit long term margin expansion.
What The Escorts Kubota Results Put To The Test
The clearest new fact was Escorts Kubota reporting Q1 2027 revenue of ₹32,075.5m and net income of ₹3,859.4m, both higher than Q1 2026. Net margin slipped from 14.8% to 12.0%, so profitability quality did not move in step with the higher totals. That mix of stronger scale but thinner margins cuts both ways for investors with optimistic or cautious narratives.
The live assumption here was margin resilience. For another stock built on export expansion and product rollouts, it may be useful to track whether net margin holds up as sales climb, rather than assuming operating scale automatically preserves profitability.
What You Would Be Paying For In Escorts Kubota Today
With Escorts Kubota at ₹2,576 after a 30.8% loss over the past year, the selected Narrative still places its Fair Value above the current price based on its own assumptions rather than hard fact.
The pitch leans on exports, product refreshes, financing and construction equipment as a wider earnings engine. A buyer today would be betting that export led expansion and a broader non tractor mix can sustain margins despite cost and regional pressures.
"The main factor that has to go right is that Escorts Kubota continues to widen its non-tractor and construction equipment mix while managing cost inflation so that margins stay supported even when individual segments face pressure."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Before The Next Story Makes Headlines
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 41% below our estimate - sells oncology planning software that hospitals adopt as AI driven treatments become standard.
- Company 2 - 25% below our estimate - grows surgeon adoption of antibiotic eluting bone grafts as infection focused procedures shift to local delivery.
- Company 3 - 18% below our estimate - wins maintenance and modernization contracts as a larger salesforce targets elevator owners seeking better uptime.
Three companies from the same screener. Open the full list of 203 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com