


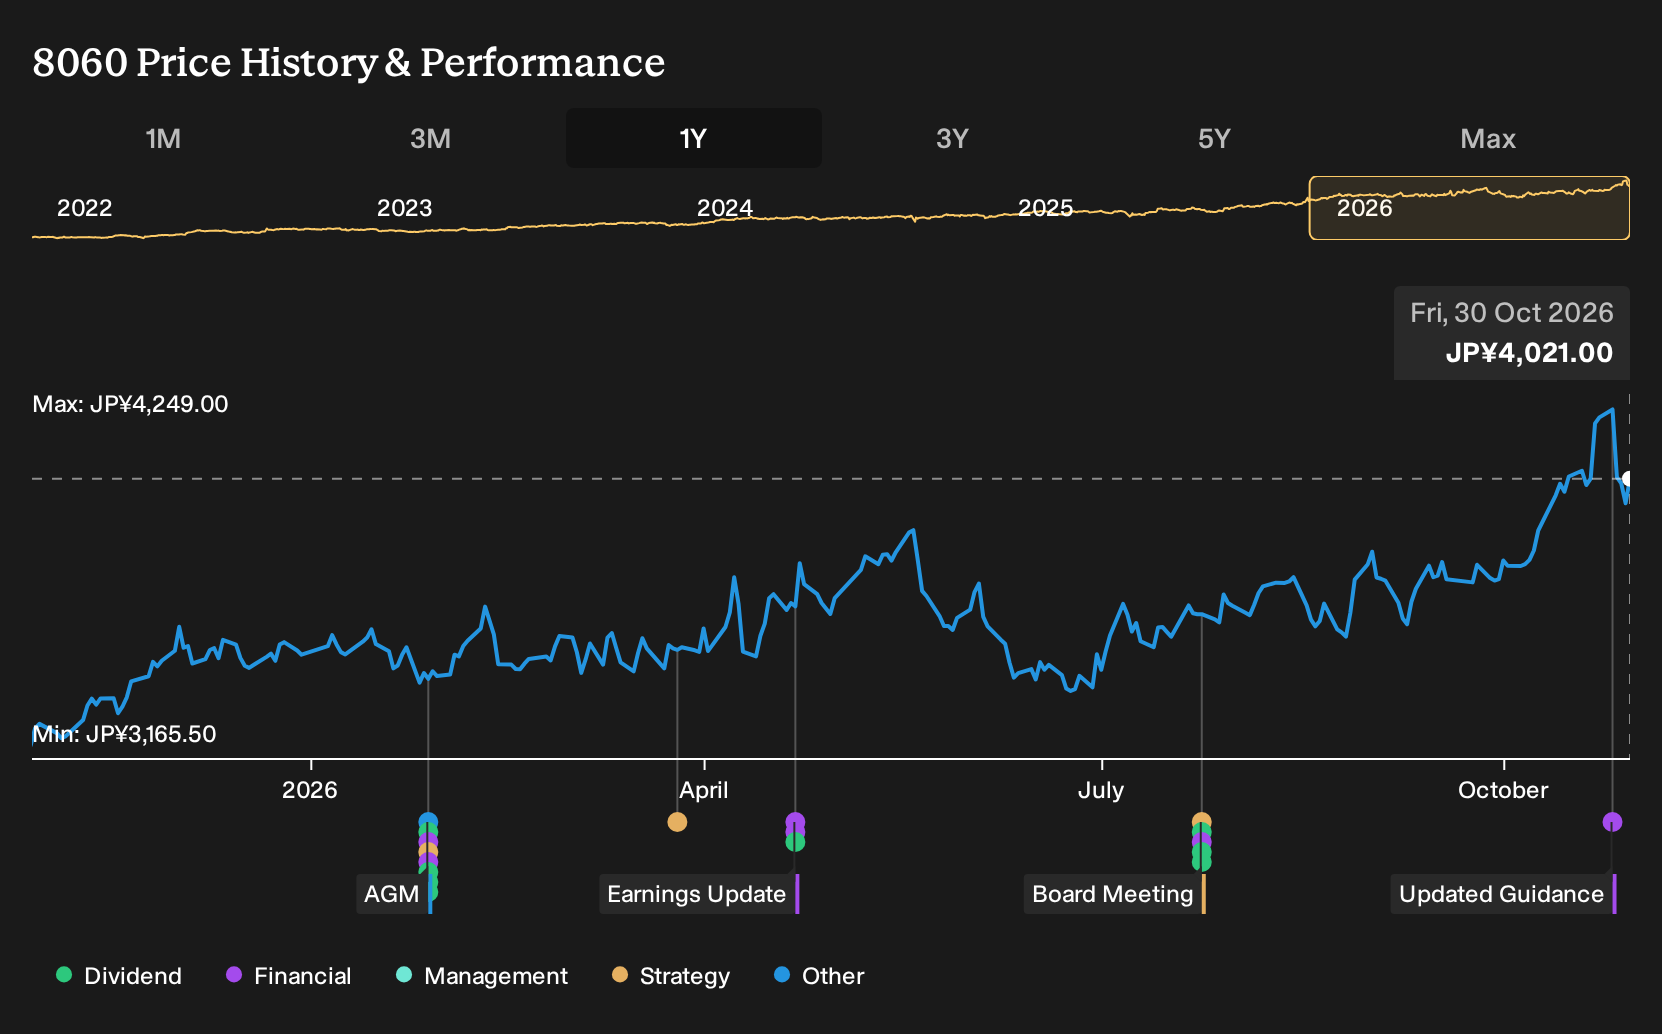
- Canon Marketing Japan issued consolidated guidance for 2026, projecting net sales of ¥685,000 million, operating income of ¥63,000 million, net income of ¥44,000 million and basic EPS of ¥211.48, following its Q3 2026 earnings update.
- The latest quarter showed higher earnings per share and net income alongside an improved trailing 12 month net margin, indicating stronger profitability from Canon Marketing Japan's mix of hardware and solutions despite ongoing structural pressure in printers and cameras.
- The focus now is on how Canon Marketing Japan's firmer profitability profile, highlighted by its improved margins, could reshape the broader investment narrative.
What Is Canon Marketing Japan's Investment Narrative?
For Canon Marketing Japan, the core belief is that a mature distributor and solutions provider can still convert a relatively modest top line into solid profits through disciplined execution. The fresh 2026 guidance, released right after the Q3 call, reinforces that message by putting concrete figures around expected net sales, operating income and earnings per share. The near term story hinges on how well management keeps squeezing efficiency out of a hardware heavy portfolio while leaning on IT services and solutions to support pricing and protect margins.
The most important swing factors remain grounded in everyday operations. Demand for printers, cameras and professional printing kit is not the easy growth engine it once was, which makes Canon Marketing Japan's mix and cost control crucial. Forecast earnings growth and recent margin trends give some support to the idea of a steady, cash generative business, yet the current P/E premium to peers and a slower expected revenue growth rate than the broader JP market keep execution risk front and center.
Even so, there is a less obvious pressure point that only really shows up once you focus on...
There's only one way to know the right time to buy, sell or hold Canon Marketing Japan. Head to Simply Wall St's company report for the latest analysis of Canon Marketing Japan's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Canon Marketing Japan research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Canon Marketing Japan. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canon Marketing Japan's overall financial health at a glance.
Looking For More Ideas Beyond Canon Marketing Japan?
If the Canon Marketing Japan story has sharpened your focus on profitability, balance sheets and income reliability, the next step is to widen the opportunity set. The Simply Wall St Screener lets you filter the market around the traits that matter most to you, so you can build a watchlist that matches your own risk and return preferences rather than someone else's template.
- If you want potential value with quality fundamentals as a starting point, scan through 14 high quality undervalued stocks that already clear basic balance sheet and cash flow hurdles.
- For readers who care most about resilience during tougher periods, filter for 24 resilient stocks with low risk scores that score well on volatility and financial risk metrics.
- When the goal is to pair strong finances with room to grow, focus on our 71 high quality undiscovered gems that still sit off most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com