


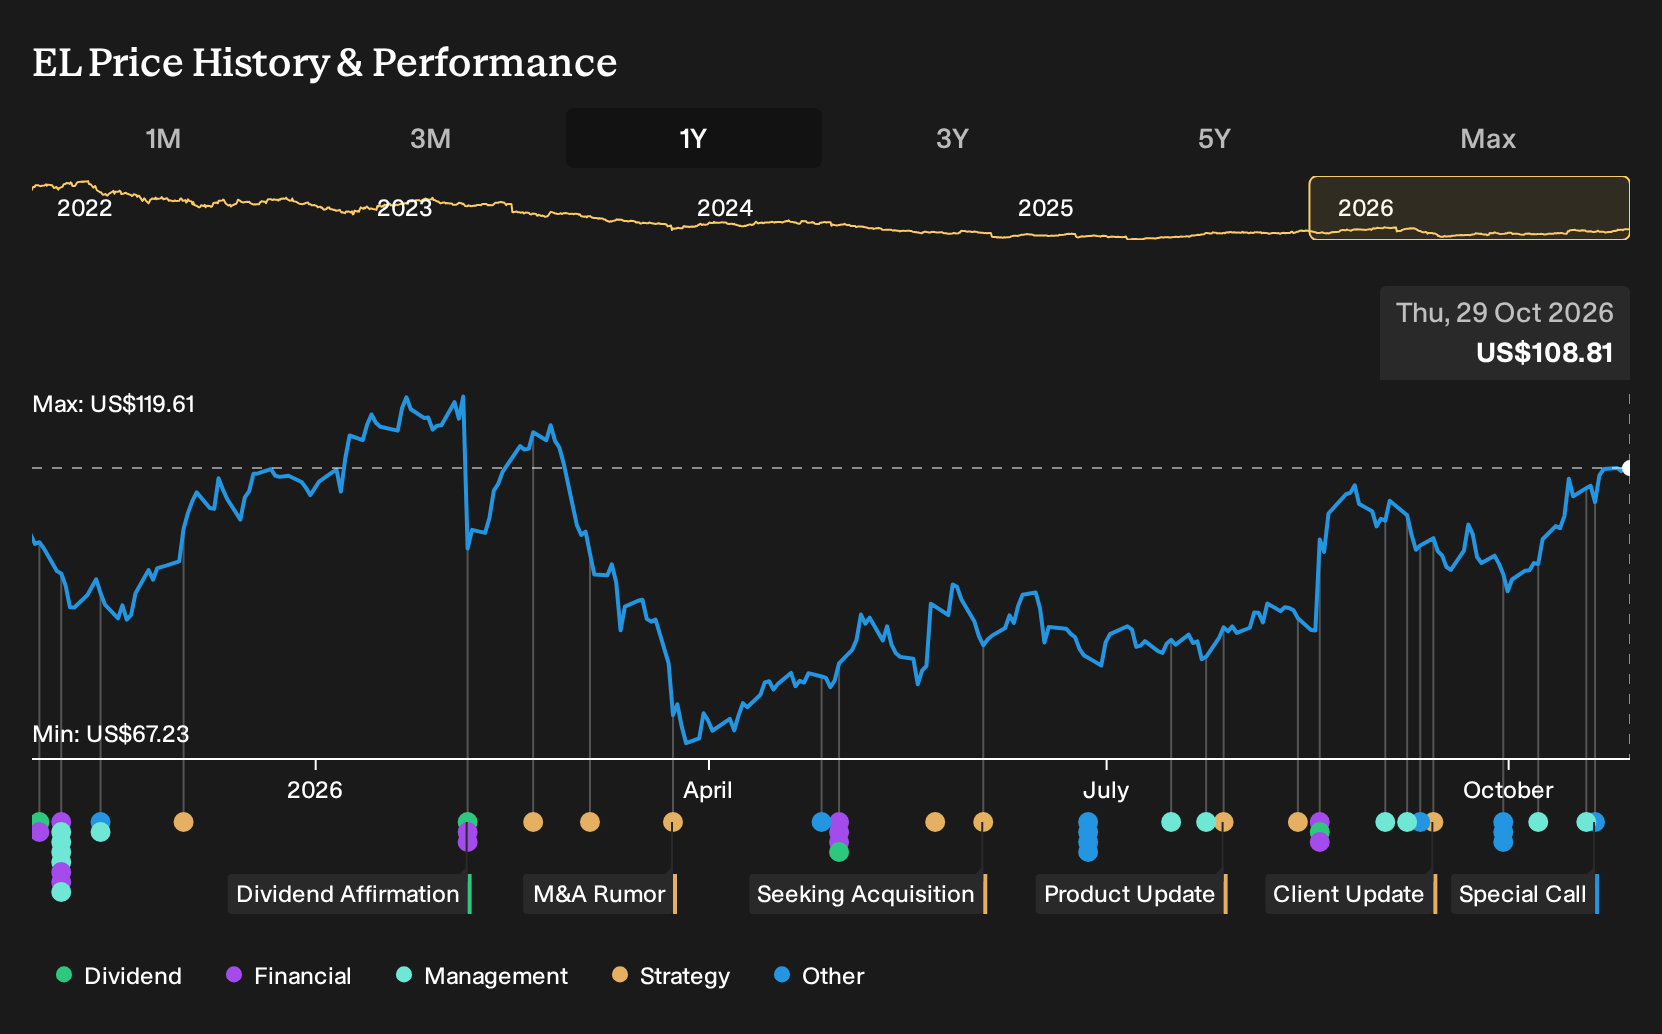
- Estée Lauder Companies announced a partnership with Microsoft to build out its cloud, data and AI stack, while also preparing for quarterly results where Wall Street expects $0.52 in EPS on $3.65b in revenue.
- In the same week, Clinique brought in Krista Lee Berger as Senior Vice President of Global Marketing, adding a marketer known for closely tying brands to culture and multi country execution.
- We will look at how Estée Lauder Companies' investment narrative is shaped by the Microsoft AI partnership and earnings expectations.
Estée Lauder Companies Investment Narrative Recap
To own Estée Lauder Companies today, you need to believe the Profit Recovery and Growth Plan and One ELC model can keep lifting margins while the reset channel mix, especially online and China, supports steadier cash generation. The most important near term catalyst sits in execution against upcoming earnings, where the market is watching whether improving profitability appears durable rather than specific to a single quarter.
The biggest immediate risk is that restructuring, including workforce and door reductions, or renewed travel retail volatility interrupts that margin story or weakens brand execution at the counter. The Microsoft AI partnership and Clinique marketing hire look additive, but neither changes those core near term swing factors on their own.
The Microsoft cloud and AI partnership is the clearest operational tie in to the current catalyst set. It plugs directly into Estée Lauder Companies One Operating Ecosystem and existing AI enabled efforts with partners like Profound, Accenture, WPP, Shopify and Meta, which are all aimed at better media spend efficiency, product development productivity and more targeted online selling.
For you as an investor, the question is whether this alliance can tighten execution around marketing returns, assortment, and personalization quickly enough to support the margin trajectory already embedded in expectations. If management delivers cleaner digital targeting and simpler internal workflows, it could help offset risks from restructuring complexity and any choppiness in travel retail or China demand.
Estée Lauder Companies' narrative projects US$17.2b revenue and US$1.5b earnings by 2029. This assumes 4.6% yearly revenue growth and an earnings increase of about US$1.3b from US$182.0m today.
Uncover why Estée Lauder Companies' fair value aligns with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on travel retail risk and more on Estée Lauder Companies' margin upside. Before the Clinique hire news, the bullish camp was already penciling in about US$17.8b of revenue and US$1.7b of earnings by 2029. You can use those richer assumptions as one reference point, then decide whether this kind of cultural marketing firepower might eventually push forecasts higher, keep them intact, or even prompt a rethink.
Explore 5 other Estée Lauder Companies fair value estimates, including one that suggests there may be as much as 17% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Estée Lauder Companies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Estée Lauder Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it straightforward to evaluate Estée Lauder Companies' overall financial health at a glance.
Looking for more Estée Lauder Companies style ideas?
If the Estée Lauder Companies story has you thinking about where else disciplined execution and clear narratives might line up, the Simply Wall St Screener can help you scan a wider field without drowning in noise.
- If capital protection ranks high for you, consider starting with 30 resilient stocks with low risk scores that score well on resilience and risk metrics.
- For investors who care most about strong balance sheets and solid foundations, filter for companies using the list of solid balance sheet and fundamentals (23 results) to see which businesses back their stories with financial strength.
- If you enjoy spotting potential early, broaden your watchlist with a 9 elite penny stocks with strong financials that may offer different risk reward profiles to larger household brands.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com