


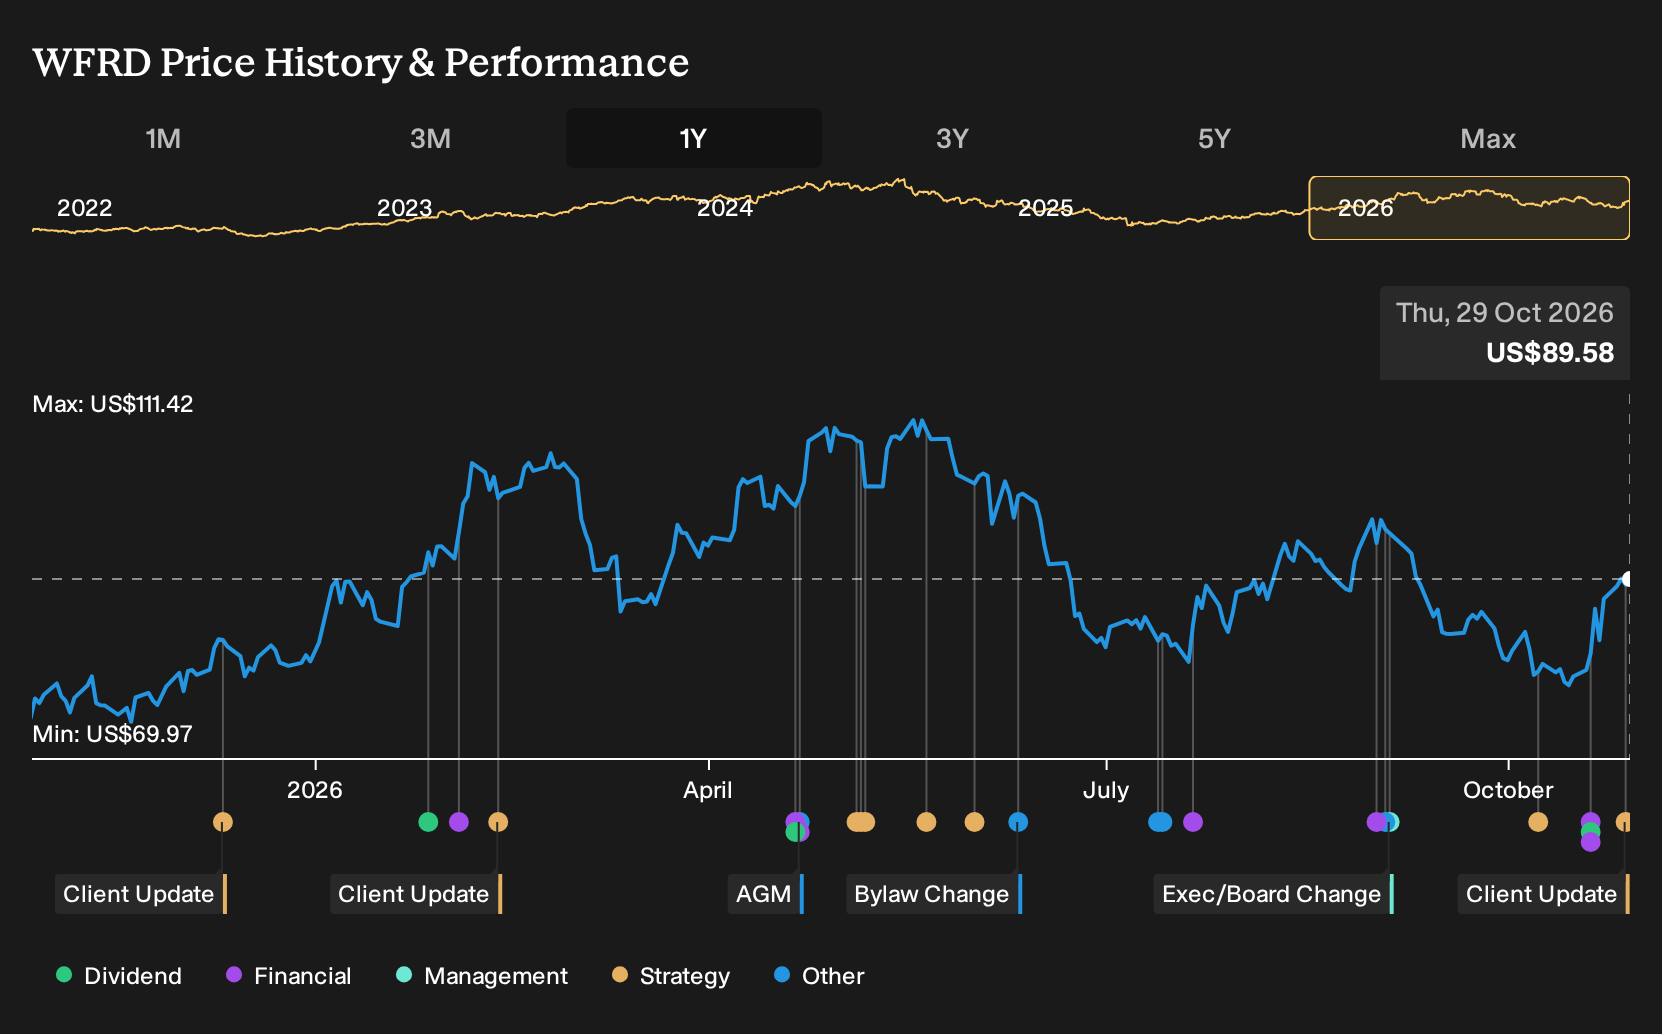
- Weatherford International redeemed all US$236 million of its 8.625% Senior Notes due 2030 at par plus accrued interest, using cash on hand and cutting annual cash interest expense by about US$20 million.
- The debt paydown reduces gross borrowings while also extending the maturity profile by roughly seven years, which tightens Weatherford International’s focus on balance sheet resilience and cash flow discipline.
- We will now look at how Weatherford International’s full redemption of its 2030 Senior Notes could reshape the company’s investment narrative.
Weatherford International Investment Narrative Recap
To own Weatherford International, you need to accept a story built on international and offshore spending, a pivot toward higher margin, technology led services and disciplined free cash flow. The latest quarter shows revenue of US$1,143 million versus US$1,232 million a year earlier, while net income rose to US$120 million from US$81 million. This keeps execution in focus rather than pure top line momentum.
The key near term swing factor is whether higher margin work and portfolio reshaping offset regional disruptions and the Saudi contract roll off. Conflict related delays in the Middle East and repeated guidance trims remain the biggest risk, because any renewed cuts could challenge confidence in Weatherford International’s operating trajectory.
The Junín 5 award in Venezuela looks most relevant right now. It puts Weatherford International’s integrated model to work across drilling, workovers and lifecycle services in a country where it already has local experience. That kind of contract leans directly into the multiyear offshore and international spending theme that underpins the equity story.
Execution on Junín 5 will matter for both catalysts and risk. Strong delivery could help offset softness tied to Middle East disruptions and the Saudi LSTK roll off, reinforcing the shift toward technology rich, integrated work. Any operational hiccups or country risk complications would cut the other way and could feed into future guidance caution.
Weatherford International's consensus setup points to US$5.3b in revenue and US$581.6 million in earnings by 2029, built on 3.8% yearly revenue growth and an earnings increase of about US$215.6 million from the US$366.0 million reported today.
Uncover why Weatherford International's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts lean hard into country risk around Venezuela rather than the Junín 5 upside. They were penciling in roughly US$5.3b of revenue and about US$607.8 million of earnings by 2029 and still only reached a US$93.0 target. Use that gap as a prompt to compare several viewpoints before considering how this new contract might influence the Weatherford International story in your own assessment.
Explore 5 other Weatherford International fair value estimates, including one that suggests it could be worth just $93.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Weatherford International research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Weatherford International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weatherford International's overall financial health at a glance.
Looking for more investment ideas beyond Weatherford International?
If Weatherford International’s balance sheet reset has you thinking about portfolio upgrades, it can help to line it up against other companies with different risk and income profiles. The Simply Wall St Screener gives you a quick way to move from one story to a full watchlist of candidates that fit your own return and volatility preferences.
- If capital preservation sits high on your priority list, consider starting with a 30 resilient stocks with low risk scores that have shown resilience based on their risk profiles.
- For investors hunting for stronger fundamentals and cleaner finances, you may prefer to sift through a list of solid balance sheet and fundamentals (23 results) to compare leverage, cash buffers and asset strength side by side.
- Those hunting for mispriced quality can cast a wider net across a 18 high quality undiscovered gems that combine fundamental strength with relatively limited market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com