


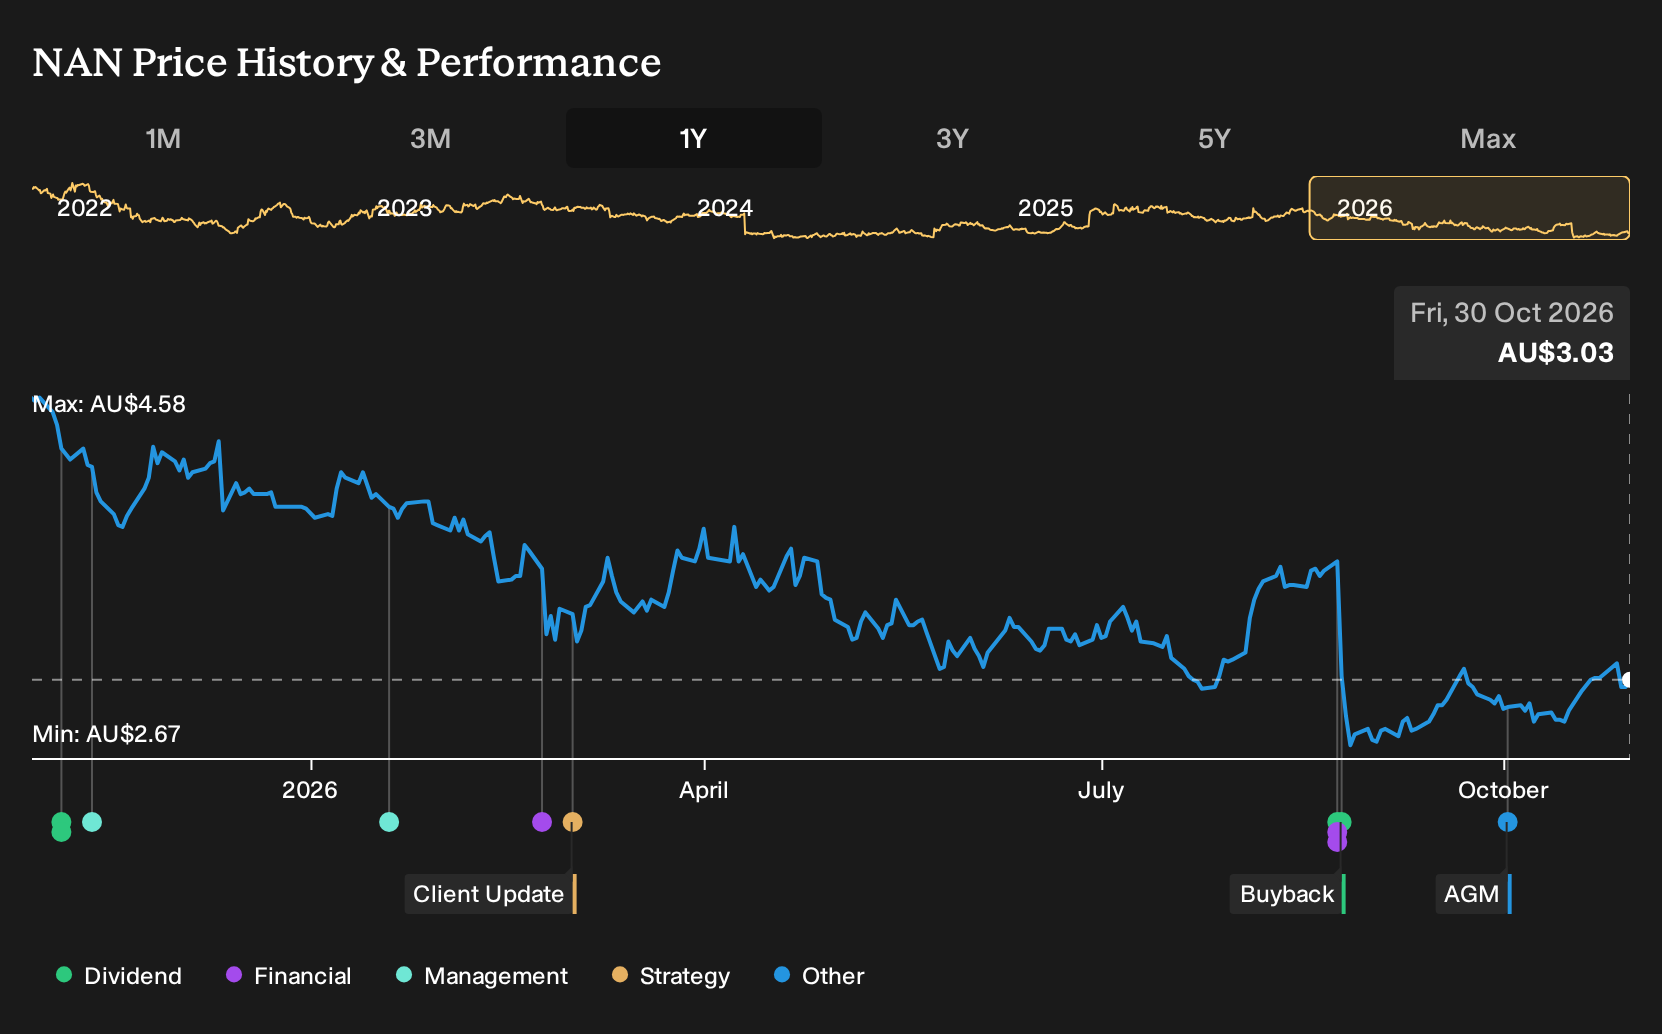
Nanosonics’ latest half year update on 24 August 2026 showed total revenue of A$101.662 million and net income of A$8.192 million, with net margin easing to 8.1%. Holding Nanosonics over the past year would have meant a 33.8% loss, including dividends. If you had been weighing up a purchase back on 30 October 2025, how should those earlier bullish and bearish expectations be judged in light of this margin setback?
The easy part of this move is behind Nanosonics. Zero in on 1 high quality undervalued stocks for companies trading below our estimates.
The Two Nanosonics Stories Investors Had To Weigh
The shares cost A$4.56 at the start of the period, so anyone looking at Nanosonics then had to decide which future felt more plausible.
The bullish narrative pointed to a Fair Value of A$6, a price implied by expectations of faster revenue expansion, supported by assumptions of a 13.8% annual growth rate and profit margins rising from 10.4% to 19.6% by 2028.
The bearish view argued for a Fair Value of A$3.75, based on concerns that tighter hospital budgets and tech substitutes could slow demand, with assumptions of 6.7% annual growth and margins easing to 7.6% by 2028.
What The Results Changed For The Nanosonics Debate
The clearest data point for Nanosonics is that total revenue moved from A$105.033 million in H2 2025 to A$101.662 million in H2 2026, while net income slipped from A$10.916 million to A$8.192 million. Net margin moved from 10.4% to 8.1%. That pattern challenged the bullish expectation of firming profitability and offered more support to the cautious case. The period still did not close the book on either story.
The episode turned on one key assumption, that net margin would move higher. When you assess another company, track whether margin trends line up with the story you are being sold and compare that against several reporting periods, not just a single half year.
What Nanosonics’ Lower Price Now Asks You To Believe
Nanosonics trades at A$3.03, with the selected Narrative’s Fair Value sitting above that level rather than below it. That view leans heavily on the idea that trophon remains a strong cash engine while CORIS develops into something more meaningful.
For that Narrative to hold, a buyer today would need to believe CORIS can shift from controlled release to broad commercial use without undercutting group profitability.
"The current share price, together with the recent broker upgrade and ongoing buybacks, suggests the market is still discounting Nanosonics' cash generative trophon-only business and the potential for CORIS to become a second earnings platform."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Looking One Step Beyond Nanosonics
Nanosonics sits in hospital equipment budgets that rarely move in isolation. When one tool earns space on a trolley, others often follow.
Those same buyers also wrestle with how procedures are actually performed. Many want surgery that is less invasive, more precise and easier to repeat safely.
Another specialist answers that need with robotic systems and digital training. Surgeons can rehearse cases, review recordings and compare techniques across many procedures.
Hospitals get a platform that keeps generating instrument and service demand. If that appetite for minimally invasive care keeps spreading, this separate supplier could matter more to your watchlist.
One Narrative has already put a figure on it. → Uncover the company trading 16% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com