


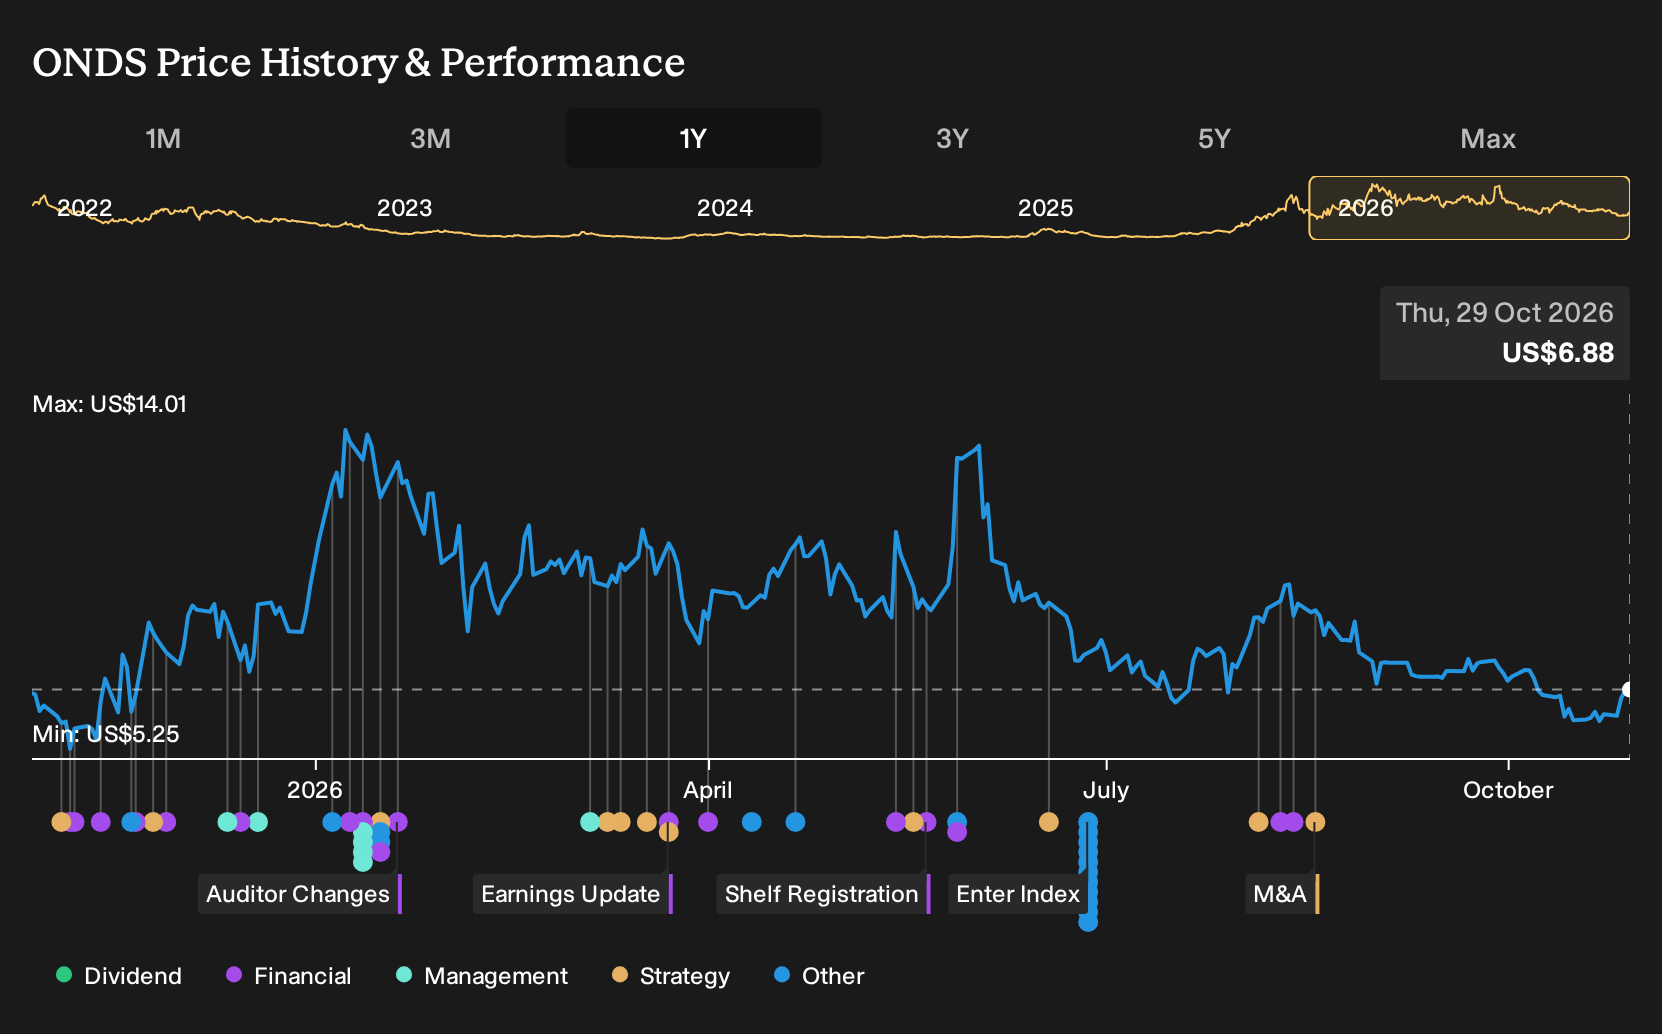
- Ondas has reported a large order book of about US$757 million at June 30 and more than US$270 million in additional orders since then, alongside new counter-drone offerings such as Sentrycs Ranger and Dronebuster REACH and contracts aligned with FEMA’s expanded US$250 million counter-UAS grant program.
- The alignment of Ondas’ aerial security and counter-drone portfolio with federal grant funding and deployment at events such as the 2026 FIFA World Cup provides the business with clearer demand visibility and highlights how public safety agencies might become a more meaningful, longer-term customer base.
- This article examines how Ondas’ investment narrative is affected as counter-drone demand evolves through FEMA grants and public safety contracts.
Scan how Ondas fits into the broader defense and security theme by comparing it with a curated 96 robotics and automation stocks that are also targeting autonomous systems and counter-drone tech.
Ondas Investment Narrative Recap
To own Ondas, you need to believe the current US$757 million order book, plus more than US$270 million in new orders, can translate into durable, profitable programs rather than one off wins. Management still runs the operation at a loss, so the big near term swing factor is whether revenue converts into cash flow without eroding gross margins.
The clearest short term catalyst is execution against 2026 guidance, including management’s aim for adjusted EBITDA to improve through the year and turn positive in the fourth quarter. The main risk sits on the other side of that same coin. If deliveries slip or costs stay high, the path to self funded growth and any future funding flexibility gets tougher.
Among the recent announcements, the fixed price US$99,000 Sentrycs Ranger offer aimed at FEMA backed counter drone budgets is the one that ties most directly to Ondas’ current story. It connects the firm’s aerial security suite to a defined US$250 million federal grant pool and to customers that often scale slowly but stick around once systems are embedded.
For you as a shareholder, the interest here is how a ground level, catalog style product could support the broader order book. Consistent Ranger orders from state and local agencies, if they materialise, would help smooth revenue between larger defense contracts. The operational test is simple. Ondas needs to ship these units efficiently, support them with the promised three year maintenance, and keep margins from getting compressed as volumes change.
Ondas' current analyst narrative points to revenue of US$1.6b and earnings of US$31.0 million by 2029, based on a forecast revenue growth rate of 110.2% per year and a projected earnings decline of US$54.8 million from earnings today of US$85.8 million.
Uncover how Ondas' fair value indicates a 174% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One more optimistic thread around Ondas focuses on earnings potential rather than near term losses. The most bullish analysts were sketching out revenue of about US$2.2b and earnings of roughly US$242.3 million by 2029 before this FEMA linked counter drone news. That is a very different story from the consensus US$1.6b and US$31.0 million view. You can treat this as a reminder that reasonable people can look at the same backlog, the same Sentrycs Ranger launch and the same order flow, and then reach very different conclusions. It is worth exploring both sets of expectations and asking how this fresh counter UAS development might affect those forecasts over time.
Explore 8 other Ondas fair value estimates, including one that suggests a potential 279% increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Ondas research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Ondas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ondas' overall financial health at a glance.
Looking For More Investment Ideas Beyond Ondas?
Once you have a view on Ondas, it can help to widen the lens and compare it with other opportunities that match your risk tolerance, income needs, and balance sheet preferences.
- For investors who want to focus on stability first, screen for companies with strong finances and low leverage using a list of solid balance sheet and fundamentals (23 results) that can help you filter out weaker balance sheets quickly.
- If you are hunting for mispriced opportunities, use a 30 high quality undervalued stocks that highlights businesses where fundamentals and valuation metrics look out of sync.
- Income focused investors who care about steady cash returns can zero in on a 7 dividend fortresses that surfaces stocks with higher yields and robust payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com