


- Cisco Systems has rolled out a broad upgrade to its AI focused 360 Partner Program, Cisco IQ platform, and Cloud Control portfolio, including new quantum resilient Wi Fi 7 access points, Model Foundry services, expanded incentives, and deeper ThousandEyes and MCP integrations.
- The scale of Cisco IQ, with more than 16,000 customers and visibility into about 20 million devices since April 2026, shows how deeply embedded Cisco’s telemetry and AI operations layer has become in customer networks.
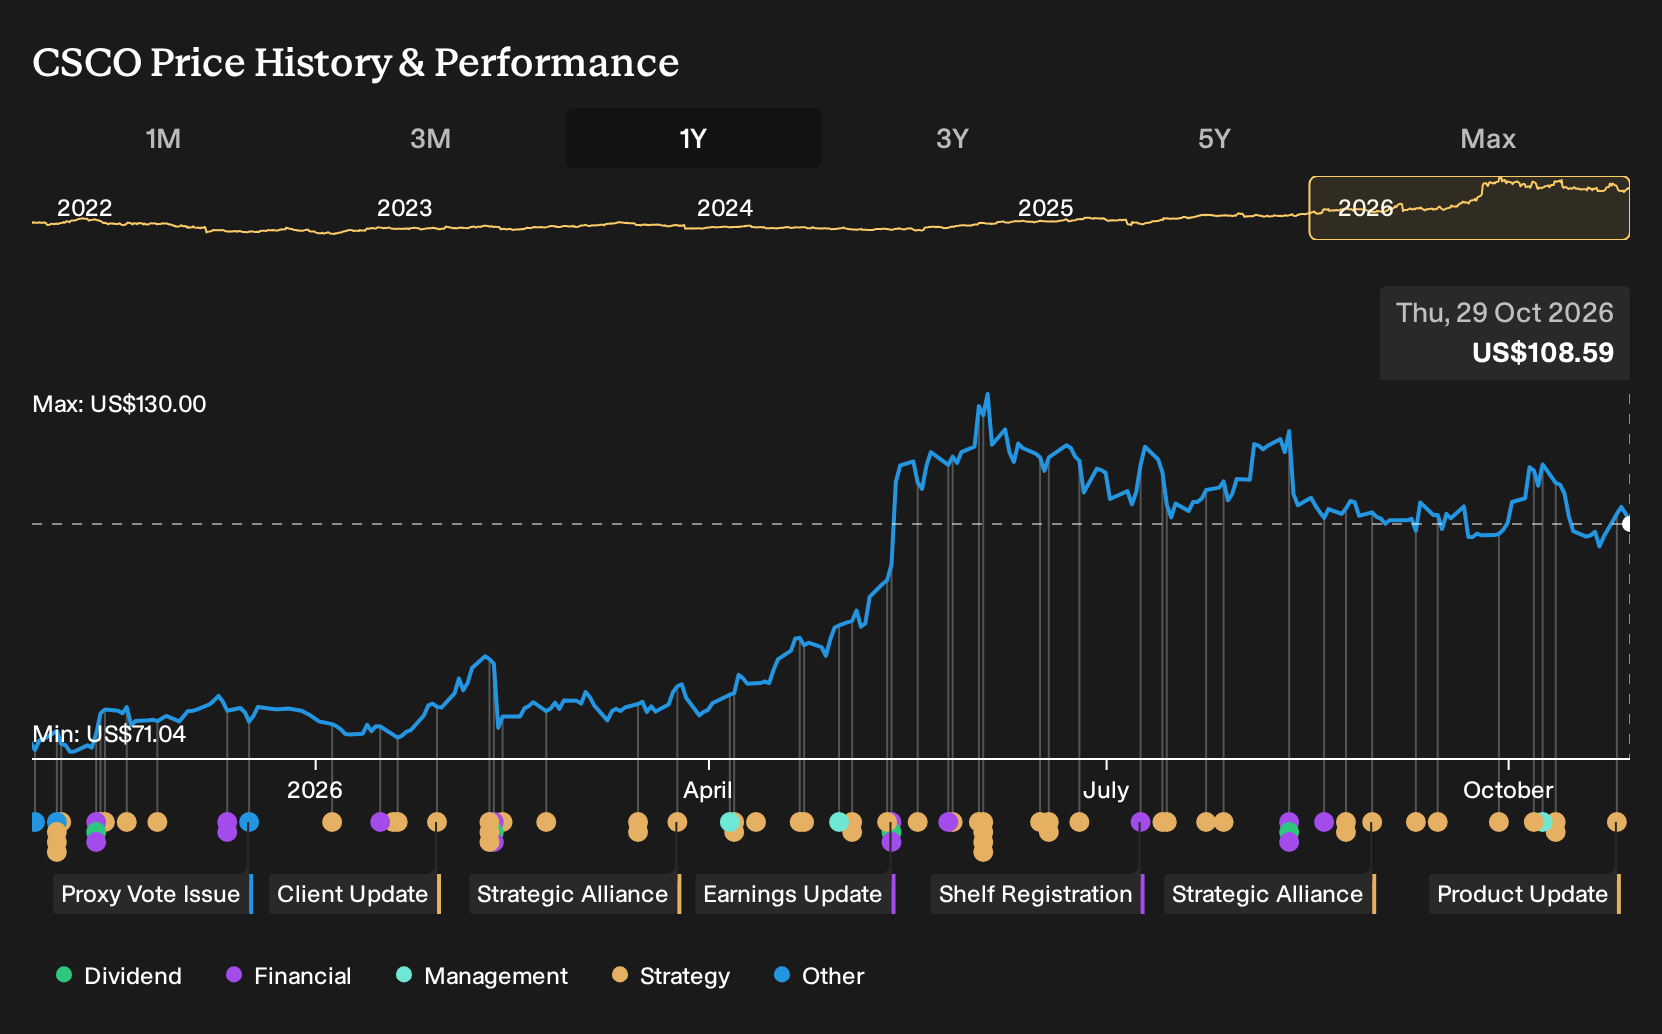
- This article will examine how Cisco Systems’ AI infrastructure initiatives and expanded partner incentives may influence the company’s broader investment narrative.
Scan how Cisco Systems fits into the AI buildout cycle, then line it up against 54 AI infrastructure stocks.
Cisco Systems Investment Narrative Recap
Cisco Systems requires you to believe that AI driven networking, security, and observability can offset hardware mix pressure and keep earnings power resilient. The short term swing factor is how efficiently it converts US$9.3b of FY26 hyperscale AI infrastructure orders, and the guided US$7.5b of FY27 AI infrastructure revenue, into sustainable margins.
The partner and AI platform refresh slightly strengthens that near term setup. Tighter integration across Cisco IQ, Cloud Control, and ThousandEyes could support adoption and post sale expansion. The biggest immediate risk still sits in gross margin pressure from a heavier hardware mix and memory costs, which could mute the benefit of higher AI and security volumes.
The expanded 360 Partner Program and Cisco IQ for Partners looks most relevant here. This package ties richer incentives, AI assisted selling tools, and Model Foundry access to the same AI infrastructure cycle that delivered the US$9.3b of FY26 hyperscale orders. It is aimed at helping partners attach more software, observability, and secure networking to those deployments.
For an investor watching catalysts, that combination matters. If partners use the new Cisco IQ Adopt incentives, MCP servers, and Cloud Control integration to grow telemetry based services, Cisco Systems could deepen recurring software and support revenue around AI hardware projects. Execution risk sits in whether partners actually engage with these tools and whether margin headwinds soften as mix shifts toward higher value software and security.
Cisco Systems' narrative projects US$83.4b revenue and US$20.1b earnings by 2029. This setup assumes 9.6% yearly revenue growth and an earnings increase of about US$6.8b from US$13.3b today.
Uncover how Cisco Systems' fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view zooms in on concentration risk. Bearish analysts worry that Cisco Systems leans too heavily on a few hyperscalers, even with US$9.0b of expected AI orders in FY26 and at least US$6.0b of AI hyperscale revenue in FY27. Before this partner news, they were working off slower top line assumptions, closer to 7.2% annual revenue growth and US$19.3b earnings by 2029, and a lower 28.8x P/E. That is a more cautious script than the consensus, and it shows how far opinions can spread. Use this announcement as a prompt to compare those stretched views and decide which story feels closer to your own expectations.
Explore 5 other Cisco Systems fair value estimates, including one that suggests it could be worth just $110.56.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cisco Systems research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for Cisco Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cisco Systems' overall financial health at a glance.
Looking for more investment ideas beyond Cisco Systems?
Once you have a handle on Cisco Systems, it can help to set it alongside a broader watchlist built from clear, data driven filters.
- If you want income to play a bigger role in your plan, scan a curated set of companies with steady payouts through 7 dividend fortresses.
- For investors focused on quality at a sensible entry point, compare Cisco Systems with a wider group of attractively priced opportunities via 30 high quality undervalued stocks.
- When balance sheet strength is non negotiable, build a shortlist of resilient businesses using the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com