


Why Laureate Education’s reaffirmed outlook matters now
Laureate Education (LAUR) just reaffirmed its 2026 earnings guidance, anchoring expectations for roughly US$1.92b to US$1.93b in revenue and setting a US$546 million to US$556 million range for the fourth quarter.
That update comes alongside fresh third quarter numbers, where sales were US$485.09 million and net income was US$101.22 million. This gives investors a clearer snapshot of how current trading compares with the full year targets.
The reaffirmed outlook lands after a busy stretch for Laureate Education, including strong third quarter results and a US$150 million increase to its share repurchase program. Yet the share price has drifted, with a 7 day share price return of 7.17% down against an 8.11% gain year to date and a much stronger 3 year total shareholder return of about 19x, which signals that longer term momentum has been far more resilient than recent trading suggests.
Spot similar higher education and consumer services stories that could be setting up their next move with our hand picked 18 high quality undiscovered gems.Laureate Education appears to be a solid operator with reaffirmed guidance, new campus investment and an expanded buyback program, yet the share price has cooled in recent months. Is that strength already fully priced in?
Most Popular Narrative: 13% Undervalued
Laureate Education last closed at $36.01, while the most followed narrative pegs fair value near $41.21, implying a meaningful discount that hinges on how well management turns online scale and buybacks into future cash returns.
The main thing that has to go right is that Laureate Education continues to scale high margin online offerings, execute its multiyear campus buildout, and embed AI tools across marketing and student delivery while still achieving the targeted margin expansion.
Online degree offerings that are priced about 40% below face to face programs but still carry contribution margins in the mid 50s with very limited capital needs support a mix shift toward higher return on invested capital and the potential for higher consolidated net margins and earnings.
See why 21 investors see Laureate Education as 13% undervalued.
Result: Fair Value of $41.21 (UNDERVALUED)
Still, Laureate Education’s narrative could be upset if new campuses struggle to fill capacity, or if any reset in valuation estimates pulls expectations lower.
Find out about the key risks to this Laureate Education narrative.
Another View: What Laureate Education’s P/E Is Really Saying
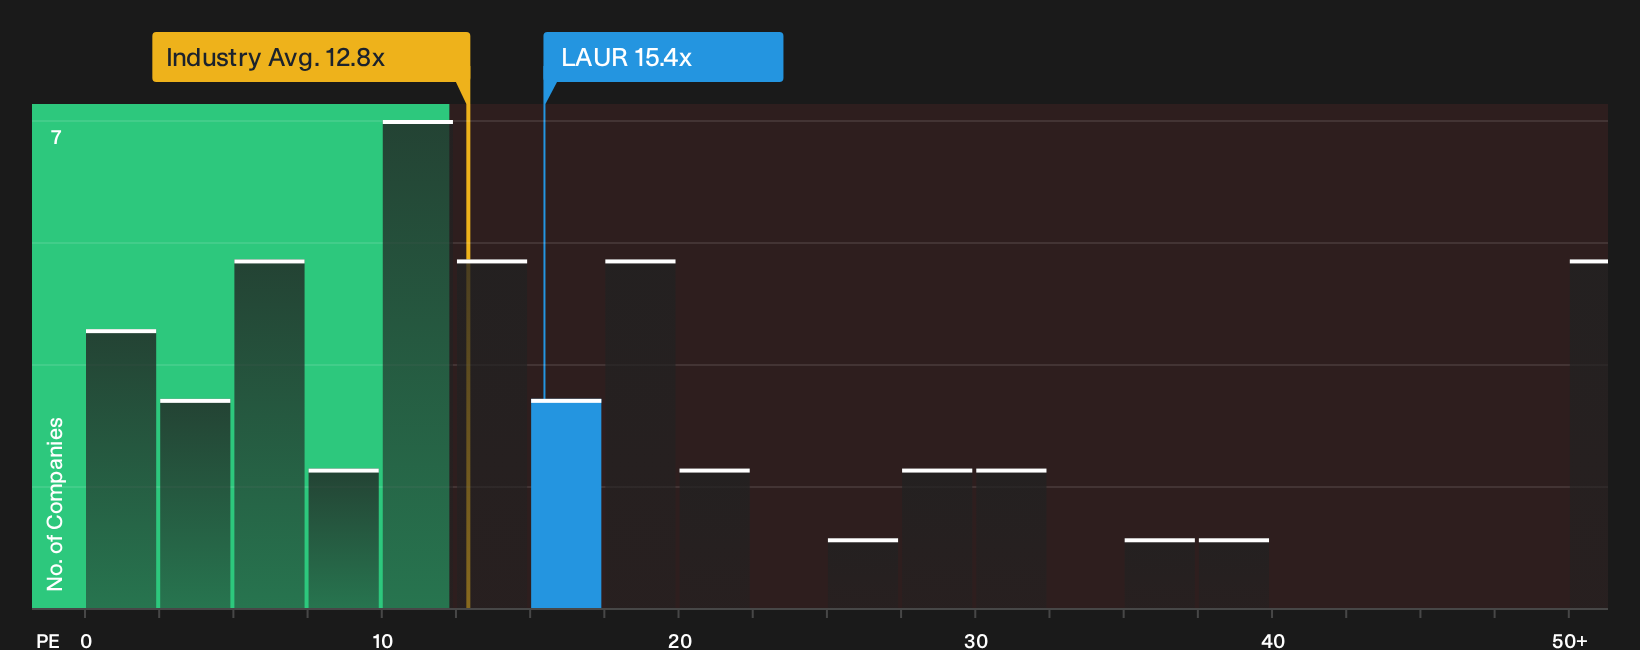
A different lens tells a more cautious story. Laureate Education trades on a P/E of 15.4x, above the US Consumer Services industry at 13.2x, yet close to the 15.5x peer average and below its 17.2x fair ratio. The market is paying up, but not excessively. Is that premium comfort or risk for you?
See what the numbers say about this price in more detail with our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all sounds optimistic, do not let the headline view be your only guide. Instead, check the underlying numbers and assumptions yourself. To see which strengths investors are already focused on, review the 3 key rewards.
Looking for more investment ideas beyond Laureate Education?
Do not stop with one stock. Use the tools available and let data filter opportunities for you, so you are not guessing what to research next.
Line up potential higher quality bargains by scanning a focused group of 30 high quality undervalued stocks that already pass key fundamental checks.
Target resilient balance sheets and steadier financial profiles by reviewing a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio.
Stack potential income ideas by screening for 7 dividend fortresses that combine higher yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com