


Madrigal Pharmaceuticals has delivered very large gains over the past five years, yet the recent pullback in 2026 leaves a practical question for anyone looking at the stock today. Is the current share price still in line with what Madrigal's sales can reasonably support?
- The stock has risen about 354% over 5 years. As a result, a lot of future revenue expectations are already embedded in the price and need to be weighed carefully.
- New data on Rezdiffra being presented at AASLD's The Liver Meeting 2026 may support long term sales potential in metabolic dysfunction-associated steatohepatitis, which feeds directly into how much investors are willing to pay per dollar of revenue.
- There is a second opinion on Madrigal Pharmaceuticals worth weighing. See what analysts think Madrigal Pharmaceuticals's shares could be worth.
The issue now is whether Madrigal Pharmaceuticals' current market value is justified by its sales base and how investors are pricing that revenue stream.
If you are weighing Madrigal Pharmaceuticals against other ways to play this theme, it can help to compare its story with the companies in 36 healthcare AI stocks.
Is Madrigal Pharmaceuticals a Bargain on Sales?
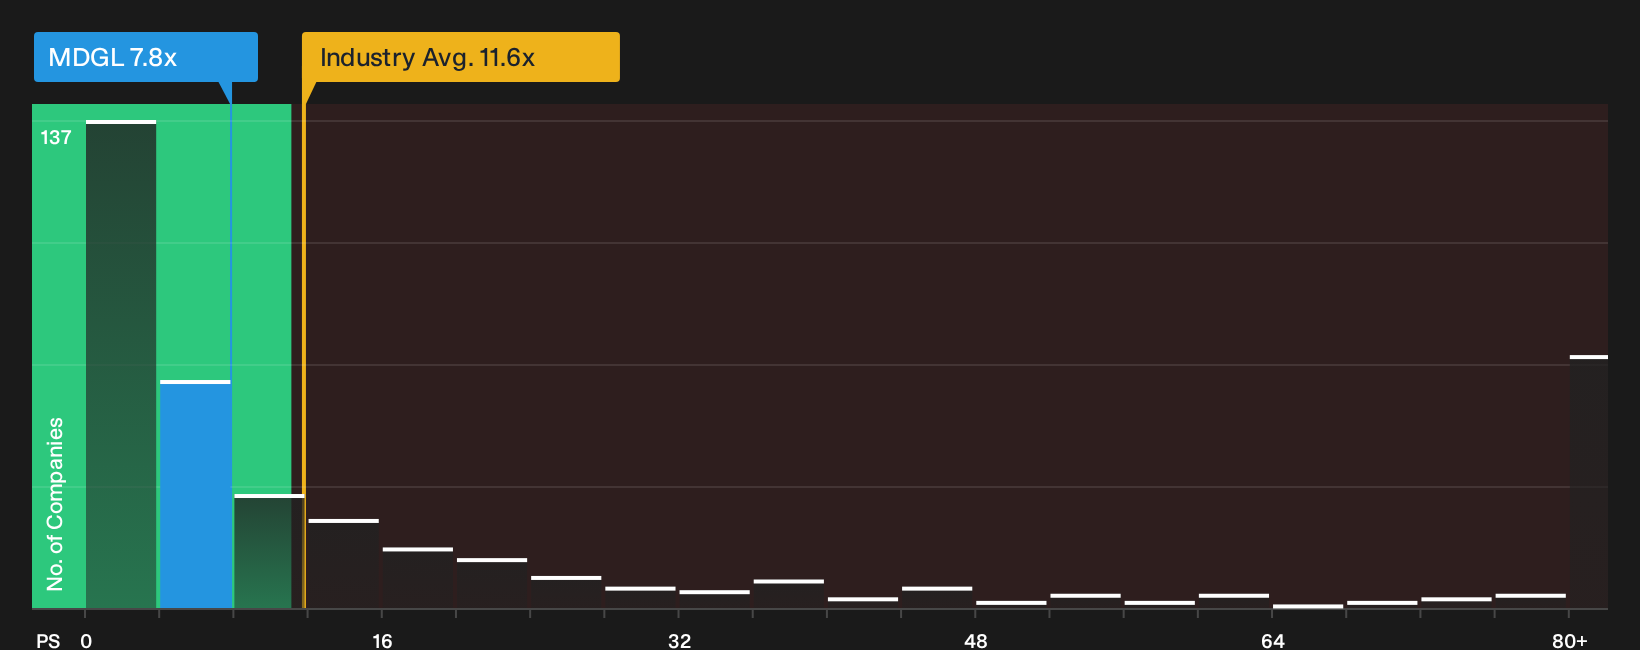
P/S is usually the cleaner yardstick for Madrigal Pharmaceuticals because earnings are still loss making and investors are really paying for the revenue line tied to Rezdiffra. On this measure, the stock trades at a P/S of 7.8x, which sits below the biotech industry average of 11.6x and well under the peer group around 27.6x.
The valuation model that adjusts for Madrigal Pharmaceuticals' growth profile, margins, size and risks points to a higher P/S as a more tailored reference point, so the current 7.8x reading screens as undervalued against that yardstick. Because the upcoming AASLD Liver Meeting data keeps attention on how durable Rezdiffra demand could be, this lower multiple relative to both the custom fair level and peers frames a set of expectations that investors may want to test against their own revenue assumptions. Explore the numbers behind Madrigal Pharmaceuticals's P/S valuation.
The Madrigal Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Madrigal Pharmaceuticals pick up where the valuation puzzle leaves off, by mapping out which future paths for growth, margins and earnings would need to hold for the stock to end up worth a lot more or a lot less than it is today on the market. Where a single ratio or model offers one neat output, these stories unpack the future it relies on so you can watch how reality lines up with that script over time on the Community page.
One of the top community narratives on Madrigal Pharmaceuticals: 19% undervalued
"Heavy reliance on Rezdiffra as a single asset means future performance is acutely vulnerable to either disappointing long-term outcomes in ongoing trials…"
Discover why this Narrative puts Madrigal Pharmaceuticals at 19% undervalued.
One more Madrigal Pharmaceuticals check belongs beside the valuation story
Madrigal Pharmaceuticals also triggers specific risk checks in the research, and those red flags can change how you weigh everything discussed so far. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com