


Heightened expectations around OPENLANE (OPLN) are building after recent analyst activity flagged stronger earnings prospects ahead of the company’s upcoming quarterly release, where markets anticipate year-over-year growth in both profit and sales.
Recent trading reflects that optimism. The share price is up 11.99% over the past month and 32.69% year to date, while total shareholder return over one, three and five years of 47.43%, 174.12% and 175.87% respectively points to momentum that investors are now testing against OPENLANE’s next earnings update.
Scan how OPENLANE’s earnings momentum compares with other potential breakouts by reviewing our hand picked list of 18 high quality undiscovered gems in similar corners of the market.
That kind of run in OPENLANE, against a backdrop of improving earnings expectations but still reported losses, can reflect either a healthier business emerging or investors leaning harder into sentiment. The valuation now has to carry that story.
Most Popular Narrative: 16% Undervalued
OPENLANE’s most followed narrative pegs fair value at $46.22, compared with the recent $38.76 close, so the story leans toward potential upside that depends on operating scale and capital allocation aligning with expectations.
The accelerating move by dealers from physical auctions to OPENLANE’s digital marketplace, highlighted by roughly 31% growth in U.S. dealer to dealer volumes while physical dealer auctions were slightly negative, points to further mix shift toward higher volume digital transactions that can support revenue and adjusted EBITDA.
See why 1 investors see OPENLANE as 16% undervalued.
Result: Fair Value of $46.22 (UNDERVALUED)
Still, the OPENLANE story can break if competition squeezes digital auction pricing or if high net debt and extra spending reduce future earnings power.
Find out about the key risks to this OPENLANE narrative.
Another View: What OPENLANE’s Sales Multiple Is Telling You
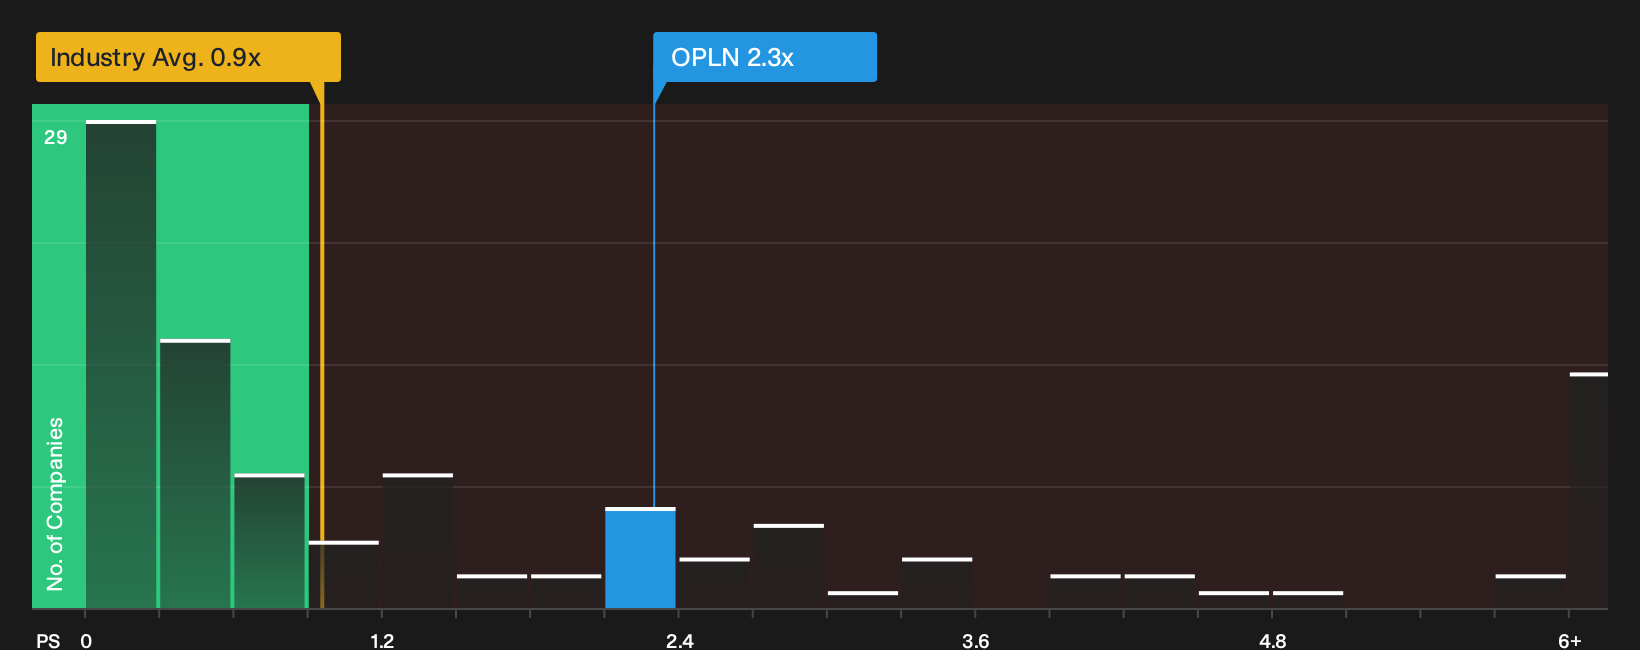
Our DCF work points to OPENLANE trading below estimated future cash flow value, yet the P/S ratio tells a different story. At 2.3x sales versus 1x for the wider US Commercial Services group and 1.7x for peers, the stock prices in richer expectations than both. The fair ratio sits at 1.9x, which would imply less upside and more valuation risk if sentiment cools.
That gap between the DCF output and a richer sales multiple leaves investors weighing which signal to trust most: the cash flow math or the market’s higher revenue-based yardstick. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around OPENLANE is split between excitement over potential upside and concern about the risks already on the radar. Act quickly, review the underlying data for yourself, and weigh both sides of the story by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond OPENLANE?
Do not stop with OPENLANE. Put fresh ideas on your radar by using focused screens that surface different types of opportunities other investors may be ignoring.
- Target potential mispricings by scanning a curated pool of companies that combine quality fundamentals with appealing entry points through the 30 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that offer meaningful yields in the 7 dividend fortresses.
- Dial down portfolio stress by concentrating on companies that show stronger financial resilience using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com