


ADT (ADT) drew investor attention after Thrive Holdings agreed to acquire the security provider in an all-cash deal valuing the business at about US$15.3b in enterprise value.
The takeover offer has triggered a sharp re-rating in ADT’s shares, with a 1-day share price return of 33.2% and a 60.8% 30-day share price return, as investors price in the US$10 deal value and reduced uncertainty around the business.
Scan other potential takeover or re-rating candidates with the 18 high quality undiscovered gems that share some of ADT’s mix of scale, recurring revenue and under-the-radar appeal.
Bulls see ADT’s 33% jump as proof the US$10 bid barely catches up to its cash flows. Bears see full value already on the table. Which case do the current numbers support as the deal math gets tested?
Most Popular Narrative: 20.2% Overvalued
On the most followed valuation narrative, ADT screens on the expensive side, with a fair value of $8.21 sitting below the last close at $9.87 and the agreed $10 bid. This puts the takeover premium ahead of what the model assigns to the security provider on a standalone basis.
Valuation Margin of Safety: At ~7.5x forward earnings and a TEV/EBITDA under 5x, the terminal decline narrative is already fully priced in. The downside risk is cushioned by the ~3.3% dividend yield and management's willingness to execute concurrent share repurchases.
See why 1 investors see ADT as 20% overvalued.
Result: Fair Value of $8.21 (OVERVALUED)
Still, the thesis can crack if ADT mishandles its heavy debt refinancing or if newer offerings like ADT Blu underperform against entrenched DIY rivals.
Find out about the key risks to this ADT narrative.
Another View: ADT Looks Cheap On Cash Flows
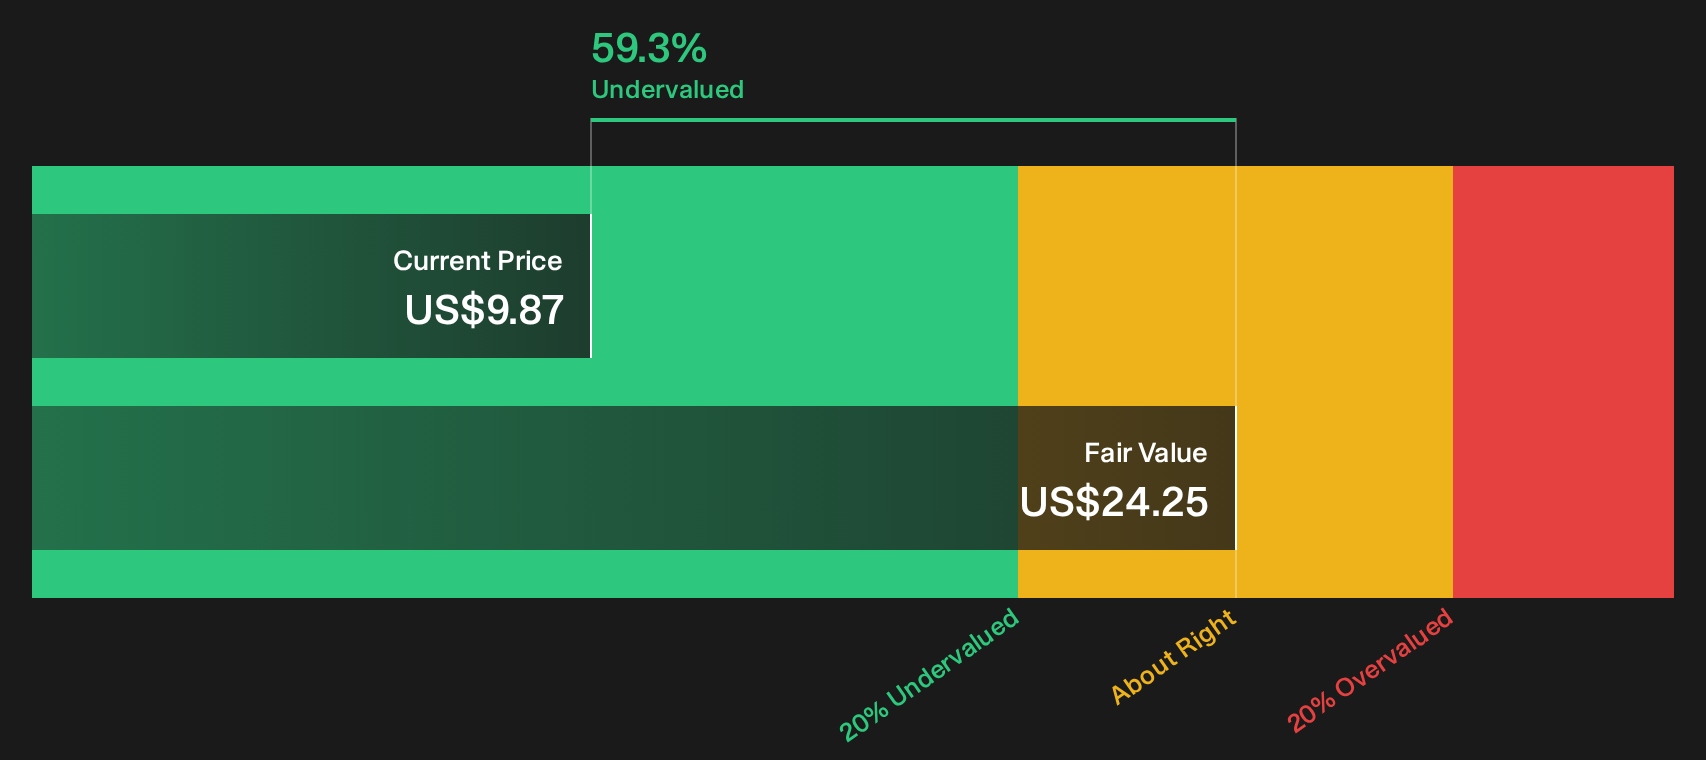
That first narrative leans on a fair value of $8.21, yet our DCF model tells a very different story for ADT. On that framework, the stock at $9.87 screens as trading 59.3% below an estimated future cash flow value of $24.25, which lands firmly in undervalued territory. Which signal do you trust more: the earnings multiple or the long term cash generation math?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages across ADT’s valuations make this a judgment call rather than a straightforward opportunity. Act while the deal debate is fresh and anchor your own view with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond ADT?
If ADT has you thinking about where pricing gaps and hidden stories might sit elsewhere, do not stop with one security when the data can work harder for you.
- Target potential mispricings in quality companies by scanning the 30 high quality undervalued stocks that balance strong fundamentals with attractive valuations.
- Prioritise resilience and capital protection by checking the 30 resilient stocks with low risk scores that keep risk scores tight without giving up financial quality.
- Spot dependable cash generators by reviewing the 7 dividend fortresses that pair 5%+ yields with an emphasis on stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com