


A new California class action has put Darden Restaurants (DRI) under a legal spotlight, with claims tied to wages, breaks, and expense reimbursement raising fresh questions about employment practices and potential financial exposure.
Darden Restaurants has attracted fresh attention, with the California class action arriving just as the share price trades around US$220.48 and short term momentum stays positive. This includes a 13.0% 1 month share price return and 17.8% year to date share price gain. Over a longer window, total shareholder return of 27.7% over one year and 78.1% over five years points to a story where recent gains remain intact, even as new legal and financing headlines start to influence how investors weigh growth prospects against rising employment related risks.
Capitalize on the scrutiny around Darden Restaurants by stress testing your own ideas against our hand picked 30 resilient stocks with low risk scores that aim to keep legal and balance sheet surprises in check.Recent gains in Darden Restaurants now sit beside fresh legal and financing headlines. The real puzzle is whether you are paying for stronger fundamentals or a swing in sentiment as valuation comes into focus next.
Most Popular Narrative: 6% Undervalued
Darden Restaurants most followed valuation story puts fair value at $233.44, slightly above the $220.48 last close. This keeps attention on whether execution can justify that gap as legal noise rises.
Darden Restaurants is stepping up unit growth with 71 openings in fiscal 2026 and guidance for 75 to 80 new openings plus 11 Bahama Breeze conversions in fiscal 2027. The company is using smaller Yard House prototypes to lower build costs, which together can increase total system sales while spreading fixed costs and supporting earnings over time.
See why 16 investors see Darden Restaurants as 6% undervalued.
Result: Fair Value of $233.44 (UNDERVALUED)
Still, softer casual dining traffic and the risk that Olive Garden weekday lunch remains weak could challenge the Darden Restaurants thesis if those trends deepen.
Find out about the key risks to this Darden Restaurants narrative.
Another View On Darden Restaurants Valuation
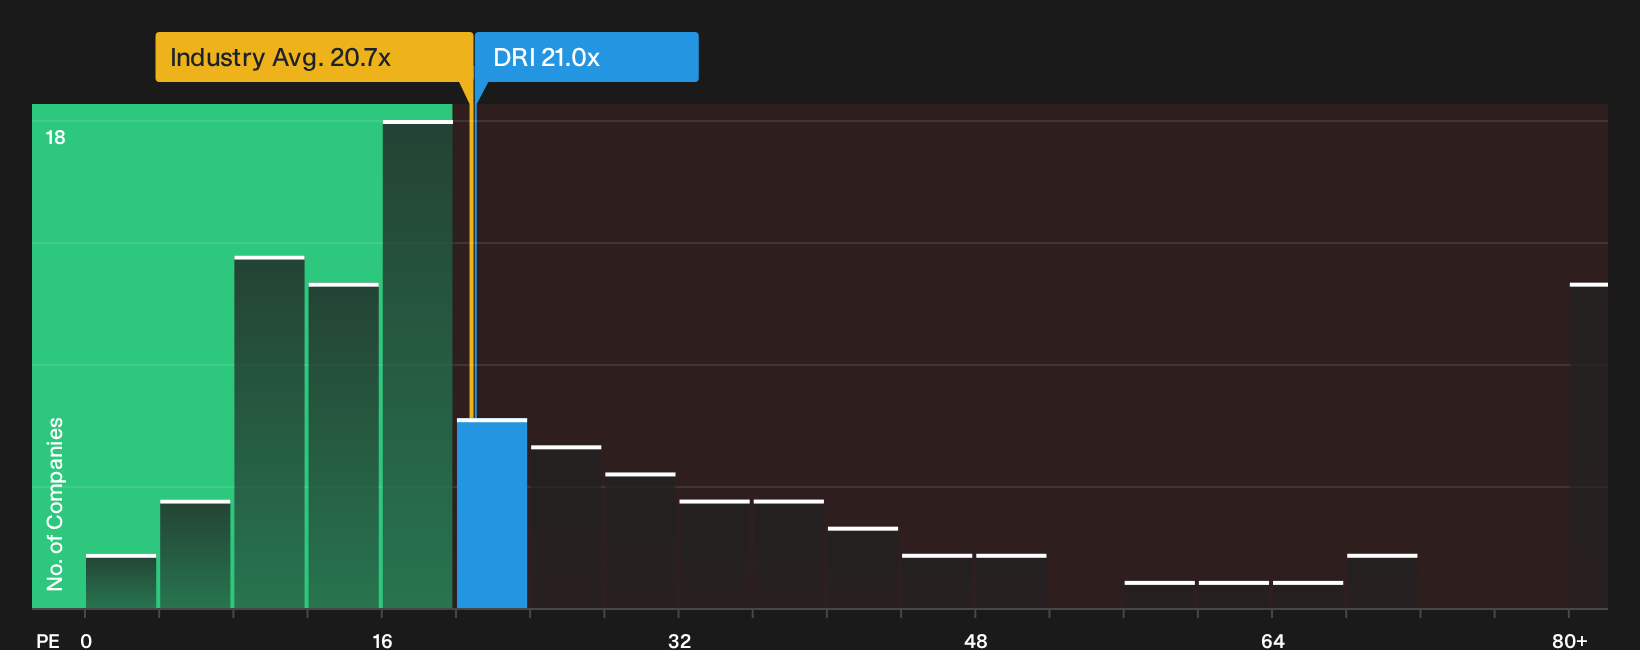
The analyst fair value story paints Darden Restaurants as 6% undervalued. The P/E tells a different story. At 21x earnings versus the US Hospitality group at 20.2x and a fair ratio of 20.4x, investors are paying a richer multiple. Is that premium really where you want to lean in today?
See what the numbers say about this price in our valuation breakdown, then compare it with our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Darden Restaurants valuation and legal risk only matter if you act on them. Pressure test your own thesis by walking through the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Darden Restaurants?
Do not stop with one legal headline and a single ticker. Broaden your watchlist with clear, rules based ideas that line up with your risk and return priorities.
- Target resilient balance sheets and steadier financial foundations by scanning our list of solid balance sheet and fundamentals (23 results) that are built to handle shocks without constant drama.
- Hunt for pricing gaps where quality and valuation meet by running through the 30 high quality undervalued stocks before the crowd catches on.
- Stack potential cash returns on top of capital gains by reviewing income focused opportunities in the 7 dividend fortresses while yields remain compelling.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com